Multi EMA Cross with Volume Price Momentum Trading Strategy
This is a comprehensive momentum trading strategy based on multiple exponential moving average (EMA) crossovers and volume-price indicators. The strategy generates trading signals by combining various indicators…
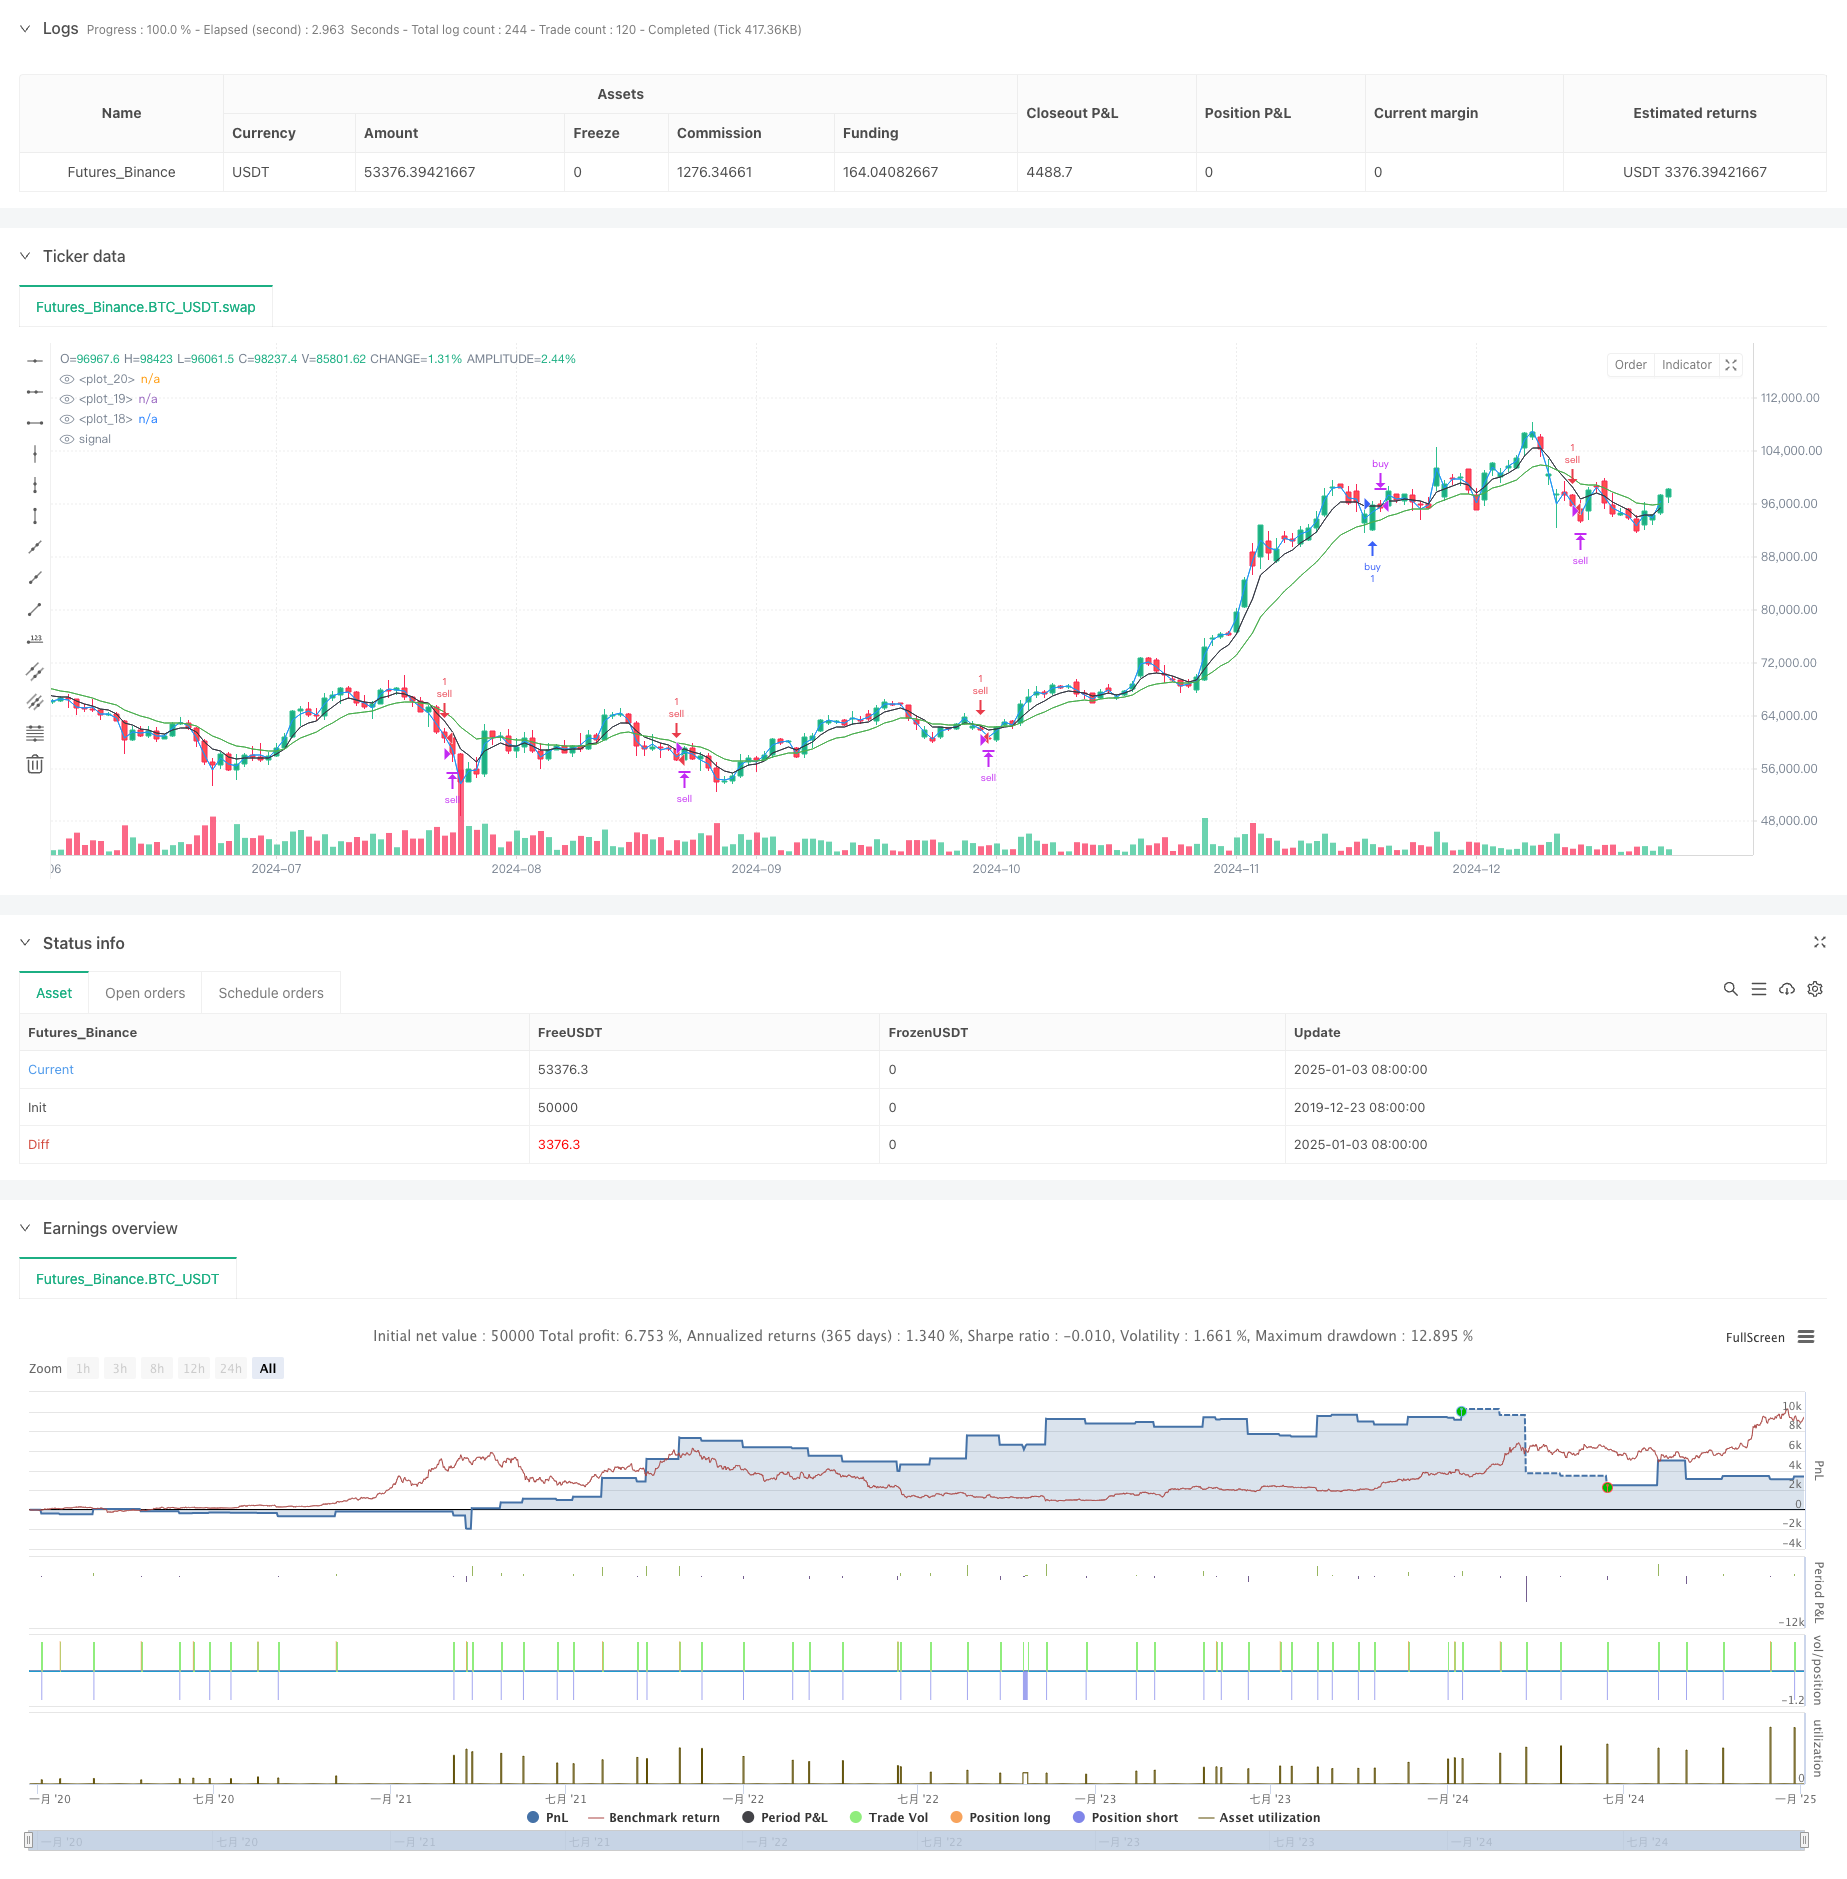
This is a comprehensive momentum trading strategy based on multiple exponential moving average (EMA) crossovers and volume-price indicators. The strategy generates trading signals by combining various indicators including fast and slow EMAs, Volume Weighted Average Price (VWAP), and SuperTrend, while incorporating intraday trading windows and price movement thresholds to control entry and exit points.
Strategy Principles
The strategy utilizes 5-day and 13-day EMAs as primary trend indicators. Long positions are triggered when the fast EMA crosses above the slow EMA with closing price above VWAP, while short positions are triggered when the fast EMA crosses below the slow EMA with closing price below VWAP. The strategy also incorporates the SuperTrend indicator for trend confirmation and stop-loss determination. Different entry conditions are set for different trading days, including price movement relative to the previous day's close and the day's high-low range.
Strategy Advantages
- Multiple technical indicators enhance trading signal reliability
- Differentiated entry conditions for different trading days better adapt to market characteristics
- Dynamic profit-taking and stop-loss mechanisms effectively control risk
- Intraday trading window restrictions avoid high volatility periods
- Previous high-low points and price movement constraints reduce the risk of chasing highs and lows
Strategy Risks
- False signals may occur in rapidly fluctuating markets
- Potential lag during initial trend reversals
- Parameter optimization may face overfitting risks
- Trading costs may impact strategy returns
- Significant drawdowns possible during highly volatile market periods
Strategy Optimization Directions
- Consider incorporating volume analysis indicators to further confirm trend strength
- Optimize parameters for different trading days to improve strategy adaptability
- Add more market sentiment indicators to enhance predictive accuracy
- Refine profit-taking and stop-loss mechanisms to improve capital efficiency
- Consider adding volatility indicators to optimize position management
Summary
This strategy achieves a combination of trend following and momentum trading through the comprehensive use of multiple technical indicators. The strategy design fully considers market diversity by adopting differentiated trading rules for different trading days. Through strict risk control and flexible profit-taking and stop-loss mechanisms, the strategy demonstrates good practical application value. Future improvements can enhance strategy stability and profitability by introducing additional technical indicators and optimizing parameter settings.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-04 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
//@version=6
strategy("S1", overlay=true)
fastEMA = ta.ema(close, 5)
slowEMA = ta.ema(close,13)
ema9 = ta.ema(close, 9)
ema100 = ta.ema(close, 100)
ema5 = ta.ema(close, 5)
ema200 = ta.ema(close, 200)

ma = ta.sma(close, 50)

mult = input.float(defval=3)
len = input.int(defval=11)
[superTrend, dir] = ta.supertrend(mult, len)
vwap1= ta.vwap(hlc3)

plot(slowEMA,color = color.green)
plot(fastEMA,color = color.black)
plot(vwap1, color = color.blue)

var dailyTaskDone = false
var gapdown = false
var gapup = false
var runup = 0.0
var biggapdown = false
var biggapup = false
var prevDayClose = 0.0
var todayLow = 0.0
var todayHigh = 0.0
var noBuyNow = false
var noSellNow = false
var buyPrice = 0.0
var sellPrice = 0.0
var todayBuyDone = false
var todaySellDone = false
var dragonflyDoji = false
var candleCount = 0
var candleCount1 = 0
var lastTrade = 9
var lastFiveCandles = false
var lastSevenCandlesS = false
var fiveEMACC = 0
candleCount := candleCount + 1
candleCount1 := candleCount1 + 1

if fiveEMACC > 0
    fiveEMACC := fiveEMACC + 1

if fiveEMACC == 6
    fiveEMACC := 0

if strategy.openprofit == 0
    candleCount := 0

if hour == 9 and minute ==15
    prevDayClose := close[1]
    todayLow := low
    todayHigh := high
    lastTrade := 9

if hour == 9 and minute ==15 and (open - close[1]) >  close*0.01
    gapup := true

if hour == 9 and minute ==15 and (open - close[1]) <  close*0.005*-1
    gapdown := true

if hour == 9 and minute ==15 and (close - close[1]) > 200
    biggapup := true

if hour == 9 and minute ==15 and (close - close[1]) < 200
    biggapdown := true

if low < todayLow
    todayLow := low
    candleCount1 := 0
if high > todayHigh
    todayHigh := high

if close > todayLow + 200
    noBuyNow := true

if close < todayHigh - 200//0.01*close
    noSellNow := false

lastFiveCandles := (close[4]<open[4] or close[3]<open[3] or close[2] < open[2] or close[1]<open[1])
lastSevenCandlesS := (close[6]>open[6] or close[5]>open[5] or close[4]>open[4] or close[3]>open[3] or close[2] > open[2] or close[1]>open[1])
if hour == 15
    dailyTaskDone := false
    gapdown := false
    gapup := false
    biggapup := false
    biggapdown := false
    noBuyNow := false
    noSellNow := false
    todayLow := 0.0
    todayHigh := 0.0
    buyPrice  := 0.0
    sellPrice := 0.0
    todayBuyDone := false
    todaySellDone := false
    dragonflyDoji := false
    lastTrade := 9

// if fastEMA < slowEMA and lastTrade == 1 and strategy.openprofit==0
//     lastTrade := 9


if fastEMA > slowEMA and lastTrade == 0 and strategy.openprofit==0
    lastTrade := 9

buy =  (dayofweek==dayofweek.thursday and (fastEMA - slowEMA > close*0.001) and close > vwap1 and close[1] > vwap1[1]) or
       (dayofweek==dayofweek.monday and (fastEMA - slowEMA > close*0.001) and close > vwap1 and close[1] > vwap1[1] and close-prevDayClose < close*0.011) or
       (dayofweek==dayofweek.tuesday and (fastEMA - slowEMA > close*0.001) and close > vwap1 and close[1] > vwap1[1] and lastFiveCandles  and close-prevDayClose < close*0.015 and close-todayLow < close*0.012) or
       (dayofweek==dayofweek.wednesday and (fastEMA - slowEMA > close*0.001) and close > vwap1 and close-prevDayClose < close*0.015 and (hour!=9 or minute>=35) and close-todayLow < close*0.012) or
       (dayofweek==dayofweek.friday and ((fastEMA - slowEMA > close*0.001))and close > vwap1 and close[1] > vwap1[1] and (hour!=9 or minute>=35))

sell=  (dayofweek==dayofweek.thursday and (hour!=9 or minute>=35) and ((slowEMA - fastEMA > close*0.00089)) and close < vwap1  and lastSevenCandlesS and close[1] < vwap1[1]) or
       (dayofweek==dayofweek.monday and ((slowEMA - fastEMA > close*0.00089)) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and todayHigh-close < close*0.008 and todayHigh-close[1] < close * 0.01 ) or
       (dayofweek==dayofweek.tuesday and  (hour!=9 or minute>=35) and (open - low < 2*(high-close)) and (close-open<10)  and not dragonflyDoji  and (slowEMA - fastEMA > close*0.00089) and close < vwap1 and close[1] < vwap1[1]  and prevDayClose-close<close*0.012 and todayHigh-close < close*0.009 and todayHigh-close[1] < close * 0.009) or
       (dayofweek==dayofweek.wednesday  and  (hour!=9 or minute>=40) and close<open and (slowEMA - fastEMA > close*0.00089) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and (close-todayLow>30 or candleCount1<1) ) or
       (dayofweek==dayofweek.friday and ((slowEMA - fastEMA > close*0.00089)) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and (hour!=9 or minute>=55) )

// buy =  (dayofweek==dayofweek.thursday and (fastEMA > slowEMA) and close > vwap1 and close[1] > vwap1[1]) or
//        (dayofweek==dayofweek.monday and (fastEMA > slowEMA) and close > vwap1 and close[1] > vwap1[1] and close-prevDayClose < close*0.011) or
//        (dayofweek==dayofweek.tuesday and (fastEMA > slowEMA) and close > vwap1 and close[1] > vwap1[1] and lastFiveCandles  and close-prevDayClose < close*0.015 and close-todayLow < close*0.012) or
//        (dayofweek==dayofweek.wednesday and (fastEMA > slowEMA) and close > vwap1 and close-prevDayClose < close*0.015 and (hour!=9 or minute>=35) and close-todayLow < close*0.012) or
//        (dayofweek==dayofweek.friday and ((fastEMA > slowEMA))and close > vwap1 and close[1] > vwap1[1] and (hour!=9 or minute>=35))

// sell=  (dayofweek==dayofweek.thursday and (hour!=9 or minute>=35) and ((slowEMA > fastEMA)) and close < vwap1  and lastSevenCandlesS and close[1] < vwap1[1]) or
//        (dayofweek==dayofweek.monday and ((slowEMA > fastEMA)) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and todayHigh-close < close*0.008 and todayHigh-close[1] < close * 0.01 ) or
//        (dayofweek==dayofweek.tuesday and  (hour!=9 or minute>=35) and (open - low < 2*(high-close)) and (close-open<10)  and not dragonflyDoji  and (slowEMA > fastEMA) and close < vwap1 and close[1] < vwap1[1]  and prevDayClose-close<close*0.012 and todayHigh-close < close*0.009 and todayHigh-close[1] < close * 0.009) or
//        (dayofweek==dayofweek.wednesday  and  (hour!=9 or minute>=40) and close<open and (slowEMA > fastEMA) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and (close-todayLow>30 or candleCount1<1) ) or
//        (dayofweek==dayofweek.friday and ((slowEMA > fastEMA)) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and (hour!=9 or minute>=55) )

dragonflyDoji:= false

// (slowEMA - fastEMA > close*0.00089 or (slowEMA-fastEMA>close*0.00049 and (high[2]>vwap or high[1]>vwap)))
if sellPrice != 0 and runup < sellPrice - low
    runup := sellPrice - low


if buyPrice != 0 and runup < high - buyPrice
    //ourlabel = label.new(x=bar_index, y=na, text=tostring(runup), yloc=yloc.belowbar)
    runup := high - buyPrice


NoBuySellTime = (hour == 15) or ((hour==14 and minute>=25)) or (hour==9 and minute<=35) or hour >= 14
//(fiveEMACC > 0 and low < fastEMA and close < vwap1)
buyexit     =  fastEMA<slowEMA or (close<superTrend and close < vwap1 and close[1] < vwap1[1]) //or strategy.openprofit > 400 or strategy.openprofit < -5000
sellexit =  slowEMA<fastEMA or (close > vwap1 and close[1] > vwap1[1] and close>superTrend) //or strategy.openprofit > 400 or strategy.openprofit < -5000

exitPosition =  (dayofweek==dayofweek.thursday and buyPrice!=0.0 and (high - buyPrice) > 50) or (dayofweek==dayofweek.thursday and sellPrice!=0.0 and (sellPrice - low) > 80) or (dayofweek==dayofweek.monday and buyPrice !=0.0 and high-buyPrice > 30) or (dayofweek==dayofweek.monday and sellPrice!=0.0 and (sellPrice - low) > 30) or (dayofweek!=dayofweek.thursday and dayofweek!=dayofweek.monday  and buyPrice!=0.0 and (high - buyPrice) > 30) or  (dayofweek!=dayofweek.thursday  and dayofweek!=dayofweek.monday and sellPrice!=0.0 and (sellPrice - low) > 30)
//code such that 2 fastema is > than 2 slowema
//exitPosition =  (sellPrice!=0 and runup >21 and strategy.openprofit < -2000) or (candleCount > 18 and strategy.openprofit > 50 and strategy.openprofit < 1000) or (dayofweek==dayofweek.thursday and buyPrice!=0.0 and (high - buyPrice) > buyPrice * 0.007) or (dayofweek==dayofweek.thursday and sellPrice!=0.0 and (sellPrice - low) > sellPrice * 0.007) or (dayofweek==dayofweek.monday and buyPrice !=0.0 and high-buyPrice > 30) or (dayofweek!=dayofweek.thursday and dayofweek!=dayofweek.monday  and buyPrice!=0.0 and (high - buyPrice) > buyPrice * 0.002) or  (dayofweek!=dayofweek.thursday  and sellPrice!=0.0 and (sellPrice - low) > sellPrice * 0.002)
//(runup >21 and strategy.openprofit < -2000) or
if  buy and fastEMA>vwap1 and (not todayBuyDone or lastTrade != 1) and not NoBuySellTime// and not dailyTaskDone //and (dayofweek==dayofweek.friday or (close-prevDayClose)<150)//and not biggapup
    strategy.entry("buy", strategy.long)
    //dailyTaskDone := true
    if buyPrice == 0.0
        fiveEMACC := 1

    buyPrice := close
    //ourlabel = label.new(x=bar_index, y=na, text=tostring(todayLow + 500), yloc=yloc.belowbar9
    todayBuyDone := true
    lastTrade := 1
    runup := 0.0

if  sell and (not todaySellDone or lastTrade != 0) and not NoBuySellTime// and not dailyTaskDone // and dayofweek!=dayofweek.friday //and (dayofweek==dayofweek.friday or (prevDayClose-close)<150)//and not biggapdown
    strategy.entry("sell", strategy.short)
    //dailyTaskDone := true
    if sellPrice == 0.0
        fiveEMACC := 1
    sellPrice := close
    todaySellDone := true
    lastTrade := 0
    runup := 0.0

// if ((fastEMA-slowEMA>18 and close>vwap and close[1]>vwap[1] and (not todayBuyDone or candleCount>12)) or (slowEMA-fastEMA>10 and close < vwap and close[1]<vwap[1] and (not todaySellDone or candleCount > 12))) and strategy.openprofit==0
// ourlabel = label.new(x=bar_index, y=na, text=tostring(abs(prevDayClose-close)), yloc=yloc.belowbar)

IntraDay_SquareOff = minute >=15 and hour >= 15
if true and (IntraDay_SquareOff or exitPosition)
    strategy.close("buy")
    strategy.close("sell")
    buyPrice := 0
    sellPrice := 0
    runup := 0.0
if  buyexit
    strategy.close("buy")
    buyPrice := 0
if sellexit
    strategy.close("sell")
    sellPrice := 0

buy1 =  ((dayofweek==dayofweek.thursday and (fastEMA - slowEMA > close*0.001) and close > vwap1 and close[1] > vwap1[1]) or
       (dayofweek==dayofweek.monday and (fastEMA - slowEMA > close*0.0013) and close > vwap1 and close[1] > vwap1[1]) or
       (dayofweek==dayofweek.tuesday and (fastEMA - slowEMA > close*0.0013) and close > vwap1 and close[1] > vwap1[1] and not gapup) or
       (dayofweek==dayofweek.wednesday and (fastEMA - slowEMA > close*0.0013) and close > vwap1 and close[1] > vwap1[1] and close-prevDayClose < close*0.0085) or
       (dayofweek==dayofweek.friday and (fastEMA - slowEMA > close*0.0013) and close > vwap1 and close[1] > vwap1[1] and close - todayLow < close*0.012))
       and dayofweek!=dayofweek.friday and (not todayBuyDone or lastTrade != 1) and not NoBuySellTime// and not dailyTaskDone //and (dayofweek==dayofweek.friday or (close-prevDayClose)<150)//and not biggapup


sell1=  ((dayofweek==dayofweek.thursday and (slowEMA - fastEMA > close*0.00079) and close < vwap1 and close[1] < vwap1[1]) or
       (dayofweek==dayofweek.monday and (slowEMA - fastEMA > close*0.00079) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and todayHigh-close < close*0.01 and todayHigh-close[1] < close * 0.01) or
       (dayofweek==dayofweek.tuesday and (slowEMA - fastEMA > close*0.00079) and close < vwap1 and close[1] < vwap1[1] and not gapdown and not dragonflyDoji and todayHigh-close < close*0.009 and todayHigh-close[1] < close * 0.009) or
       (dayofweek==dayofweek.wednesday and (slowEMA - fastEMA > close*0.00079) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and prevDayClose-close < 0.005*close) or
       (dayofweek==dayofweek.friday and (slowEMA - fastEMA > close*0.00079) and close < vwap1 and close[1] < vwap1[1] and not dragonflyDoji and prevDayClose-close < 0.005*close)) and
       dayofweek!=dayofweek.friday and (not todaySellDone or lastTrade != 0) and not NoBuySellTime// and not dailyTaskDone

// if buy1 and strategy.openprofit==0
//     ourlabel = label.new(x=bar_index, y=na, text=tostring(fastEMA - slowEMA), yloc=yloc.belowbar)
// if sell1 and strategy.openprofit==0
//     ourlabel = label.new(x=bar_index, y=na, text=tostring(slowEMA - fastEMA), yloc=yloc.belowbar)

// buy =  ((fastEMA > slowEMA and fastEMA[1] < slowEMA[1]) and (fastEMA - slowEMA) > 10) or  ((fastEMA > slowEMA and fastEMA[1] > slowEMA[1] and fastEMA[2] < slowEMA[2]) and (fastEMA - slowEMA) > 20)
// sell=  ((fastEMA < slowEMA and fastEMA[1] > slowEMA[1] ) and (slowEMA - fastEMA) > 10) or ((fastEMA < slowEMA and fastEMA[1] < slowEMA[1] and fastEMA[2] > slowEMA[2]) and (slowEMA - fastEMA) > 20)

// buy =  (fastEMA > slowEMA and fastEMA[1] < slowEMA[1])
// sell=  (fastEMA < slowEMA and fastEMA[1] > slowEMA[1] )


// buy =  ((fastEMA > slowEMA and fastEMA[1] < slowEMA[1]) and (fastEMA - slowEMA) > 10) or  ((fastEMA > slowEMA and fastEMA[1] > slowEMA[1] and fastEMA[2] < slowEMA[2]) and (fastEMA - slowEMA) > 1)
// sell=  ((fastEMA < slowEMA and fastEMA[1] > slowEMA[1] ) and (slowEMA - fastEMA) > 5)


// buy =  fastEMA > slowEMA and fastEMA[1] > slowEMA[1] and fastEMA[2] < slowEMA[2]
// sell=  fastEMA < slowEMA and fastEMA[1] < slowEMA[1] and fastEMA[2] > slowEMA[2]

//Daily chart
// buyexit = (close + 40 < slowEMA)//rsi > 65 and fastEMA > ema9 // fastEMA > ema9// close < fastEMA//(rsi > 65 and close < fastEMA and fastEMA > ema3 and close > ema200)  //strategy.openprofit < -10000 and slowEMA > ema3 and slowEMA[1] < ema3[1] and 1==2
// sellexit = (close - 40  > slowEMA)//rsi < 35 // and close > ema200) or (rsi < 35 and close < ema200 and fastEMA < ema3) //strategy.openprofit < -10000 and fastEMA < ema3 and fastEMA[1] > ema3[1] and 1==2


// buyexit = (close < superTrend)// and (close < vwap1 and close[1] < vwap1[1] and close < close[1])//and close[2] < vwap1[2]//rsi > 65 and close < fastEMA// fastEMA > ema9// close < fastEMA//(rsi > 65 and close < fastEMA and fastEMA > ema3 and close > ema200)  //strategy.openprofit < -10000 and slowEMA > ema3 and slowEMA[1] < ema3[1] and 1==2
// sellexit = (close > superTrend)// and (close > vwap1 and close[1] > vwap1[1] and close > close[1]) //and close[2] > vwap1[2]//rsi < 35// and close > ema200) or (rsi < 35 and close < ema200 and fastEMA < ema3) //strategy.openprofit < -10000 and fastEMA < ema3 and fastEMA[1] > ema3[1] and 1==2

// buyexit = (close < superTrend and close < vwap1 and close[1] < vwap1[1] and close[1] < superTrend[1]) //or strategy.openprofit > 400 or strategy.openprofit < -5000
// sellexit =  (close > superTrend and close > vwap1 and close[1] > vwap1[1] and close[1] > superTrend[1]) //or strategy.openprofit > 400 or strategy.openprofit < -5000
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-EMA-Cross-with-Volume-Price-Momentum-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Trend Following Strategy Based on Support Resistance and Momentum Indicators Across Multiple TimeframesPine Script · Momentum · 1d
- Golden Cross with Bollinger Bands Momentum StrategyPine Script · Momentum · 1d
- Oscillator Candles Momentum Trading StrategyPine Script · Momentum · 1h
- Multi factor Fusion Strategy Multi factor Fusion StrategyPine Script · Momentum · 3h