Strategy vault / Mean reversion
Multi indicator Combined Quantitative Trading Strategy
This strategy uses three technical indicators of stock price, RSI, StochRSI and Bollinger Bands, and combines trading time and direction conditions to determine buy and sell signals for quantitative trading strategies.
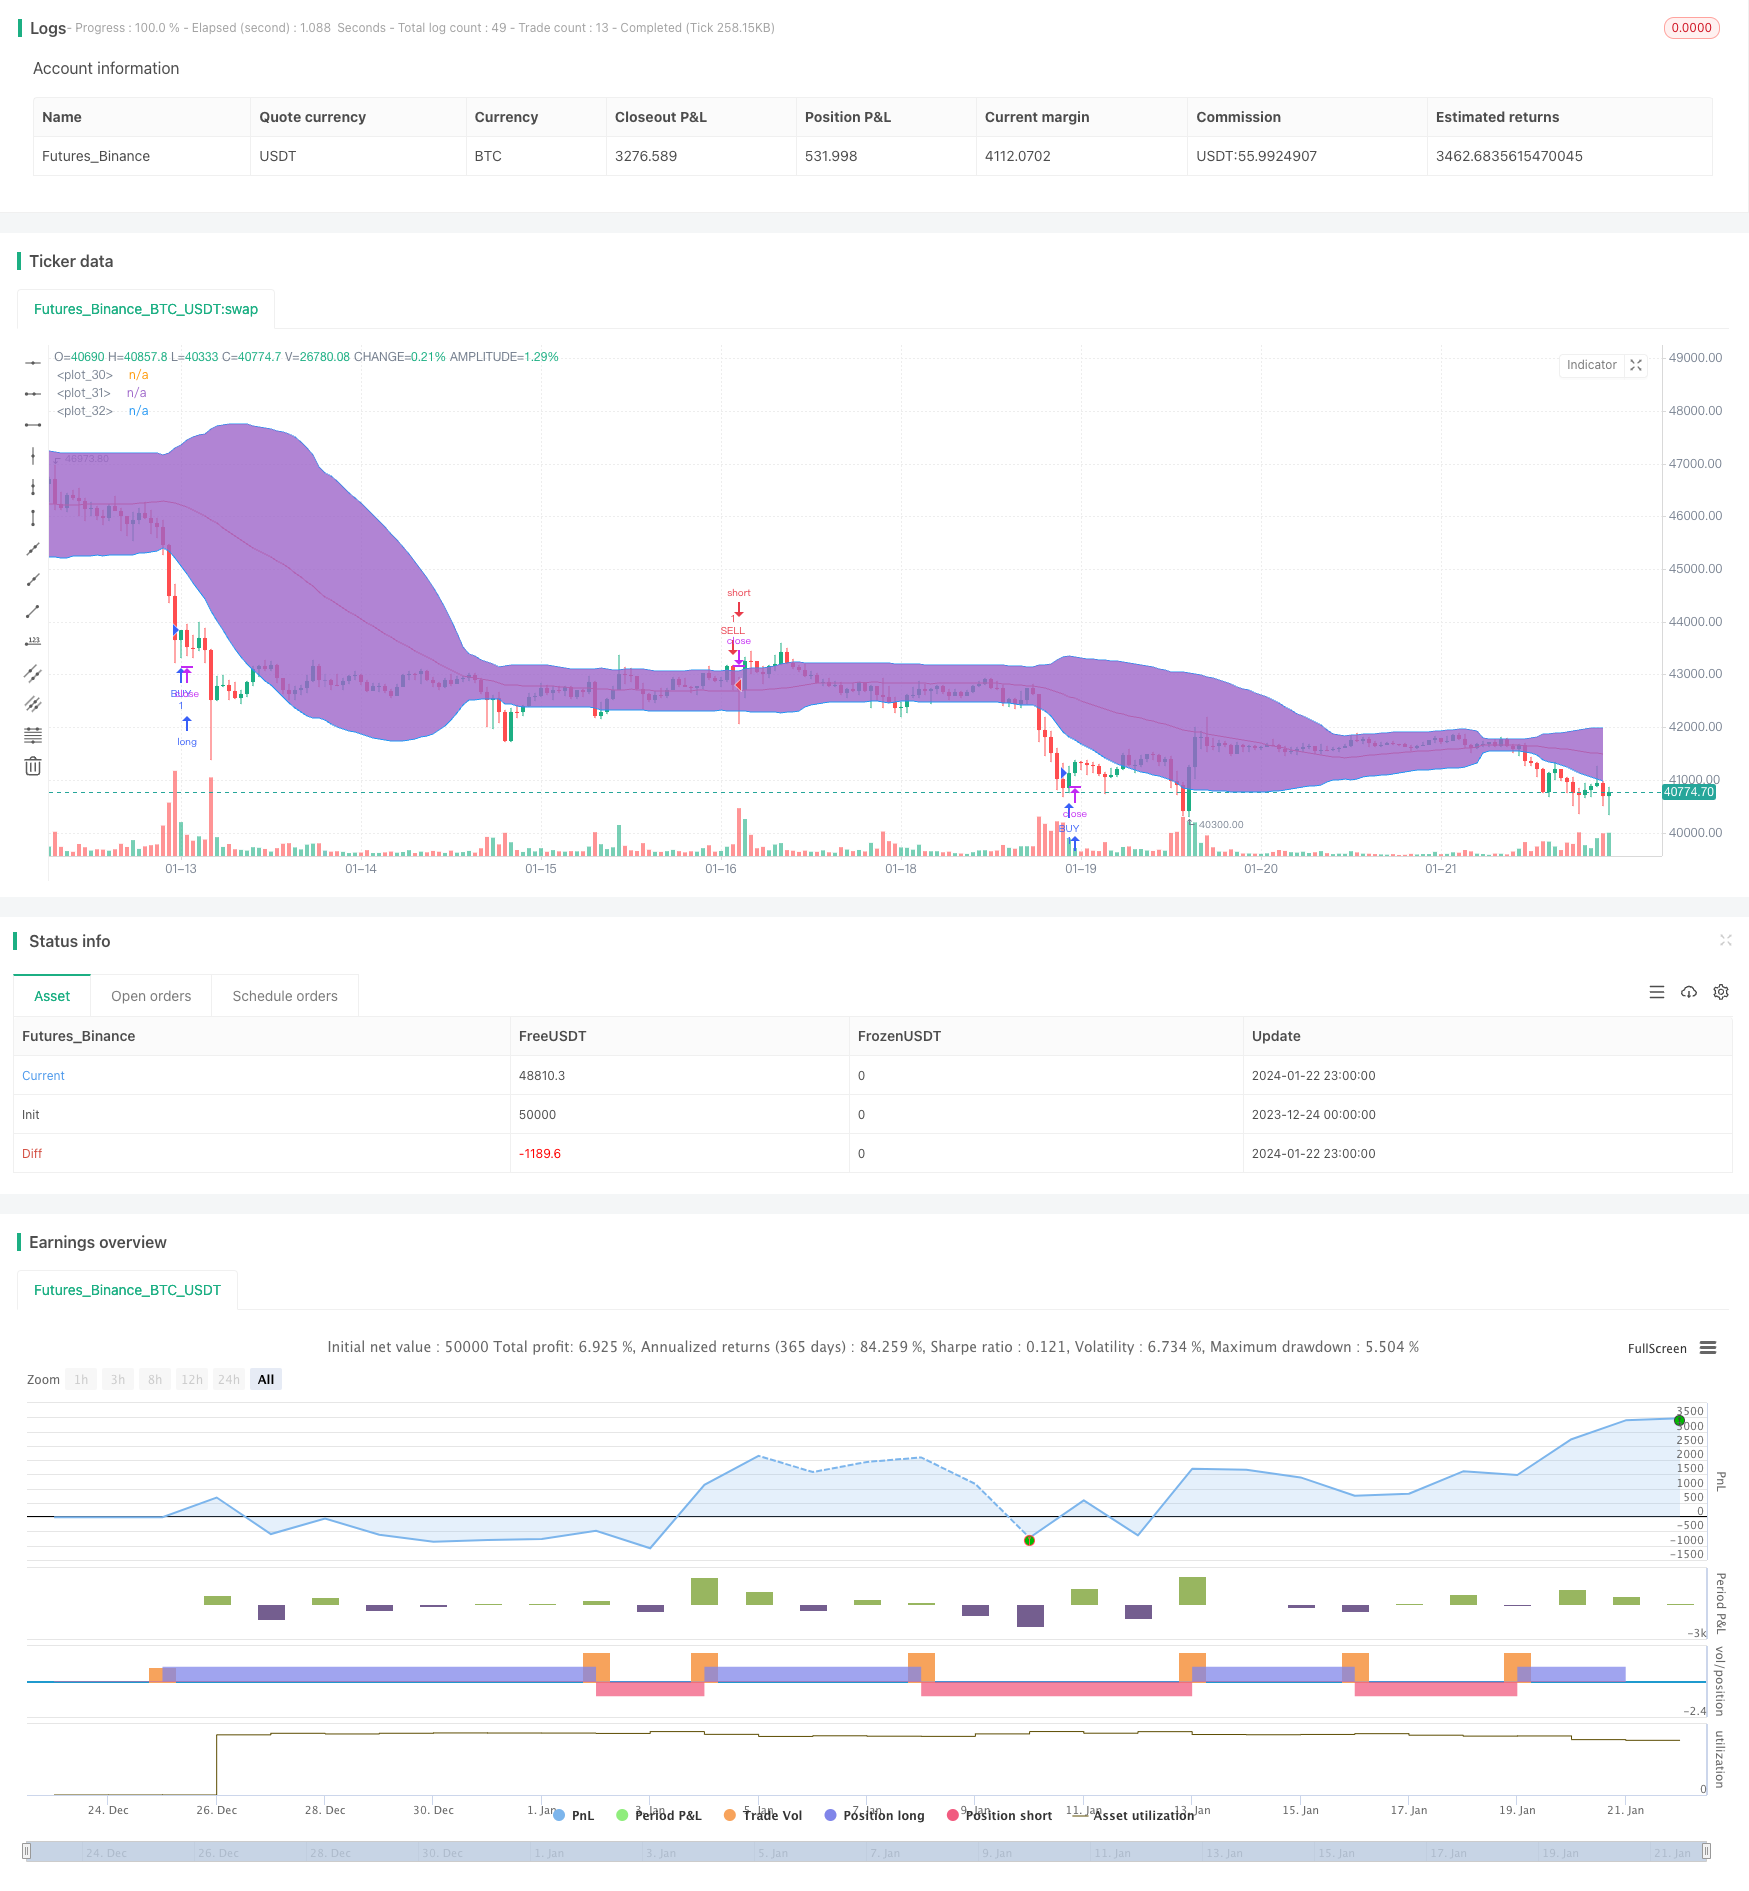
Overview
This strategy uses three technical indicators of stock price, RSI, StochRSI and Bollinger Bands, and combines trading time and direction conditions to determine buy and sell signals for quantitative trading strategies.
Principle
When the RSI indicator is less than the lower area and the StochRSI K line crosses above the D line, it is considered a buy signal. At the same time, the stock price is cheaper than the lower line of the Bollinger Band or crosses below the lower line of the Bollinger Band is also used as a basis for buying.
When the RSI indicator exceeds the upper area and the StochRSI K line crosses below the D line, it is considered a sell signal. At the same time, the stock price is higher than the upper line of the Bollinger Band or breaks through the upper line of the Bollinger Band is also used as the basis for selling.
The RSI indicator judges whether the stock price is overbought or oversold, StochRSI judges the momentum of the stock price, and Bollinger Bands judges whether the stock price is running at high levels and cheap. Multiple indicators combine to determine buying and selling.
Advantage Analysis
This is a multi-indicator combined strategy with wide coverage of indicators and comprehensive judgment basis. Crossing is required between the current stock price or indicator and its threshold before judging the signal, which has a certain filtering effect on false signals.
Time condition restrictions are added before placing orders to avoid greater risks during specific time periods.
By combining the judgments of multiple indicators, more types of trends can be matched to improve the effectiveness of the strategy.
Risk Analysis
The strategy relies mainly on three types of indicators. If the indicator gives a wrong signal, the strategy will cause losses. Indicators should verify each other and cannot completely rely on a certain indicator. For example, RSI oscillation in a certain period of time will increase the possibility of issuing false signals.
The time judgment conditions added in the strategy may also miss favorable market conditions.
If the stock selection is inappropriate, for example, stocks with severe exaggeration effects, the validity of these indicators will be greatly reduced. The applicability of stocks to these indicators should be studied.
Optimization
Increase risk control measures such as maximum drawdown to limit losses.
Adjust the parameters of the indicator to better match the selected stocks. For example, speed up the RSI parameters to detect faster price changes.
Increase filtering mechanisms, such as suspend trading when the stock price is in the middle of the Bollinger Band to avoid oscillating market conditions. And stop ordering near opening and closing to avoid gap risk.
Stock selection can refer to fundamentals to avoid stocks with serious financial fraud. Industry and market value judgments can also be added to select large-cap stocks.
Summary
This is a typical multi-variable technical indicator strategy with a balanced mix of indicators and extensive coverage. At the same time, the order conditions are rigorous, which can effectively select stocks to achieve profit, and the drawdown will be controlled within a certain range. Through the optimization of indicators and parameters, it can better adapt to the market. At the same time increase risk control mechanism to minimize risk to further improve the stability and reliability of the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 6 | lengthrsi |
| v_input_2 | 20 | overSold |
| v_input_3 | 70 | overBought |
| v_input_4 | 3 | smoothK |
| v_input_5 | 3 | smoothD |
| v_input_6 | 14 | lengthRSI |
| v_input_7 | 14 | lengthStoch |
| v_input_8_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_9 | 50 | bblength |
| v_input_10 | 1.5 | Multiplier for BB Upper Band |
| v_input_11 | 1.5 | Multiplier for BB Lower Band |
| v_input_12 | 2018 | yearfrom |
| v_input_13 | 2019 | yearuntil |
| v_input_14 | 6 | monthfrom |
| v_input_15 | 12 | monthuntil |
| v_input_16 | true | dayfrom |
| v_input_17 | 31 | dayuntil |
Source Pine Script
/*backtest
start: 2023-12-24 00:00:00
end: 2024-01-23 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version= 2
strategy("RSI+STOCHRSI+BB Strategy", overlay=true)
lengthrsi = input(6)
overSold = input( 20 )
overBought = input( 70 )
price = close
vrsi = rsi(price, lengthrsi)

smoothK = input(3, minval=1)
smoothD = input(3, minval=1)
lengthRSI = input(14, minval=1)
lengthStoch = input(14, minval=1)
src = input(close, title="RSI Source")

rsi1 = rsi(src, lengthRSI)
k = sma(stoch(rsi1, rsi1, rsi1, lengthStoch), smoothK)
d = sma(k, smoothD)

bblength = input(50)
bbupmult =input(1.5,title="Multiplier for BB Upper Band")
bblowmult = input(1.5,title="Multiplier for BB Lower Band")

basis =  sma(close,bblength)

devup = bbupmult * stdev(close, bblength)
devlow = bblowmult * stdev(close, bblength)

upper = basis + devup
lower = basis - devlow
plot(basis, color=red)
p1 = plot(upper, color=blue)
p2 = plot(lower, color=blue)
fill(p1, p2)


yearfrom = input(2018)
yearuntil =input(2019)
monthfrom =input(6)
monthuntil =input(12)
dayfrom=input(1)
dayuntil=input(31)


if (  ( crossover(k,d)) and ( crossover(vrsi,overSold) or vrsi<overSold)  and (  (price<lower) or crossover(price,lower) ) )
    strategy.entry("BUY", strategy.long, stop=close, oca_name="TREND",  comment="BUY")

else
    strategy.cancel(id="BUY")


if ( ( crossunder(k,d) ) and ( (vrsi >overBought) or crossunder(vrsi,overBought) ) and  ( (price>upper) or crossunder(price,upper) ))

    strategy.entry("SELL", strategy.short,stop=close, oca_name="TREND",  comment="SELL")
else
    strategy.cancel(id="SELL")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-indicator-Combined-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- Modified Bollinger Bands StrategyPine Script · Mean reversion · 1h
- Multi Factor Strategy CombinationPine Script · Mean reversion · 1m
- Williams VIX Fix StrategyPine Script · Mean reversion · 1d
- Bollinger Bands Stochastic RSI ExtremePine Script · Mean reversion · 15m