Multi Indicator Dynamic Volatility Trading Strategy
This strategy is an intelligent trading system based on multiple technical indicators, combining signals from Moving Averages (MA), Volume, and Average True Range (ATR) to capture market opportunities through…
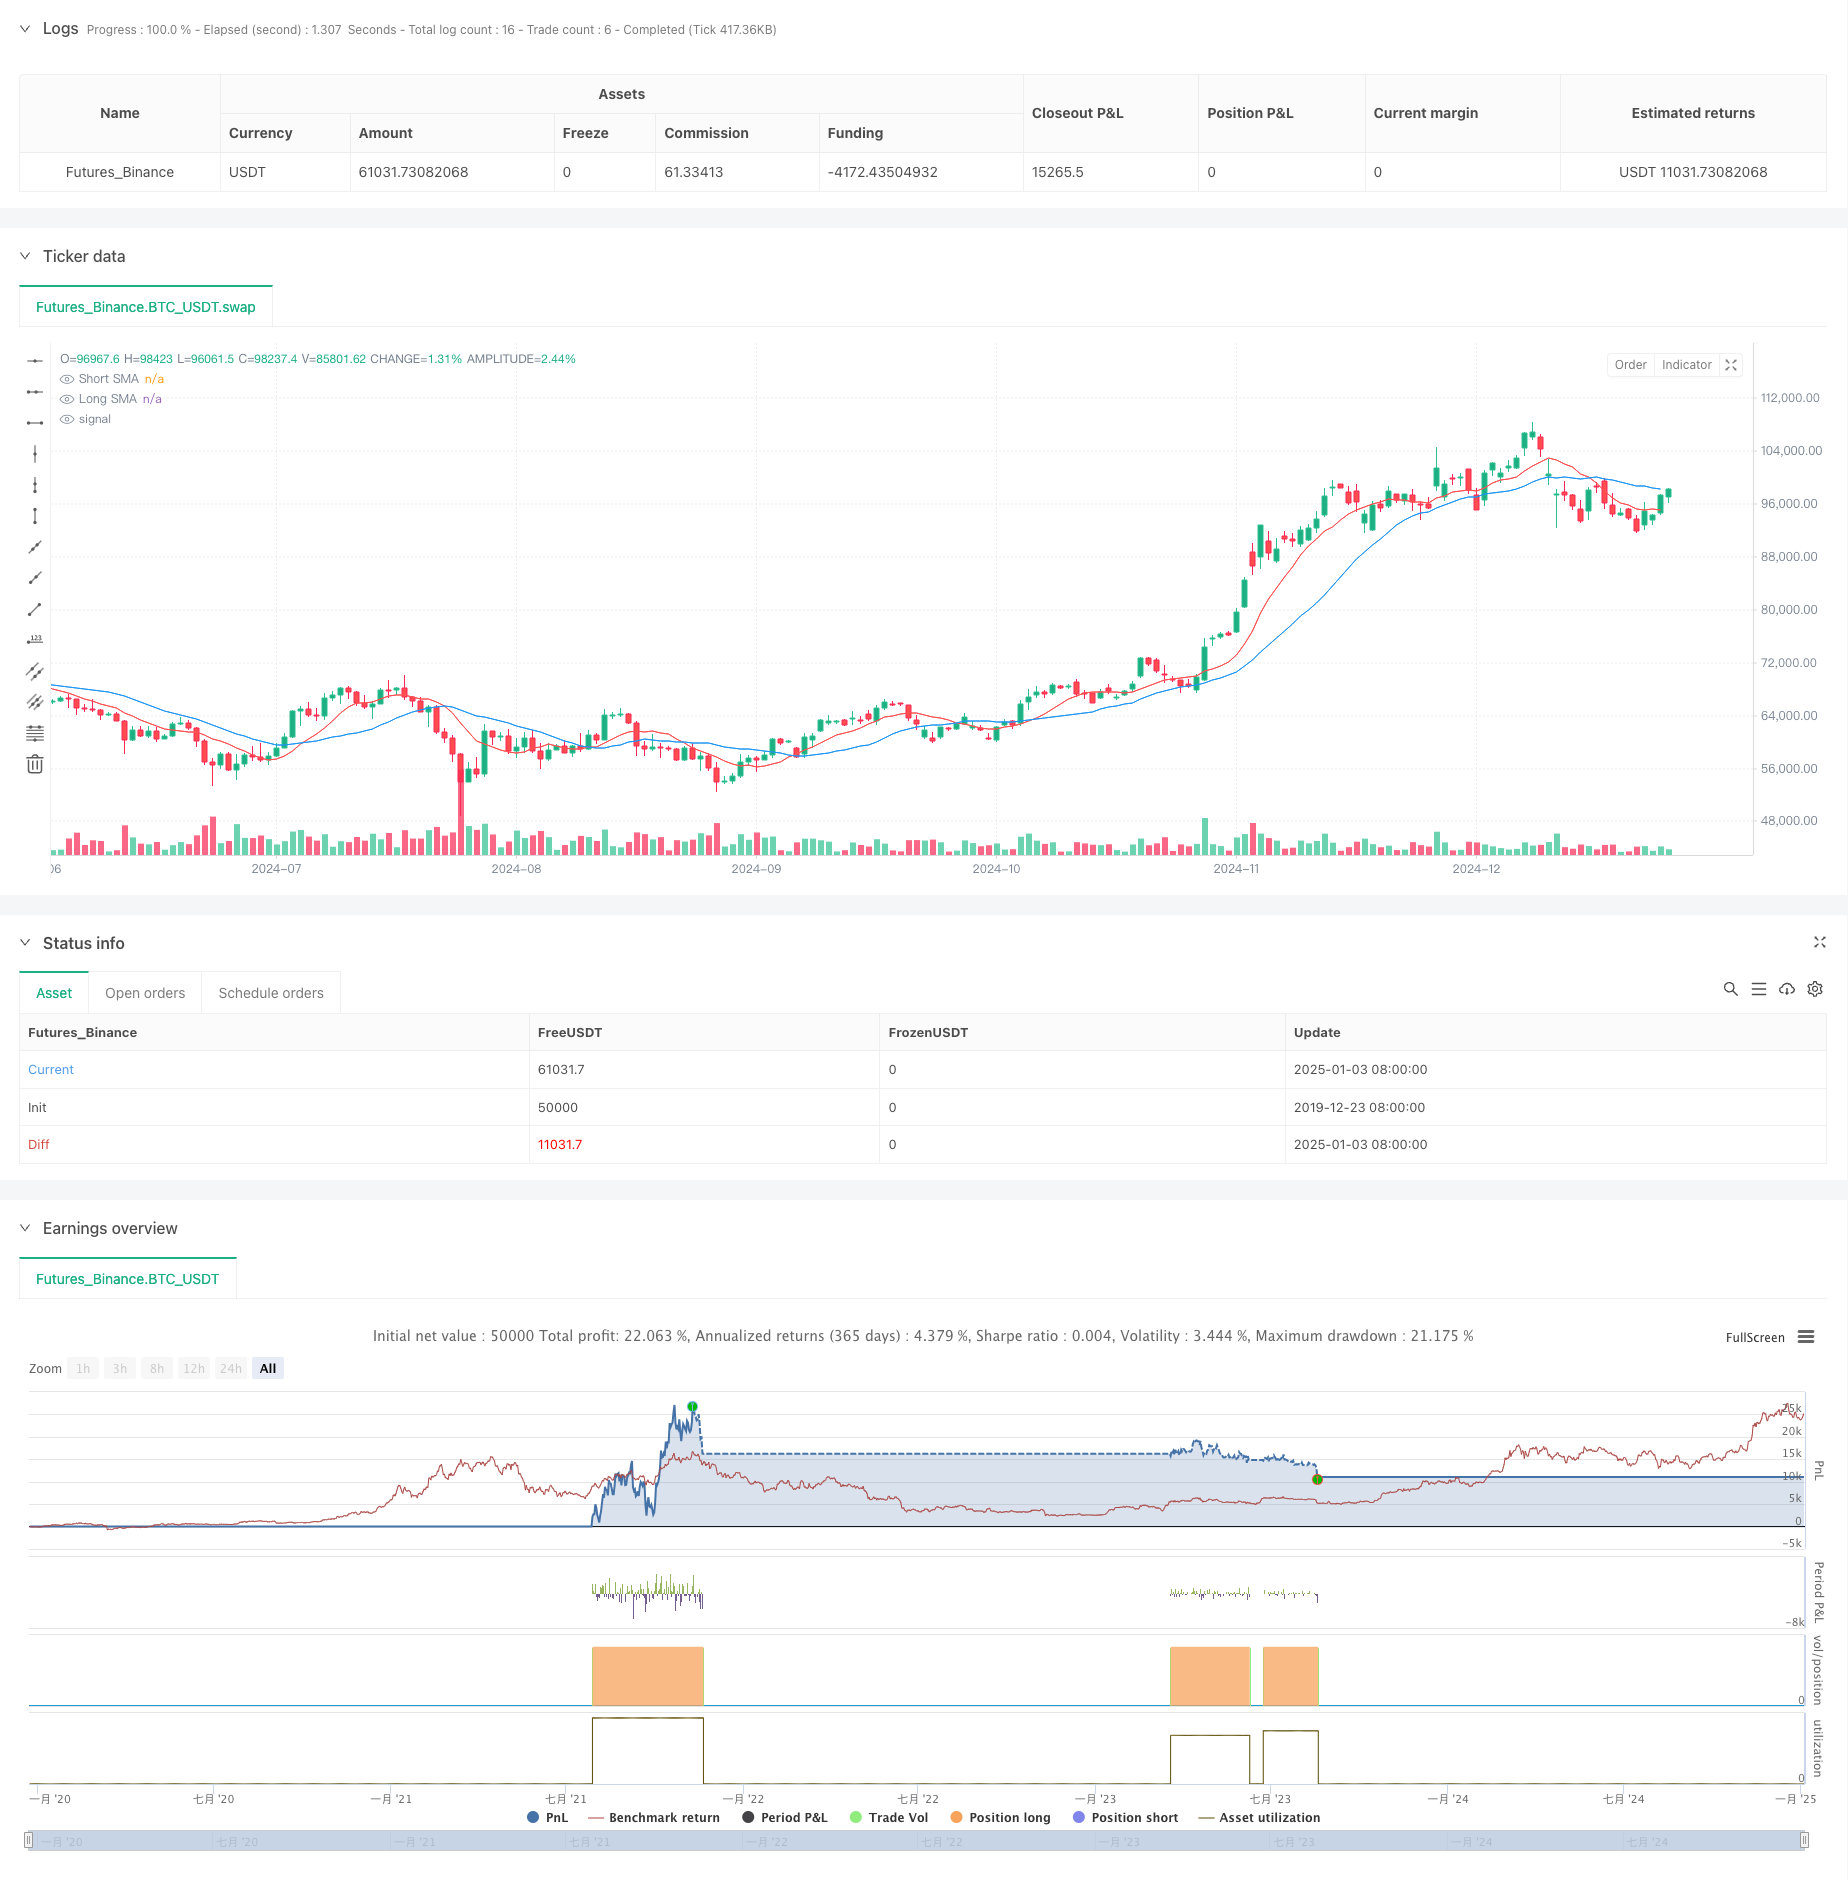
Overview
This strategy is an intelligent trading system based on multiple technical indicators, combining signals from Moving Averages (MA), Volume, and Average True Range (ATR) to capture market opportunities through comprehensive analysis of price trends, trading activity, and market volatility. The strategy employs a dual moving average system as the primary trend indicator, while incorporating volume and volatility as trading filters to achieve multiple validations of trading signals.
Strategy Principle
The core logic is based on three dimensions:
- Trend Dimension: Uses 9-day and 21-day Simple Moving Averages (SMA) to construct a dual MA system, identifying trend direction through golden and death crosses.
- Volume Dimension: Calculates 21-day average volume, requiring current volume to exceed 1.5 times the average, ensuring sufficient market liquidity.
- Volatility Dimension: Employs 14-day ATR to measure market volatility, requiring current volatility to be above its mean, ensuring adequate price movement potential.
Trading signals are generated only when conditions in all three dimensions are simultaneously satisfied, significantly improving trading accuracy through this multi-filter mechanism.
Strategy Advantages
- High Signal Reliability: Cross-validation through multiple technical indicators significantly reduces false breakouts.
- Strong Adaptability: Strategy parameters can be flexibly adjusted for different market environments.
- Comprehensive Risk Control: Effective risk management through dual filtering of volatility and volume.
- Clear Execution Logic: Simple and intuitive strategy logic, easy to understand and maintain.
- High Automation Level: Includes complete signal generation and alert mechanisms, supporting automated trading.
Strategy Risks
- Lag Risk: Moving averages have inherent lag, potentially causing delayed entry points.
- Choppy Market Risk: May generate frequent false signals in range-bound markets.
- Parameter Sensitivity: Strategy effectiveness is sensitive to parameter settings, requiring adjustment in different market environments.
- Liquidity Risk: May struggle to meet trading conditions in markets with low volume.
Strategy Optimization Directions
- Incorporate Trend Strength Indicators: Consider adding ADX or DMI indicators to improve trend assessment accuracy.
- Optimize Stop-Loss Mechanism: Suggest implementing ATR-based dynamic stop-loss for more flexible risk control.
- Enhance Signal Filtering: Consider introducing RSI for auxiliary judgment to reduce false signals.
- Improve Position Management: Recommend dynamic position sizing based on volatility levels.
- Market Sentiment Factors: Consider incorporating market sentiment indicators to enhance strategy adaptability.
Summary
This strategy constructs a comprehensive trading decision system through the synergistic analysis of multiple technical indicators. The design thoroughly considers market characteristics including trends, liquidity, and volatility, demonstrating strong practicality and reliability. Through continuous optimization and improvement, the strategy shows promise for maintaining stable performance across various market environments. Its modular design provides a solid foundation for future extensions, allowing flexible adjustments and optimizations based on actual needs.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-04 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Advanced Trading Strategy", overlay=true)

// Parâmetros de entrada
shortPeriod = input.int(9, title="Short Period", minval=1)
longPeriod = input.int(21, title="Long Period", minval=1)
volumeThreshold = input.float(1.5, title="Volume Threshold Multiplier", minval=0.1)
volatilityPeriod = input.int(14, title="Volatility Period", minval=1)

// Cálculo das médias móveis
shortSMA = ta.sma(close, shortPeriod)
longSMA = ta.sma(close, longPeriod)

// Cálculo do volume médio
averageVolume = ta.sma(volume, longPeriod)

// Cálculo da volatilidade (ATR - Average True Range)
volatility = ta.atr(volatilityPeriod)

// Condições de compra e venda baseadas em médias móveis
maBuyCondition = ta.crossover(shortSMA, longSMA)
maSellCondition = ta.crossunder(shortSMA, longSMA)

// Verificação do volume
volumeCondition = volume > averageVolume * volumeThreshold

// Condição de volatilidade (volatilidade acima de um certo nível)
volatilityCondition = volatility > ta.sma(volatility, volatilityPeriod)

// Condições finais de compra e venda
buyCondition = maBuyCondition and volumeCondition and volatilityCondition
sellCondition = maSellCondition and volumeCondition and volatilityCondition

// Plotando as médias móveis
plot(shortSMA, title="Short SMA", color=color.red)
plot(longSMA, title="Long SMA", color=color.blue)

// Sinal de compra
if (buyCondition)
    strategy.entry("Buy", strategy.long)

// Sinal de venda
if (sellCondition)
    strategy.close("Buy")

// Plotando sinais no gráfico
plotshape(series=buyCondition, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="BUY")
plotshape(series=sellCondition, title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL")

// Configurando alertas
alertcondition(buyCondition, title="Buy Alert", message="Buy Signal Triggered")
alertcondition(sellCondition, title="Sell Alert", message="Sell Signal Triggered")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Indicator-Dynamic-Volatility-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Profit rate theory volatility index quantification strategyPine Script · Volatility · 3h
- Multi Indicator Volatility Trading RSI EMA ATR StrategyPine Script · Volatility · 3m
- Volatility Capture RSI Bollinger Band StrategyPine Script · Volatility · 15m
- Big Snapper Alerts R30 Chaiking Volatility condition TP RSIPine Script · Volatility · 2h
- Multi Indicator Dynamic Position Size Volatility Adaptive Quantitative Trading StrategyPine Script · Volatility · 1d
- Rose Cross Star Dual Indicator Volatility StrategyPine Script · Volatility · 1d