Strategy vault / Trend following
Multi Indicator Trend Following Strategy with ADX Dynamic Trading System
This strategy is a comprehensive trading system that combines multiple technical indicators including Exponential Moving Average (EMA), Relative Strength Index (RSI), and Average True Range (ATR), while incorporating…
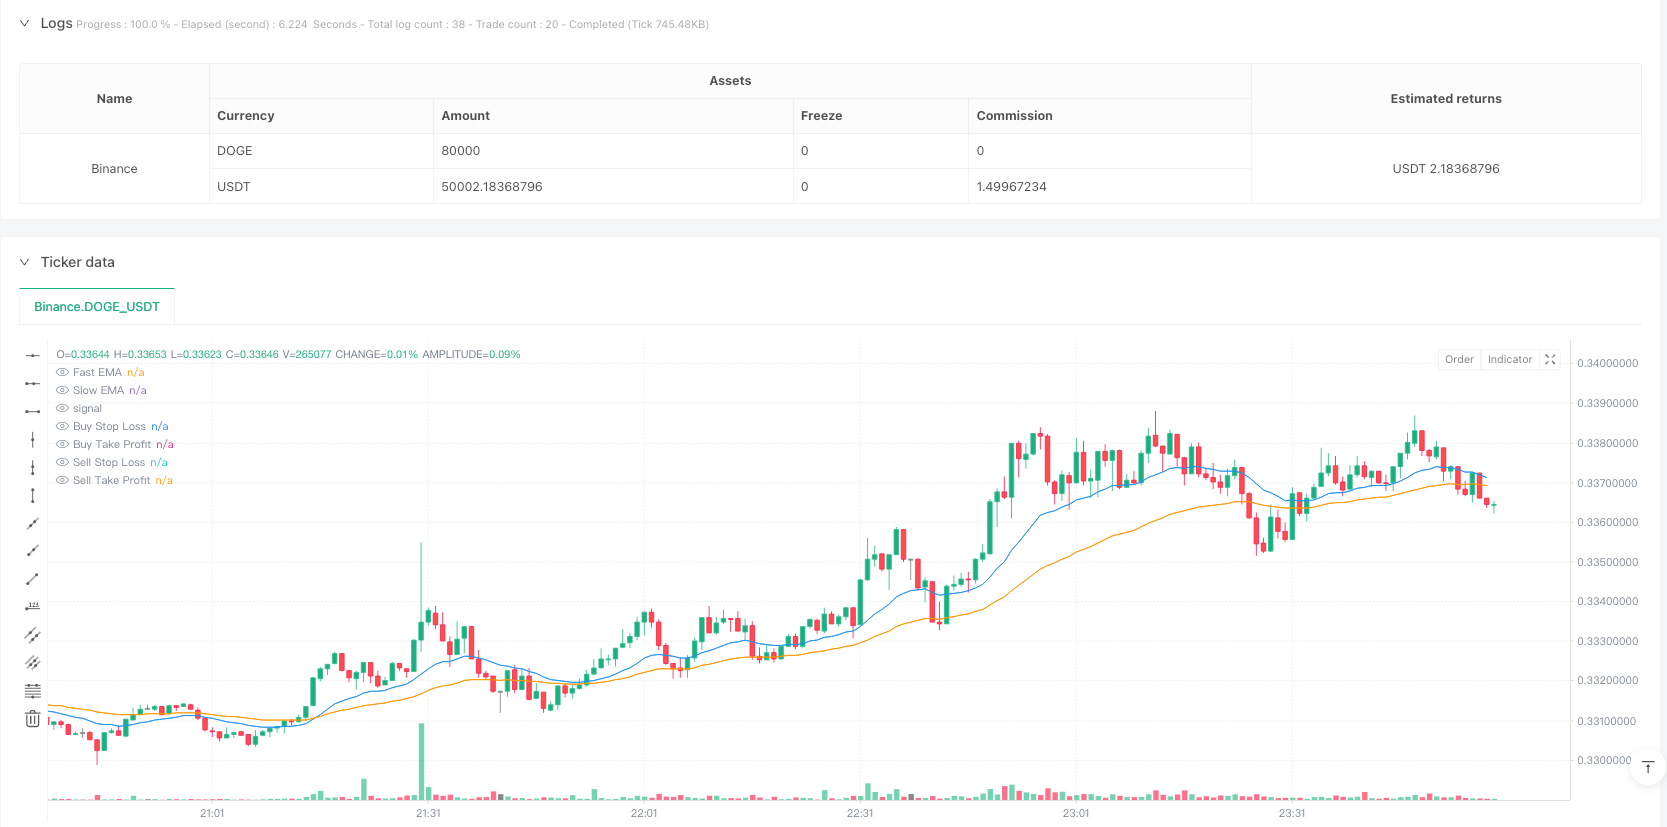
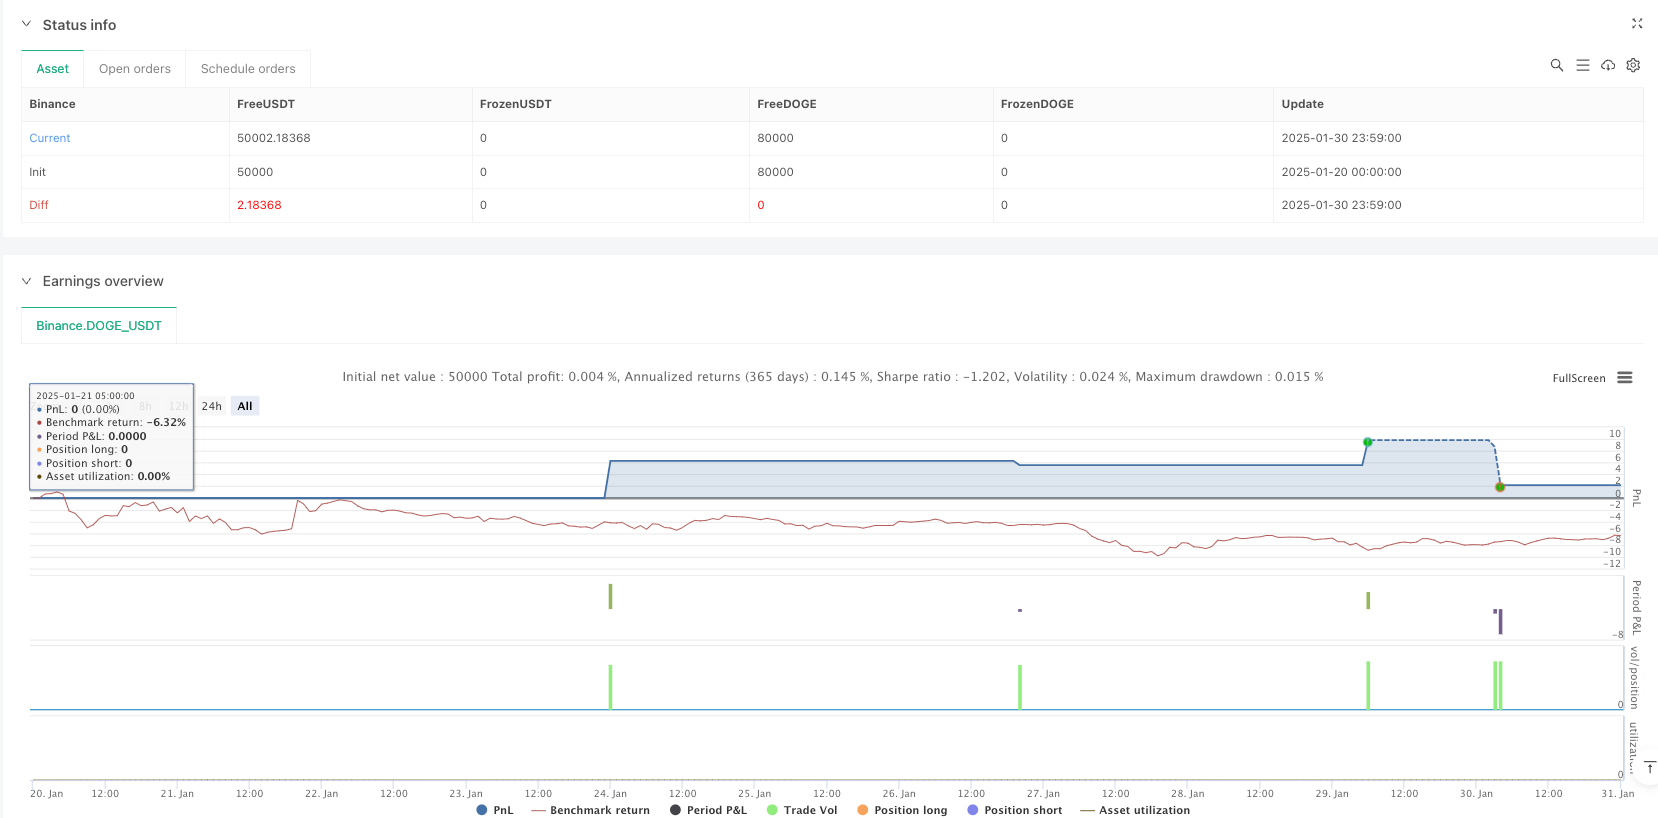
Overview
This strategy is a comprehensive trading system that combines multiple technical indicators including Exponential Moving Average (EMA), Relative Strength Index (RSI), and Average True Range (ATR), while incorporating the Average Directional Index (ADX) to enhance trend identification accuracy. The system confirms entry points through multiple signals and utilizes ATR for dynamic stop-loss and take-profit management.
Strategy Principles
The core strategy captures market trends through multiple technical indicators:
- Uses fast (20-period) and slow (50-period) EMAs to determine trend direction
- Incorporates ADX (14-period) to confirm trend strength, requiring ADX>20 for valid trends
- Utilizes RSI (14-period) to identify overbought/oversold opportunities, triggering buys above 30 and sells below 70
- Employs ATR (14-period) for dynamic stop-loss and take-profit levels, with a 2:1 risk-reward ratio
Strategy Advantages
- Multiple signal confirmation reduces false signals
- ADX integration enhances trend identification reliability
- Dynamic stop-loss and take-profit mechanism adapts to market volatility
- Strict risk control ensures manageable risk per trade
- Clear strategy logic with adjustable parameters
Strategy Risks
- Multiple indicators may lead to delayed signals
- Frequent trading may occur in ranging markets
- ADX indicator may generate delayed signals in certain market conditions
- Parameters require optimization for different market environments
Strategy Optimization
- Consider adding volume indicators to enhance signal reliability
- Implement volatility filters to adjust positions during high volatility periods
- Develop adaptive parameter mechanisms based on market conditions
- Add trend strength classification for dynamic position management
- Optimize stop-loss and take-profit logic with trailing stops
Summary
This strategy builds a comprehensive trend-following trading system through the organic combination of multiple technical indicators. While ensuring trading accuracy, it maintains safety through strict risk control. Although there is room for optimization, the overall framework provides practical value and extensibility.
Source Pine Script
/*backtest
start: 2025-01-20 00:00:00
end: 2025-01-31 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Binance","currency":"DOGE_USDT"}]
*/

//@version=5
strategy("Enhanced GBP/USD Strategy with ADX", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=1)

// === Input Parameters ===
emaFastLength = input.int(20, title="Fast EMA Length")
emaSlowLength = input.int(50, title="Slow EMA Length")
rsiLength = input.int(14, title="RSI Length")
rsiOverbought = input.int(70, title="RSI Overbought")
rsiOversold = input.int(30, title="RSI Oversold")
atrLength = input.int(14, title="ATR Length")
adxLength = input.int(14, title="ADX Length")
riskToReward = input.float(2.0, title="Risk-Reward Ratio (R:R)")
slMultiplier = input.float(1.5, title="SL Multiplier (ATR)")

// === Indicator Calculations ===
emaFast = ta.ema(close, emaFastLength)
emaSlow = ta.ema(close, emaSlowLength)
rsi = ta.rsi(close, rsiLength)
atr = ta.atr(atrLength)

// === ADX Calculation ===
// Components of ADX
tr = ta.rma(ta.tr, adxLength)  // True Range smoothed
plusDM = ta.rma(math.max(high - high[1], 0), adxLength)  // +DM
minusDM = ta.rma(math.max(low[1] - low, 0), adxLength)   // -DM
plusDI = (plusDM / tr) * 100
minusDI = (minusDM / tr) * 100
dx = math.abs(plusDI - minusDI) / (plusDI + minusDI) * 100
adx = ta.rma(dx, adxLength)  // Final ADX value

// === Entry Conditions ===
isUptrend = emaFast > emaSlow and adx > 20
isDowntrend = emaFast < emaSlow and adx > 20

buySignal = isUptrend and ta.crossover(rsi, rsiOversold)
sellSignal = isDowntrend and ta.crossunder(rsi, rsiOverbought)

// === Stop-Loss and Take-Profit ===
slDistance = atr * slMultiplier
tpDistance = slDistance * riskToReward

buySL = buySignal ? close - slDistance : na
buyTP = buySignal ? close + tpDistance : na
sellSL = sellSignal ? close + slDistance : na
sellTP = sellSignal ? close - tpDistance : na

// === Execute Trades ===
if buySignal
    strategy.entry("Buy", strategy.long)
    strategy.exit("Buy TP/SL", from_entry="Buy", stop=buySL, limit=buyTP)

if sellSignal
    strategy.entry("Sell", strategy.short)
    strategy.exit("Sell TP/SL", from_entry="Sell", stop=sellSL, limit=sellTP)

// === Plotting ===
plot(emaFast, title="Fast EMA", color=color.blue)
plot(emaSlow, title="Slow EMA", color=color.orange)

plotshape(buySignal, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="BUY")
plotshape(sellSignal, title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL")

plot(buySL, title="Buy Stop Loss", color=color.red, linewidth=1)
plot(buyTP, title="Buy Take Profit", color=color.green, linewidth=1)
plot(sellSL, title="Sell Stop Loss", color=color.red, linewidth=1)
plot(sellTP, title="Sell Take Profit", color=color.green, linewidth=1)

// === Alerts ===
alertcondition(buySignal, title="Buy Alert", message="Buy Signal Detected!")
alertcondition(sellSignal, title="Sell Alert", message="Sell Signal Detected!")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Indicator-Trend-Following-Strategy-with-ADX-Dynamic-Trading-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- Adaptive Dynamic Stop Loss and Take Profit Strategy Based on EMA Crossover and RSI FilterPine Script · Trend following
- Dynamic Trend Identification Strategy with Exponential Moving Average and Adaptive Volatility ThresholdPine Script · Trend following · 1h
- Multi Indicator Crossover Dynamic Stop Loss Trend Following StrategyPine Script · Trend following · 1d
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- Dual Trend Strategy with EMA Crossover and RSI FilterPine Script · Trend following · 1d