Strategy vault / Trend following
Multi Indicator Trend Following Strategy with Dynamic Channel and Moving Average Trading System
This strategy is a multi-indicator trading system that combines G-Channel, Exponential Moving Average (EMA), and Average True Range (ATR). It identifies trading signals through dynamic support/resistance levels and…
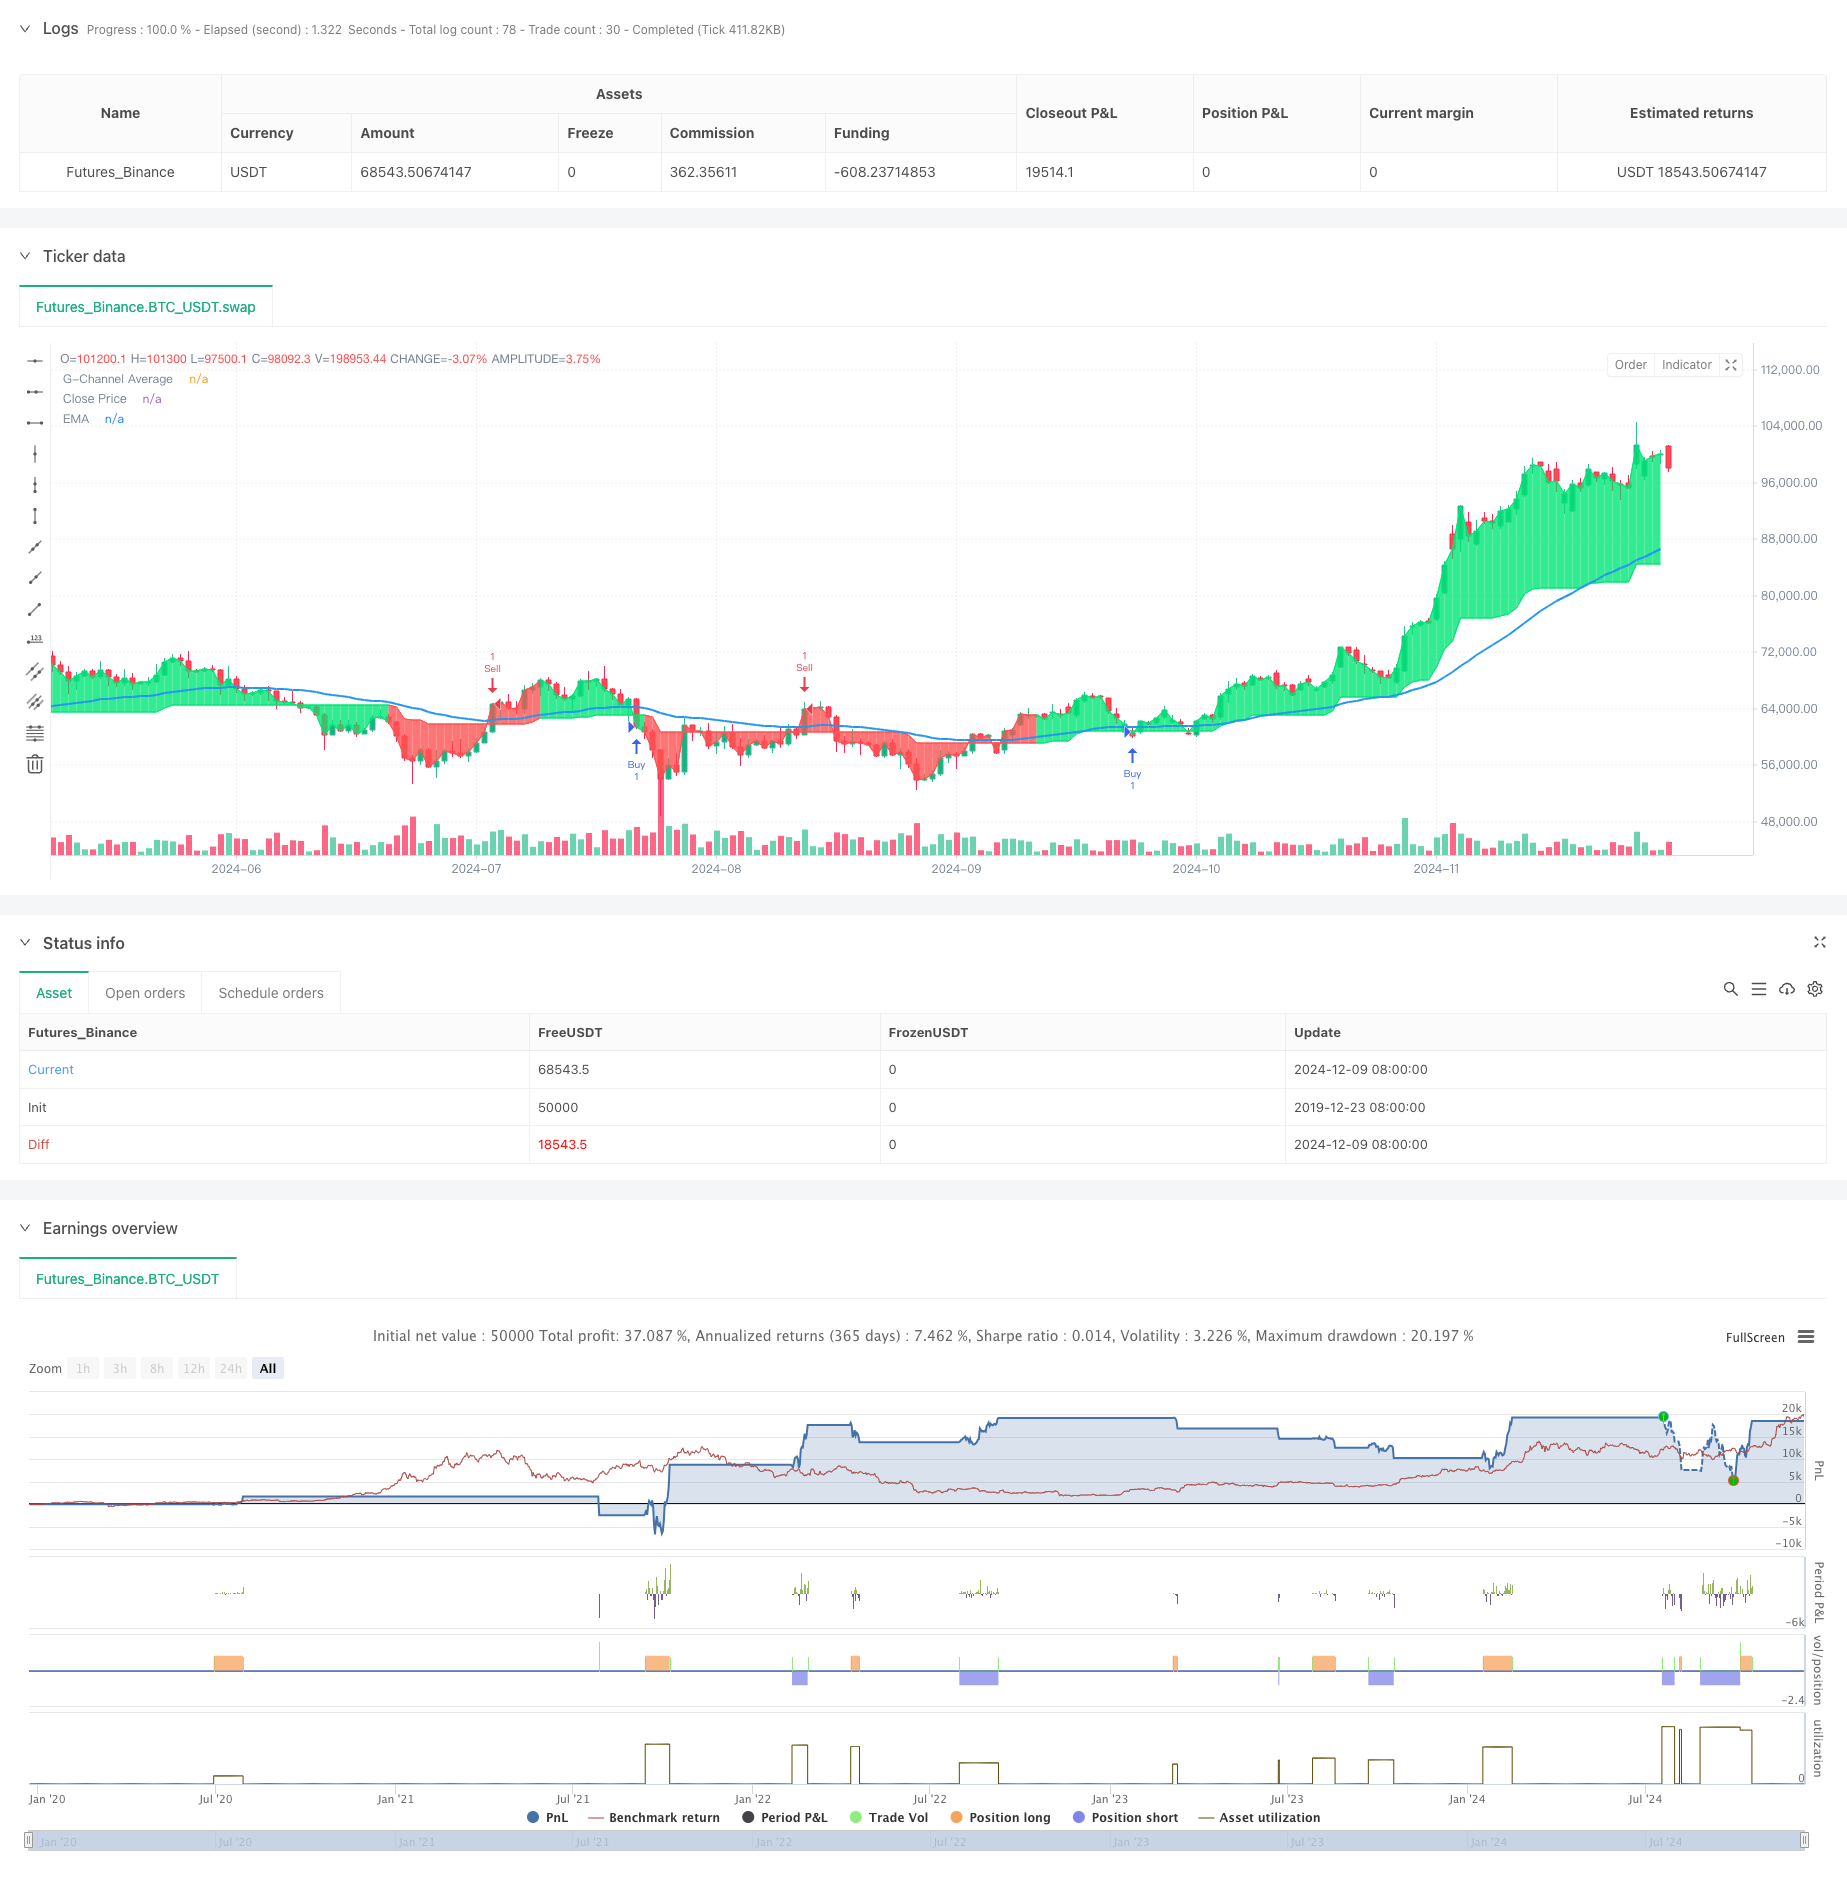
Overview
This strategy is a multi-indicator trading system that combines G-Channel, Exponential Moving Average (EMA), and Average True Range (ATR). It identifies trading signals through dynamic support/resistance levels and trend confirmation, while managing risk using ATR-based stop-loss and take-profit levels. The system emphasizes reliability and risk control, suitable for traders seeking a robust trading approach.
Strategy Principles
The core logic of the strategy is based on the following key components:
- G-Channel calculates dynamic support and resistance levels, continuously adjusting upper and lower bands
- EMA confirms overall trend direction, with trade direction determined by price position relative to EMA
- Entry signals are based on G-Channel breakouts and EMA position confirmation
- Stop-loss and take-profit levels are set using ATR multiples, with 2x ATR for stop-loss and 4x ATR for take-profit
- State tracking prevents consecutive duplicate signals
Strategy Advantages
- Multi-level signal confirmation mechanism improves trading reliability
- Dynamically adjusted channel boundaries adapt to different market conditions
- Volatility-based risk management provides better adaptability
- Avoiding duplicate signals reduces overtrading risk
- Clear visual buy/sell markers facilitate analysis and backtesting
Strategy Risks
- May generate excessive false breakout signals in ranging markets
- EMA as a lagging indicator can lead to delayed entry timing
- Fixed ATR multipliers for stops may lack flexibility during high volatility periods
- Requires longer historical data for indicator calculations
- Parameter optimization may lead to overfitting
Strategy Optimization Directions
- Incorporate volume confirmation for improved breakout reliability
- Implement dynamic ATR multipliers to adapt to different market volatility states
- Add market environment filters to avoid trading during unfavorable conditions
- Optimize signal filtering logic to further reduce false signals
- Consider adding a dynamic position sizing system
Summary
The strategy builds a complete trading system by combining multiple mature technical indicators. Its strength lies in the multi-level signal confirmation mechanism and volatility-based risk management, though it still requires optimization based on specific market characteristics in practical applications. Through the suggested optimization directions, the strategy's stability and adaptability can be further enhanced.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-10 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("G-Channel with EMA Strategy and ATR SL/TP", shorttitle="G-EMA-ATR", overlay=true)

// Input parameters
length = input.int(100, title="G-Channel Length")
src = input.source(close, title="Source")
ema_length = input.int(50, title="EMA Length")  // EMA length
atr_length = input.int(14, title="ATR Length")  // ATR length

// G-Channel calculation
var float a = na
var float b = na
a := math.max(src, nz(a[1])) - nz(a[1] - b[1]) / length
b := math.min(src, nz(b[1])) + nz(a[1] - b[1]) / length
avg = (a + b) / 2

// G-Channel cross conditions
crossup = b[1] < close[1] and b > close
crossdn = a[1] < close[1] and a > close
bullish = ta.barssince(crossdn) <= ta.barssince(crossup)
c = bullish ? color.lime : color.red

// EMA calculation
ema_value = ta.ema(src, ema_length)

// ATR calculation
atr_value = ta.atr(atr_length)

// Plot G-Channel average and Close price
p1 = plot(avg, "G-Channel Average", color=c, linewidth=1, transp=90)
p2 = plot(close, "Close Price", color=c, linewidth=1, transp=100)
fill(p1, p2, color=c, transp=90)

// Plot EMA
plot(ema_value, color=color.blue, linewidth=2, title="EMA")

// Buy and Sell conditions
buy_condition = bullish and close < ema_value
sell_condition = not bullish and close > ema_value

// Track the last signal state
var bool last_was_buy = false
var bool last_was_sell = false

// ATR-based SL and TP calculations
long_sl = close - 2 * atr_value  // 2 ATR below the entry for SL
long_tp = close + 4 * atr_value  // 4 ATR above the entry for TP
short_sl = close + 2 * atr_value // 2 ATR above the entry for SL (short)
short_tp = close - 4 * atr_value // 4 ATR below the entry for TP (short)

// Generate Buy signal only if the last signal was not Buy
if (buy_condition and not last_was_buy)
    strategy.entry("Buy", strategy.long)
    strategy.exit("Exit Buy", from_entry="Buy", stop=long_sl, limit=long_tp)
    last_was_buy := true
    last_was_sell := false

// Generate Sell signal only if the last signal was not Sell
if (sell_condition and not last_was_sell)
    strategy.entry("Sell", strategy.short)
    strategy.exit("Exit Sell", from_entry="Sell", stop=short_sl, limit=short_tp)
    last_was_sell := true
    last_was_buy := false

// Plot shapes for Buy and Sell signals
plotshape(series=buy_condition and not last_was_buy, location=location.belowbar, style=shape.labelup, color=color.lime, size=size.small, text="Buy", textcolor=color.white)
plotshape(series=sell_condition and not last_was_sell, location=location.abovebar, style=shape.labeldown, color=color.red, size=size.small, text="Sell", textcolor=color.white)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Indicator-Trend-Following-Strategy-with-Dynamic-Channel-and-Moving-Average-Trading-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Adaptive Trend Following Strategy Combining Dual Moving Average Crossover and RSIPine Script · Trend following · 2d
- Advanced Multi Indicator Trend Confirmation Trading StrategyPine Script · Trend following · 1d
- MACD EMA Multi Period Dynamic Crossover Quantitative Trading SystemPine Script · Trend following · 1h
- Multi Indicator Trend Following Strategy with ATR Dynamic Stop Loss Take ProfitPine Script · Trend following · 1d