Strategy vault / Mean reversion
Multi level Indicator Overlapping RSI Trading Strategy
This strategy is a multi-level indicator overlapping trading system based on the Relative Strength Index (RSI). Operating within a specific trading window, it identifies trading opportunities through RSI's overbought…
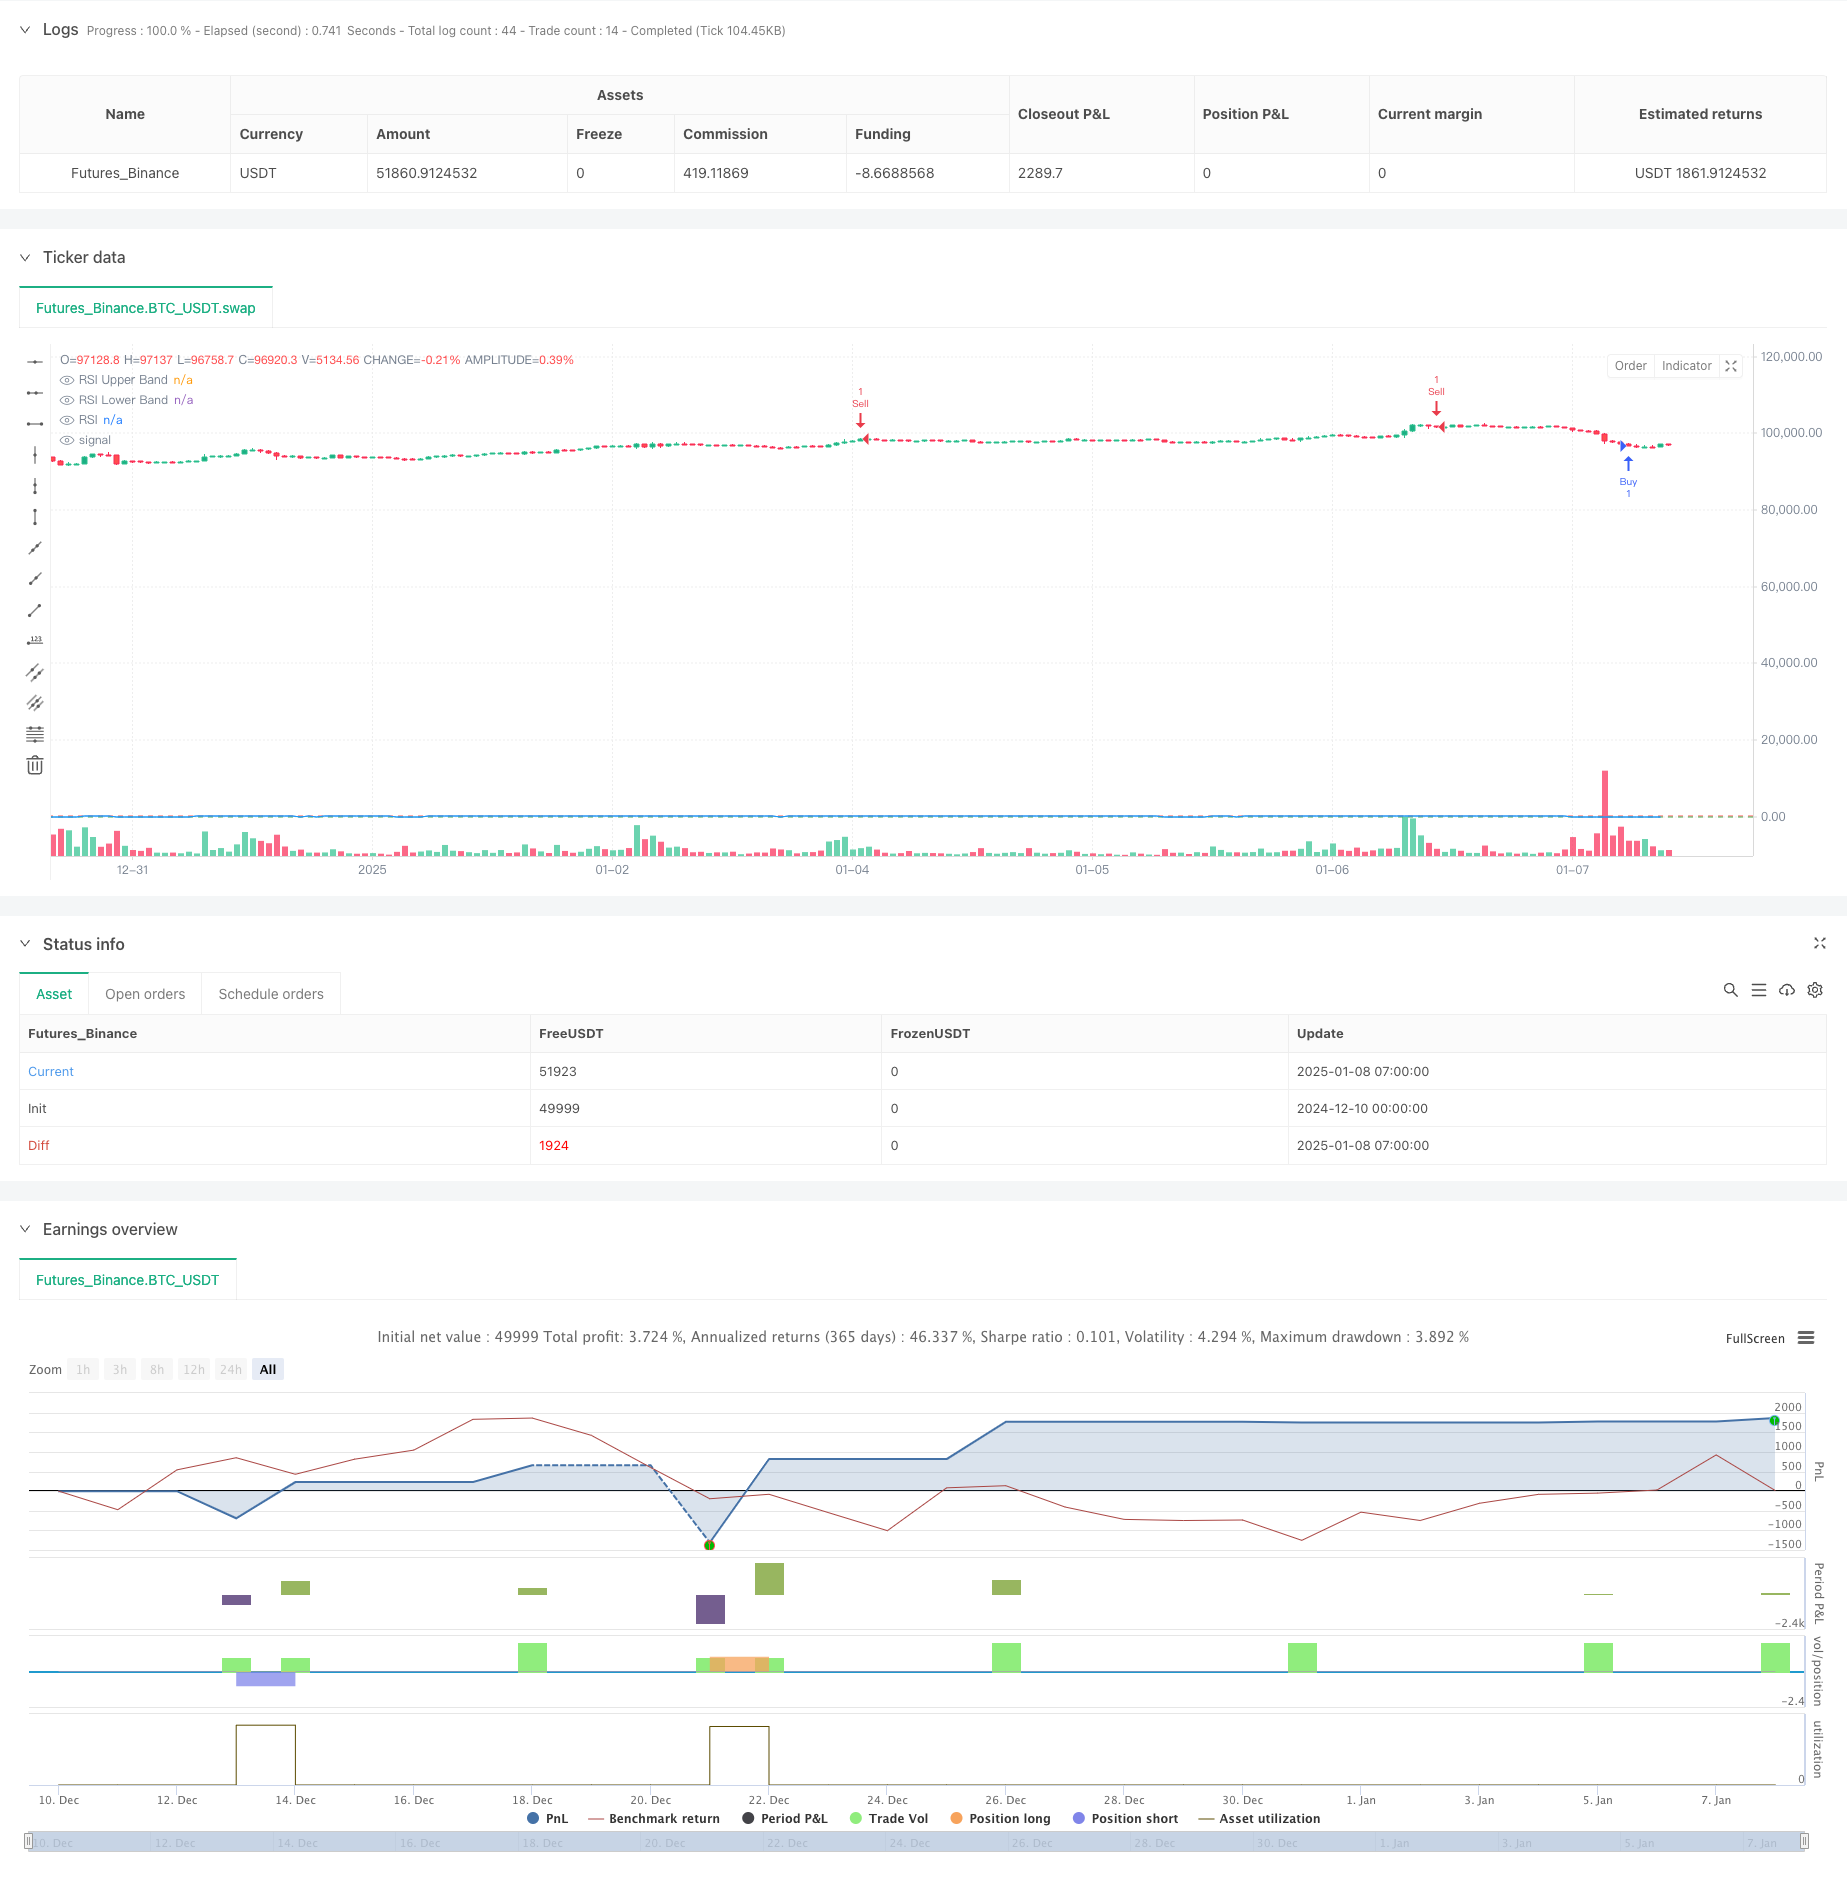
Overview
This strategy is a multi-level indicator overlapping trading system based on the Relative Strength Index (RSI). Operating within a specific trading window, it identifies trading opportunities through RSI's overbought and oversold signals, combined with a dynamic position adjustment mechanism that employs a scaled entry approach during adverse market movements. The strategy implements profit-taking based on average entry price targets.
Strategy Principle
The strategy operates based on the following core components:
- RSI calculation uses standard 14 periods with closing price as source data
- Trading window is controlled between 2-4 hours, adjustable based on market characteristics
- Entry signals based on RSI below 30 (oversold) and above 70 (overbought) levels
- Position building includes initial position and dynamic adjustment levels
- Scaling mechanism triggers when price moves adversely by 1 point
- Take profit is set at 1.5 points from average entry price
Strategy Advantages
- Multi-level signal filtering: Combines RSI technical indicator and time window dual filtering to effectively reduce false signals
- Dynamic position management: Reduces average cost during adverse market movements through scaled entry mechanism
- Reasonable risk-reward ratio: Take profit levels based on average entry price ensure overall trade expectancy
- Clear strategy logic: Well-defined module responsibilities facilitate subsequent optimization and adjustment
- High adaptability: Key parameters can be optimized for different market characteristics
Strategy Risks
- Trend market risk: May face excessive capital usage due to frequent scaling in strong trend markets
- Time window limitation: Specific time window restrictions might miss good opportunities in other periods
- Parameter sensitivity: Settings for RSI period, entry spacing significantly impact strategy performance
- Capital management risk: Requires reasonable control of single entry proportion to avoid over-concentration
Strategy Optimization Directions
- Introduce trend filter: Suggest adding moving averages or other trend indicators to optimize entry timing
- Dynamic parameter optimization: RSI thresholds and entry spacing can be dynamically adjusted based on market volatility
- Improve stop loss mechanism: Recommend adding trailing stop loss functionality to better protect existing profits
- Optimize time window: Better trading periods can be identified through backtesting data analysis
- Add volume indicators: Incorporate volume analysis to improve signal reliability
Summary
The strategy forms a relatively complete trading system through the combination of RSI indicators and scaled entry mechanisms. Its core advantages lie in its multi-level signal filtering mechanism and flexible position management approach, while attention needs to be paid to trend market risks and parameter optimization issues. The overall performance of the strategy can be further improved through enhancements such as adding trend filters and optimizing stop loss mechanisms.
Source Pine Script
/*backtest
start: 2024-12-10 00:00:00
end: 2025-01-08 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
*/

//@version=6
strategy("TonyM RSI", overlay=true)

// Input Settings
rsiLengthInput = input.int(14, minval=1, title="RSI Length", group="RSI Settings")
rsiSourceInput = input.source(close, "Source", group="RSI Settings")
startHour = input.int(2, "Start Hour", minval=0, maxval=23, group="Trading Window")
endHour = input.int(4, "End Hour", minval=0, maxval=23, group="Trading Window")

// RSI Calculation
change = ta.change(rsiSourceInput)
up = ta.rma(math.max(change, 0), rsiLengthInput)
down = ta.rma(-math.min(change, 0), rsiLengthInput)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))

// Time Filter
inTradingWindow = (hour >= startHour and hour < endHour)

// Strategy Settings
buyLevel = 30
sellLevel = 70
scaleDistance = 1.0  // Distance in points to add to the position
takeProfitPoints = 1.5  // Profit target from average price
initialQty = 1  // Initial trade size
scalingQty = 1  // Additional trade size for scaling

// Trade Logic
if inTradingWindow
    // Entry Logic
    if rsi <= buyLevel and strategy.position_size == 0
        strategy.entry("Buy", strategy.long, qty=initialQty)
    if rsi >= sellLevel and strategy.position_size == 0
        strategy.entry("Sell", strategy.short, qty=initialQty)

    // Scaling Logic
    if strategy.position_size > 0 and close <= strategy.position_avg_price - scaleDistance
        strategy.entry("Scale Buy", strategy.long, qty=scalingQty)
    if strategy.position_size < 0 and close >= strategy.position_avg_price + scaleDistance
        strategy.entry("Scale Sell", strategy.short, qty=scalingQty)

    // Exit Logic (based on average price)
    if strategy.position_size > 0
        strategy.exit("Take Profit Long", "Buy", limit=strategy.position_avg_price + takeProfitPoints)
    if strategy.position_size < 0
        strategy.exit("Take Profit Short", "Sell", limit=strategy.position_avg_price - takeProfitPoints)

// Plot RSI
plot(rsi, "RSI", color=color.blue, linewidth=1)
rsiUpperBand = hline(70, "RSI Upper Band", color=color.red)
rsiLowerBand = hline(30, "RSI Lower Band", color=color.green)
fill(rsiUpperBand, rsiLowerBand, color=color.new(color.gray, 90))
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-level-Indicator-Overlapping-RSI-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive RSI Oscillator Dynamic Trading Strategy with Threshold OptimizationPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Fibonacci Retracement Trend Following and Reversal Trading StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d