Multi Period Dynamic Moving Average Strategy
This strategy dynamically selects different types of moving averages across multiple timeframes to generate trading signals. The strategy allows selecting from SMA, EMA, TEMA, WMA and HMA moving averages, with…
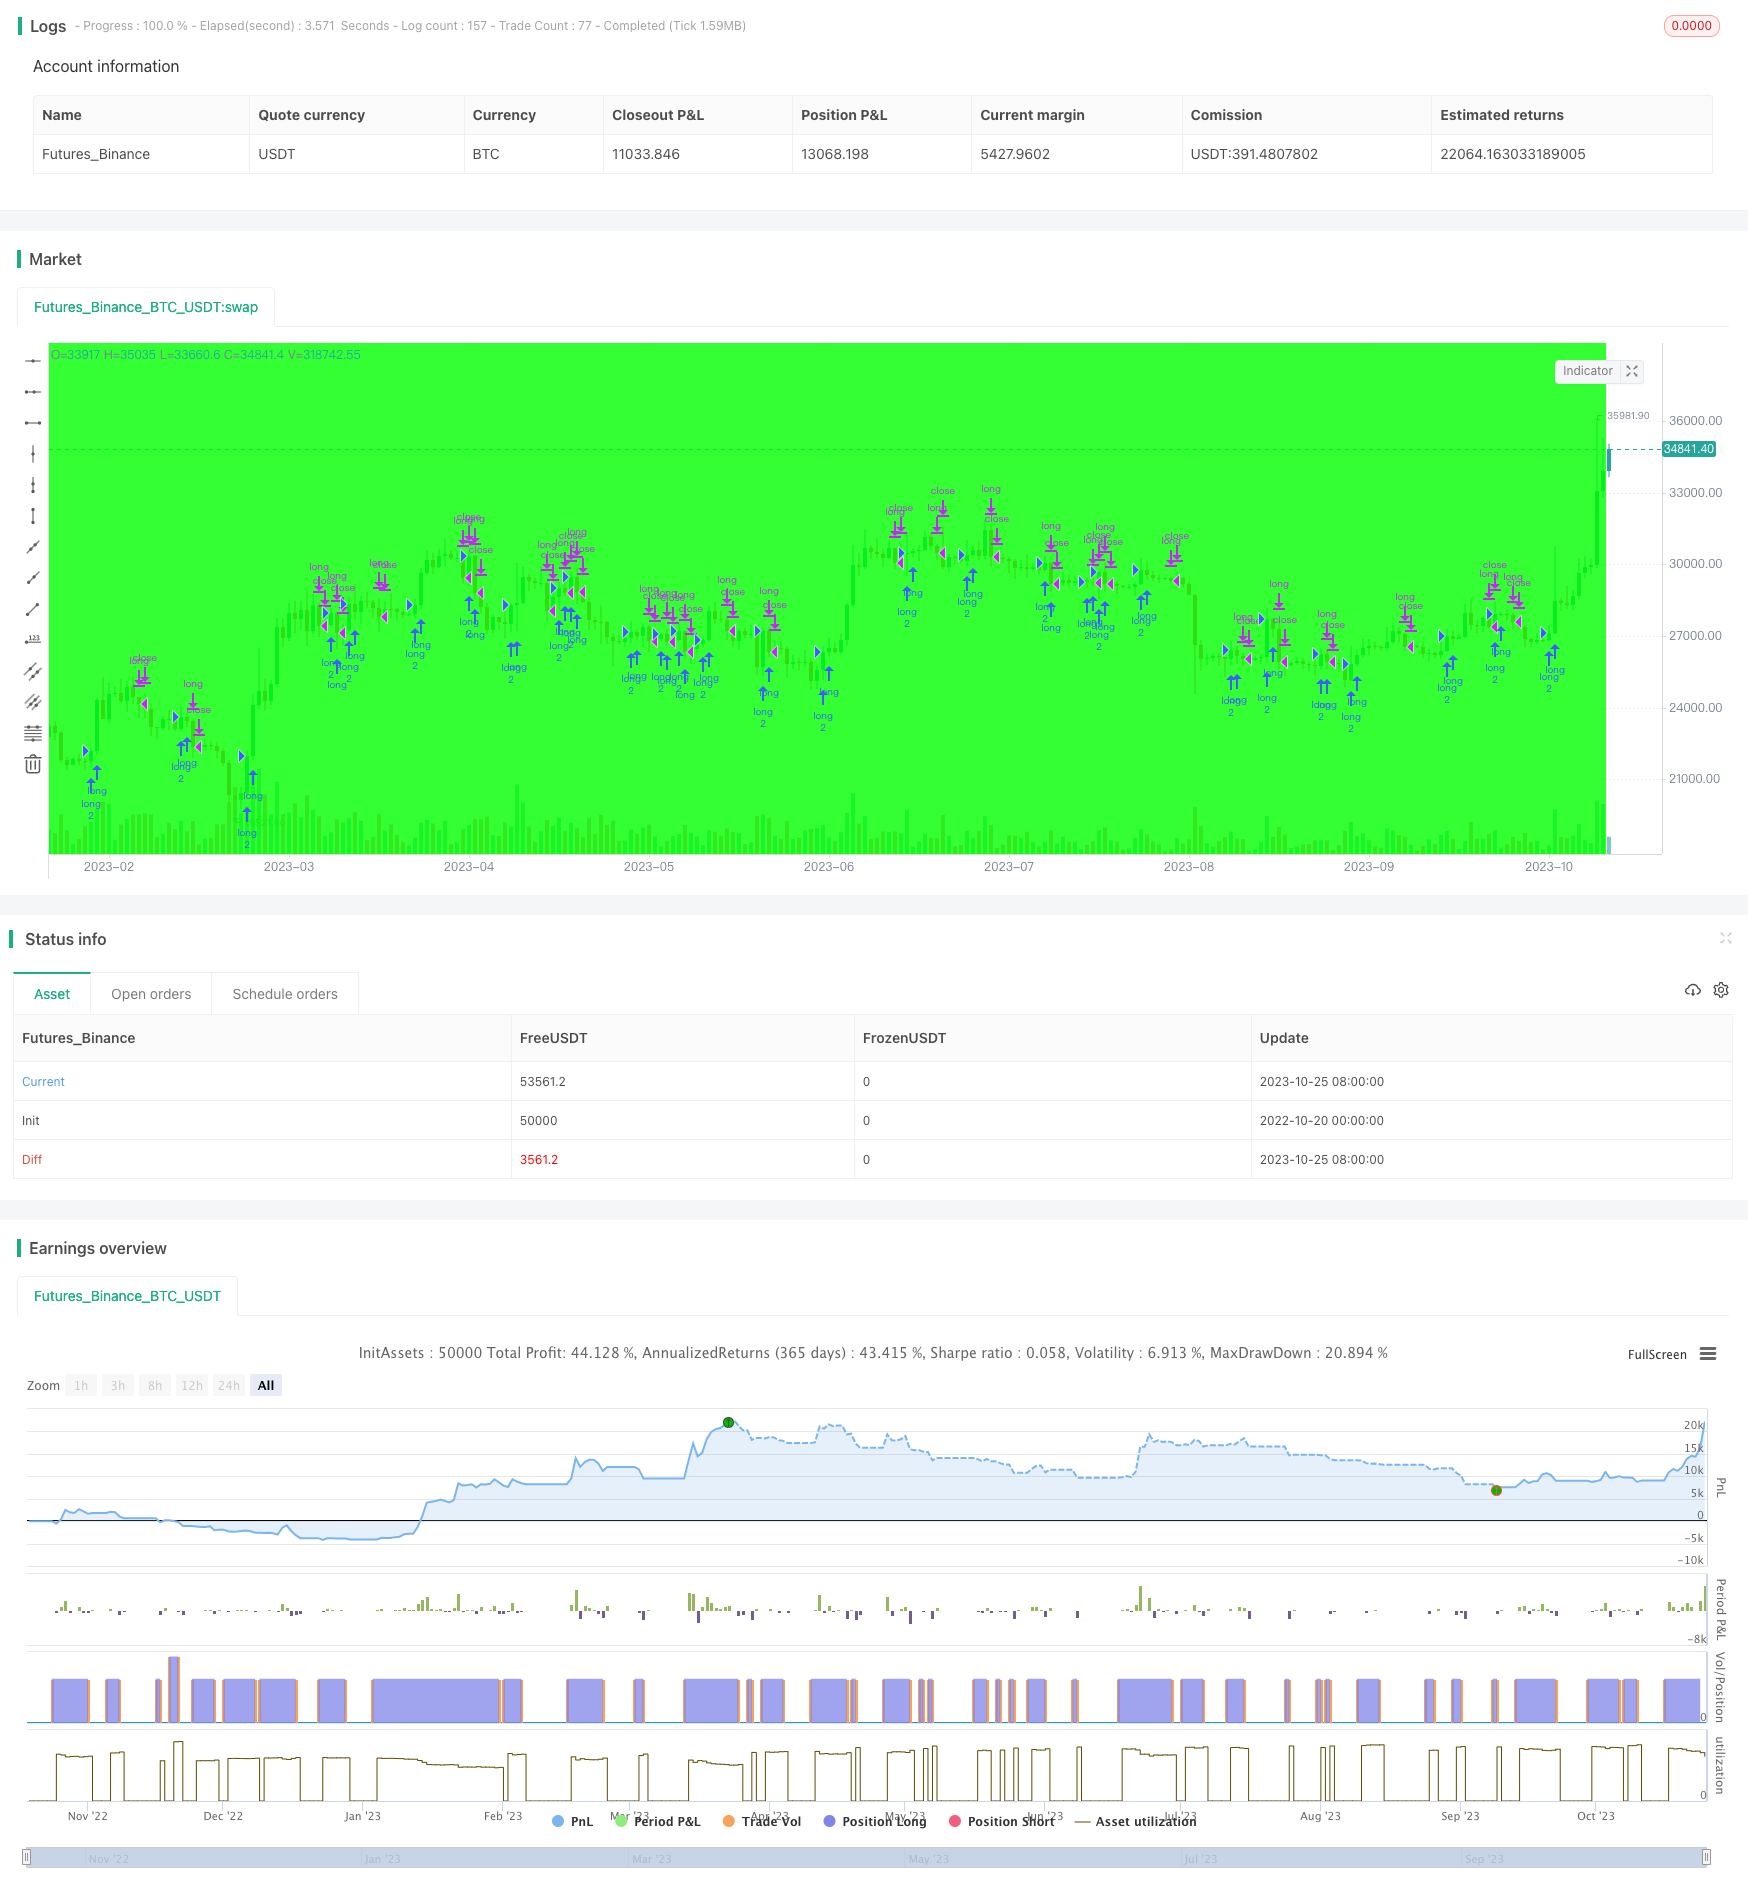
This strategy dynamically selects different types of moving averages across multiple timeframes to generate trading signals.
Strategy Logic
The strategy allows selecting from SMA, EMA, TEMA, WMA and HMA moving averages, with customizable period lengths. Different types of moving averages will be plotted dynamically based on selection. It goes long when the closing price breaks above the moving average, and goes short when the closing price breaks below.
Specifically, the strategy first defines the backtest period based on input parameters. It then calculates five types of moving averages:
- SMA Simple Moving Average
- EMA Exponential Moving Average
- TEMA Triple Exponential Moving Average
- WMA Weighted Moving Average
- HMA Hull Moving Average
The corresponding moving average is plotted based on selection. It goes long when the closing price is above the moving average, and goes short when below.
By combining different types of moving averages, the strategy can smooth price data and filter out market noise to generate more reliable trading signals. Customizable period lengths allow trading different trends across timeframes.
Advantages
- Combines multiple moving averages for greater reliability
- Customizable periods suit different trading timeframes
- Dynamic switching of averages allows flexible optimization
- Simple and intuitive trend following suitable for beginners
Risks
- Lagging of moving averages may miss trend turning points
- Overfitting with fixed parameters, underperformance in live trading likely
- Aggressive long/short signals impact capital usage efficiency
Risks can be reduced by:
- Adding other indicators to determine entries more precisely
- Real-trade optimization of parameters for different market regimes
- Optimizing position sizing based on account size and risk management
Enhancement Opportunities
The strategy can be improved in several aspects:
Add other filters for more stable signals
e.g. volume indicators to avoid false breakouts without volume confirmation.
Optimize entry and exit logic
Set price channels and stop losses to reduce unnecessary losses.
Dynamic moving average periods
Use longer periods in strong trends and shorter periods during consolidations.
Improve money management
Adjust position sizes based on drawdowns and profit taking.
Conclusion
The strategy combines various moving averages across timeframes to generate relatively stable trend following effects. With ample room for optimizations in entries, exits, parameters and money management, it can be improved for better real-world performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 100000000 | Buy quantity |
| v_input_2 | 2017 | Backtest Start Year |
| v_input_3 | true | Backtest Start Month |
| v_input_4 | true | Backtest Start Day |
| v_input_5 | false | Backtest Start Hour |
| v_input_6 | false | Backtest Start Minute |
| v_input_7 | 2099 | Backtest Stop Year |
| v_input_8 | true | Backtest Stop Month |
| v_input_9 | 30 | Backtest Stop Day |
| v_input_10 | true | Color Background? |
| v_input_11 | 0 | Select MA: SMA | EMA | TEMA | WMA | HMA |
| v_input_12 | 7 | Period |
Source Pine Script
/*backtest
start: 2022-10-20 00:00:00
end: 2023-10-26 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("MA_strategy ", shorttitle="MA_strategy", overlay=true, initial_capital=100000)

qty = input(100000000, "Buy quantity")

testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testStartHour = input(0, "Backtest Start Hour")
testStartMin = input(0, "Backtest Start Minute")

testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,testStartHour,testStartMin)

testStopYear = input(2099, "Backtest Stop Year")
testStopMonth = input(1, "Backtest Stop Month")
testStopDay = input(30, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)


testPeriodBackground = input(title="Color Background?", type=bool, defval=true)
testPeriodBackgroundColor = testPeriodBackground and (time >= testPeriodStart) and (time <= testPeriodStop) ? #00FF00 : na
bgcolor(testPeriodBackgroundColor, transp=97)

testPeriod() =>
    time >= testPeriodStart and time <= testPeriodStop ? true : false


ma1 = input( "SMA",title="Select MA", options=["SMA", "EMA","TEMA", "WMA","HMA"])


len1 = input(7, minval=1, title="Period")

s=sma(close,len1)

e=ema(close,len1)


xEMA1 = ema(close, len1)
xEMA2 = ema(xEMA1, len1)
xEMA3 = ema(xEMA2, len1)
t = 3 * xEMA1 - 3 * xEMA2 + xEMA3


f_hma(_src, _length)=>
    _return = wma((2 * wma(_src, _length / 2)) - wma(_src, _length), round(sqrt(_length)))

h = f_hma(close, len1)

w = wma(close, len1)

ma = ma1 == "SMA"?s:ma1=="EMA"?e:ma1=="WMA"?w:ma1=="HMA"?h:ma1=="TEMA"?t:na

buy= close>ma
sell= close<ma

alertcondition(buy, title='buy', message='buy')
alertcondition(sell, title='sell', message='sell')

ordersize=floor(strategy.equity/close)

if testPeriod()
    strategy.entry("long",strategy.long,ordersize,when=buy)
    strategy.close("long", when = sell )
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Period-Dynamic-Moving-Average-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Multi Indicator Trend Breakout Strategy with Dynamic Stop LossPine Script · Breakout · 1d