Strategy vault / Trend following
Multi Period EMA Crossover Quantitative Trading Strategy
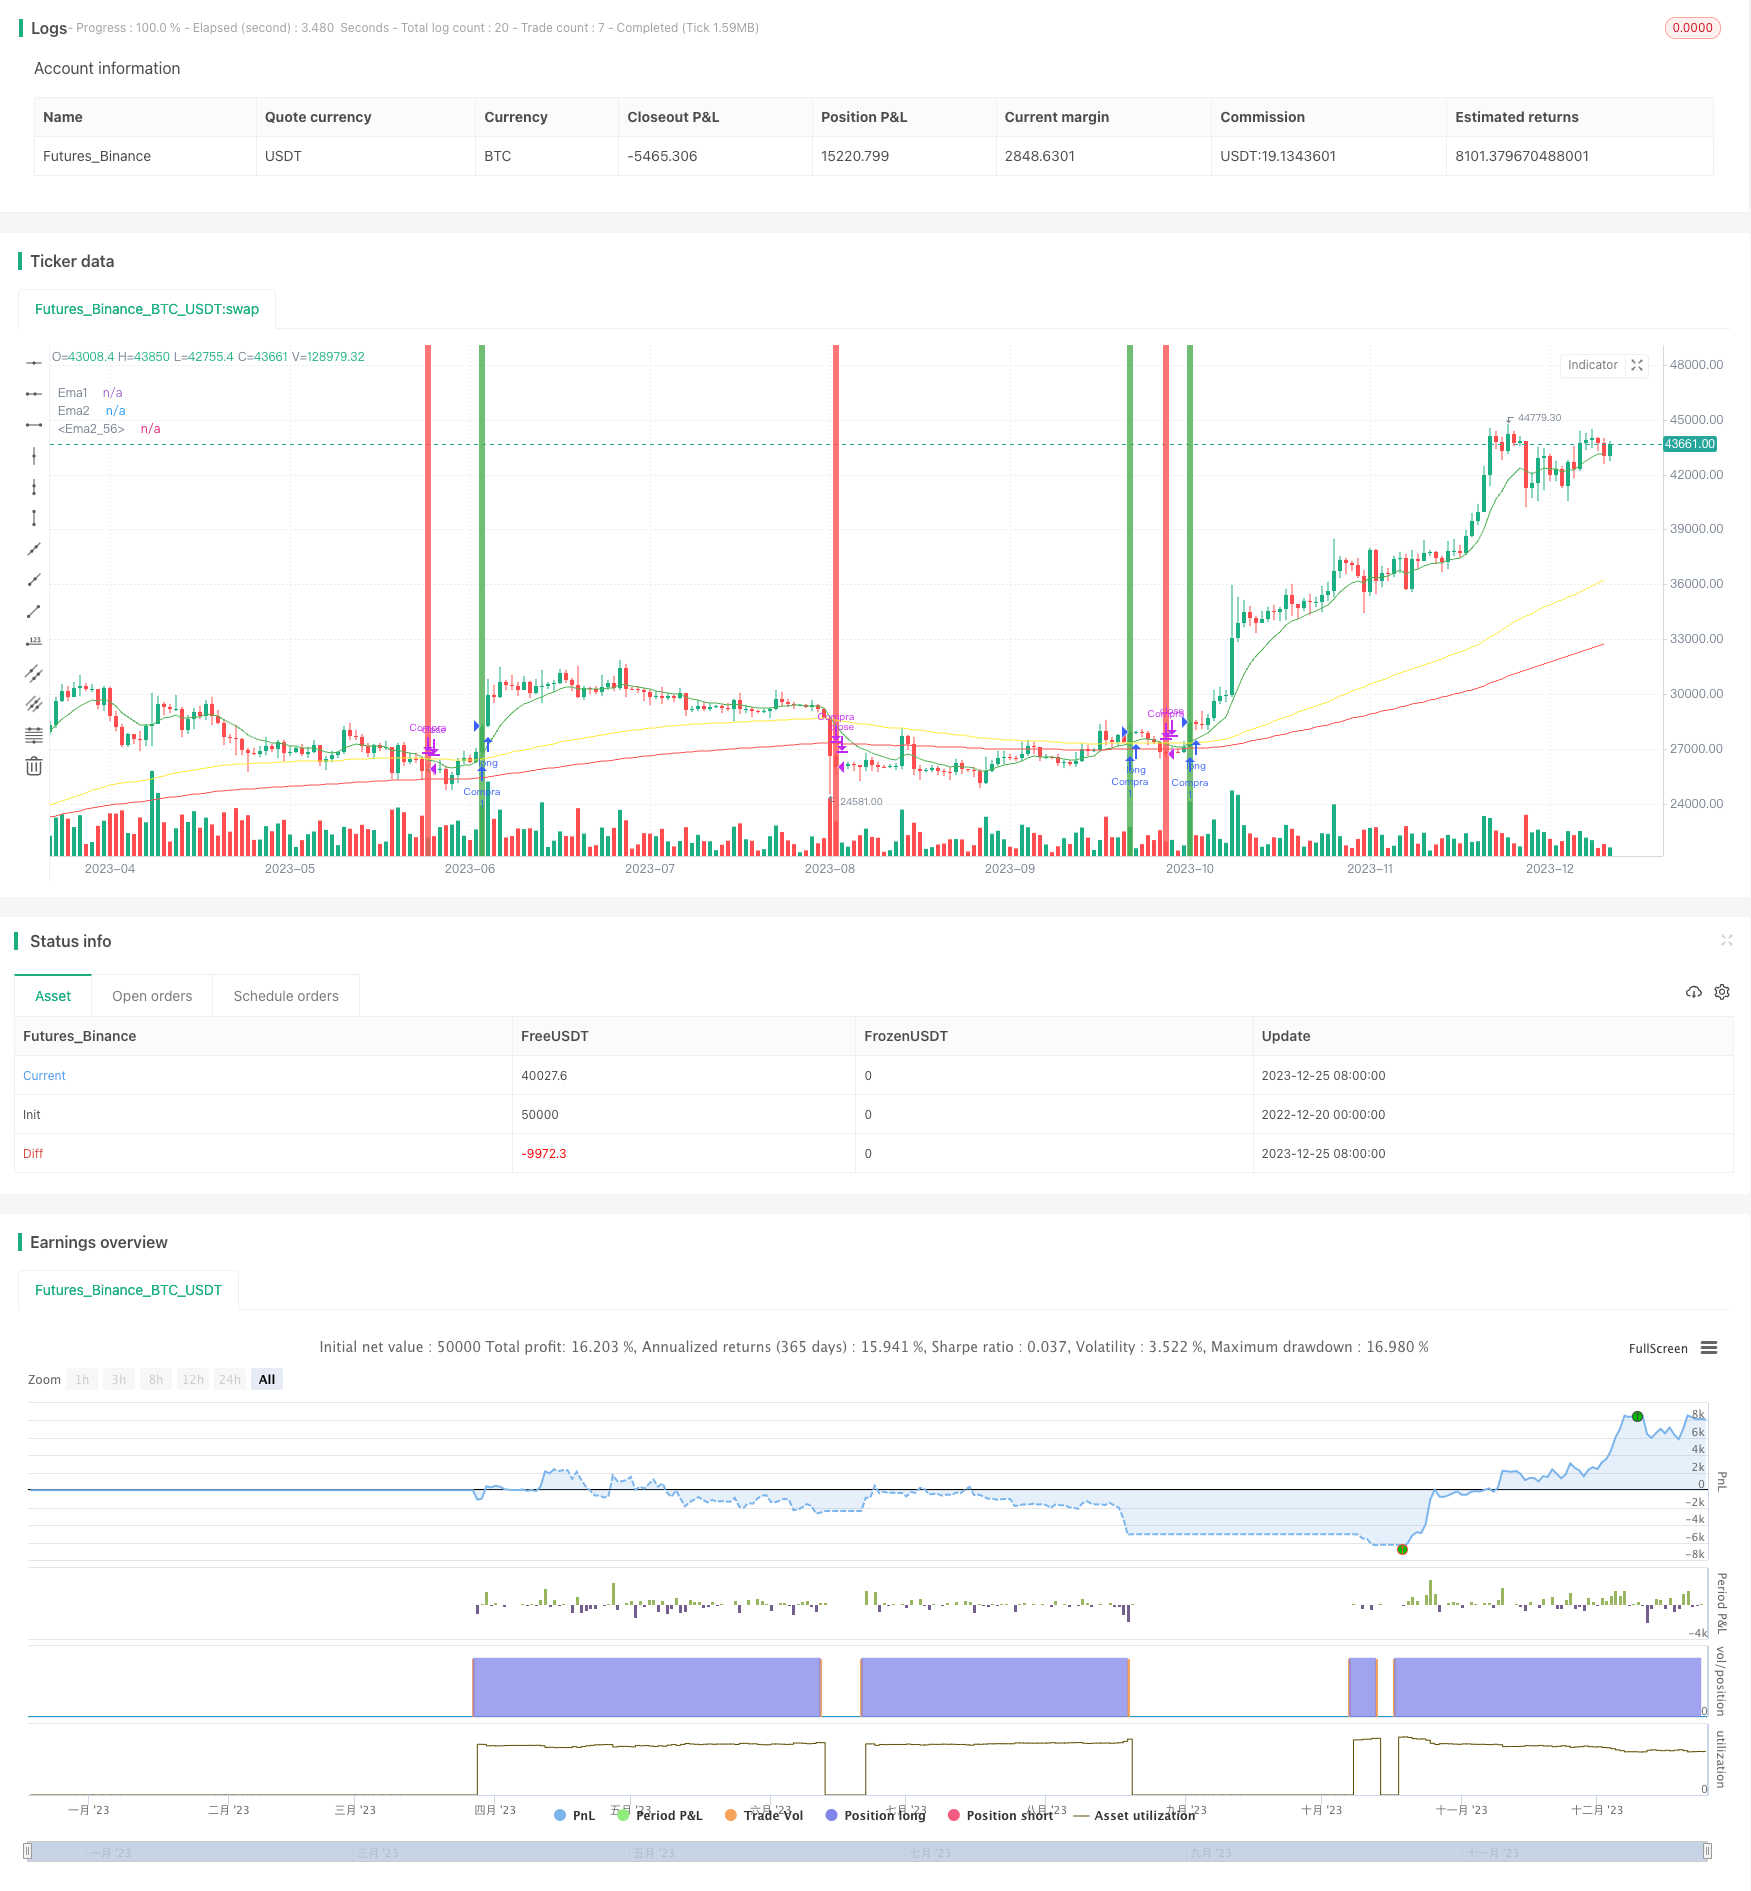
This article introduces a quantitative trading strategy based on the crossover points of Exponential Moving Averages (EMA) over three different periods. The strategy aims to utilize EMA crossovers to identify…
Overview
This article introduces a quantitative trading strategy based on the crossover points of Exponential Moving Averages (EMA) over three different periods. The strategy aims to utilize EMA crossovers to identify long-term and short-term trends in the stock market for effective trading decisions.
Strategy Principle
The strategy employs EMAs of three different periods: 10-day, 100-day, and 200-day. Buy or sell signals are generated based on the direction of the crossover when the short-period EMA (10-day) crosses the longer-period EMAs (100-day or 200-day). The strategy also incorporates a time filter to ensure trades are executed only within specific time frames. This combination adds flexibility and adaptability to the strategy.
Advantages Analysis
The strength of this strategy lies in its simplicity and high adaptability. Multi-period EMAs provide a multi-dimensional view of market trends, increasing the accuracy of trading decisions. Additionally, the time filter avoids instability during specific market periods, reducing potential risks.
Risk Analysis
Despite its effectiveness, the strategy carries certain risks. The primary risk is market volatility due to unforeseen events, which may lead to strategy failure. Additionally, EMAs can be lagging, delaying the reflection of market changes. Methods to mitigate these risks include real-time market monitoring and combining other technical indicators to enhance decision accuracy.
Optimization Direction
Optimization directions for the strategy include the integrated use of various technical indicators, such as the Relative Strength Index (RSI) and Bollinger Bands, to deepen and broaden market analysis. Additionally, adjusting the periods of EMAs to better suit different market conditions could be beneficial.
Conclusion
Overall, this
multi-period EMA crossover quantitative trading strategy is an effective tool that can help traders make better decisions in a volatile market. With continuous optimization and adaptation to market changes, this strategy has the potential to achieve higher returns in future trading endeavors.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Periodo_1 |
| v_input_2 | 100 | Periodo_2 |
| v_input_3 | 200 | Periodo_3 |
| v_input_4 | 2000 | Desde año |
| v_input_int_1 | true | Desde mes |
| v_input_int_2 | true | Desde dia |
| v_input_5 | 2030 | Hasta año |
| v_input_int_3 | true | Hasta mes |
| v_input_int_4 | true | Hasta dia |
Source Pine Script
/*backtest
start: 2022-12-20 00:00:00
end: 2023-12-26 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
start = timestamp(2023,1,1,0,0)
end = timestamp(2024,1,1,0,0)
strategy("Tester Emas", overlay = true)

periodo1 = input(10,"Periodo_1")
periodo2 = input(100,"Periodo_2")
periodo3 = input(200,"Periodo_3")

//definir media moviles
ema1 = ta.ema(close,periodo1)
ema2 = ta.ema(close,periodo2)
ema3 = ta.ema(close,periodo3)

//Desde
desde_a = input(2000, title = "Desde año")
desde_m = input.int(   1, title = "Desde mes", minval=1, maxval = 12)
desde_d = input.int(   1, title = "Desde dia", minval=1, maxval = 31)

//Hasta
hasta_a = input(2030, title = "Hasta año")
hasta_m = input.int(   1, title = "Hasta mes", minval=1, maxval = 12)
hasta_d = input.int(   1, title = "Hasta dia", minval=1, maxval = 31)

FechaValida() => true

//Condicion de entradas
longCondition = ta.crossover(ema1, ema2)
shortCondition = ta.crossunder(ema1,ema2)

alcista = (ema1 > ema2) and (ema2 > ema3)
comprado =strategy.position_size > 0


//Comprar o vender segun las condiciones de entradas

//if (longCondition)
if (not comprado and alcista and FechaValida())
    // Round redondea mi capital para comprar las acciones en cantidades enteras
    cantidad = math.round(strategy.equity/ close)
    strategy.entry("Compra", strategy.long, cantidad)
//if (shortCondition)
if (comprado and not alcista and FechaValida())
    //strategy.entry("Venta", strategy.short)
    strategy.close("Compra" , comment = "Venta")

if (comprado and not FechaValida())
    //Cierre x finalizacion de periodo
    //strategy.entry("Venta", strategy.short)
    strategy.close("Compra" , comment = "Venta x fin")

//Graficar las medias moviles
plot(ema1, color = color.green, title = "Ema1")
plot(ema2, color = color.yellow, title = "Ema2")
plot(ema3, color = color.red, title = "Ema2")
//GMarca los cruces de medias
bgcolor(longCondition ? color.green : na)
bgcolor(shortCondition ? color.red : na)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Period-EMA-Crossover-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Incremental Order Size Fibonacci Retracement Trend Following StrategyPine Script · Trend following · 1d
- Multi Indicator Trend Divergence Quantitative Trading StrategyPine Script · Trend following · 1d
- Multi Indicator Trend Following Strategy with Dynamic Risk ManagementPine Script · Trend following · 2h