Multi Technical Indicator Trend Following Strategy with Ichimoku Cloud Breakout and Stop Loss System
This strategy is a comprehensive trading system that combines multiple technical indicators, primarily based on the Ichimoku Cloud indicator for trading decisions. The system determines entry points through the…
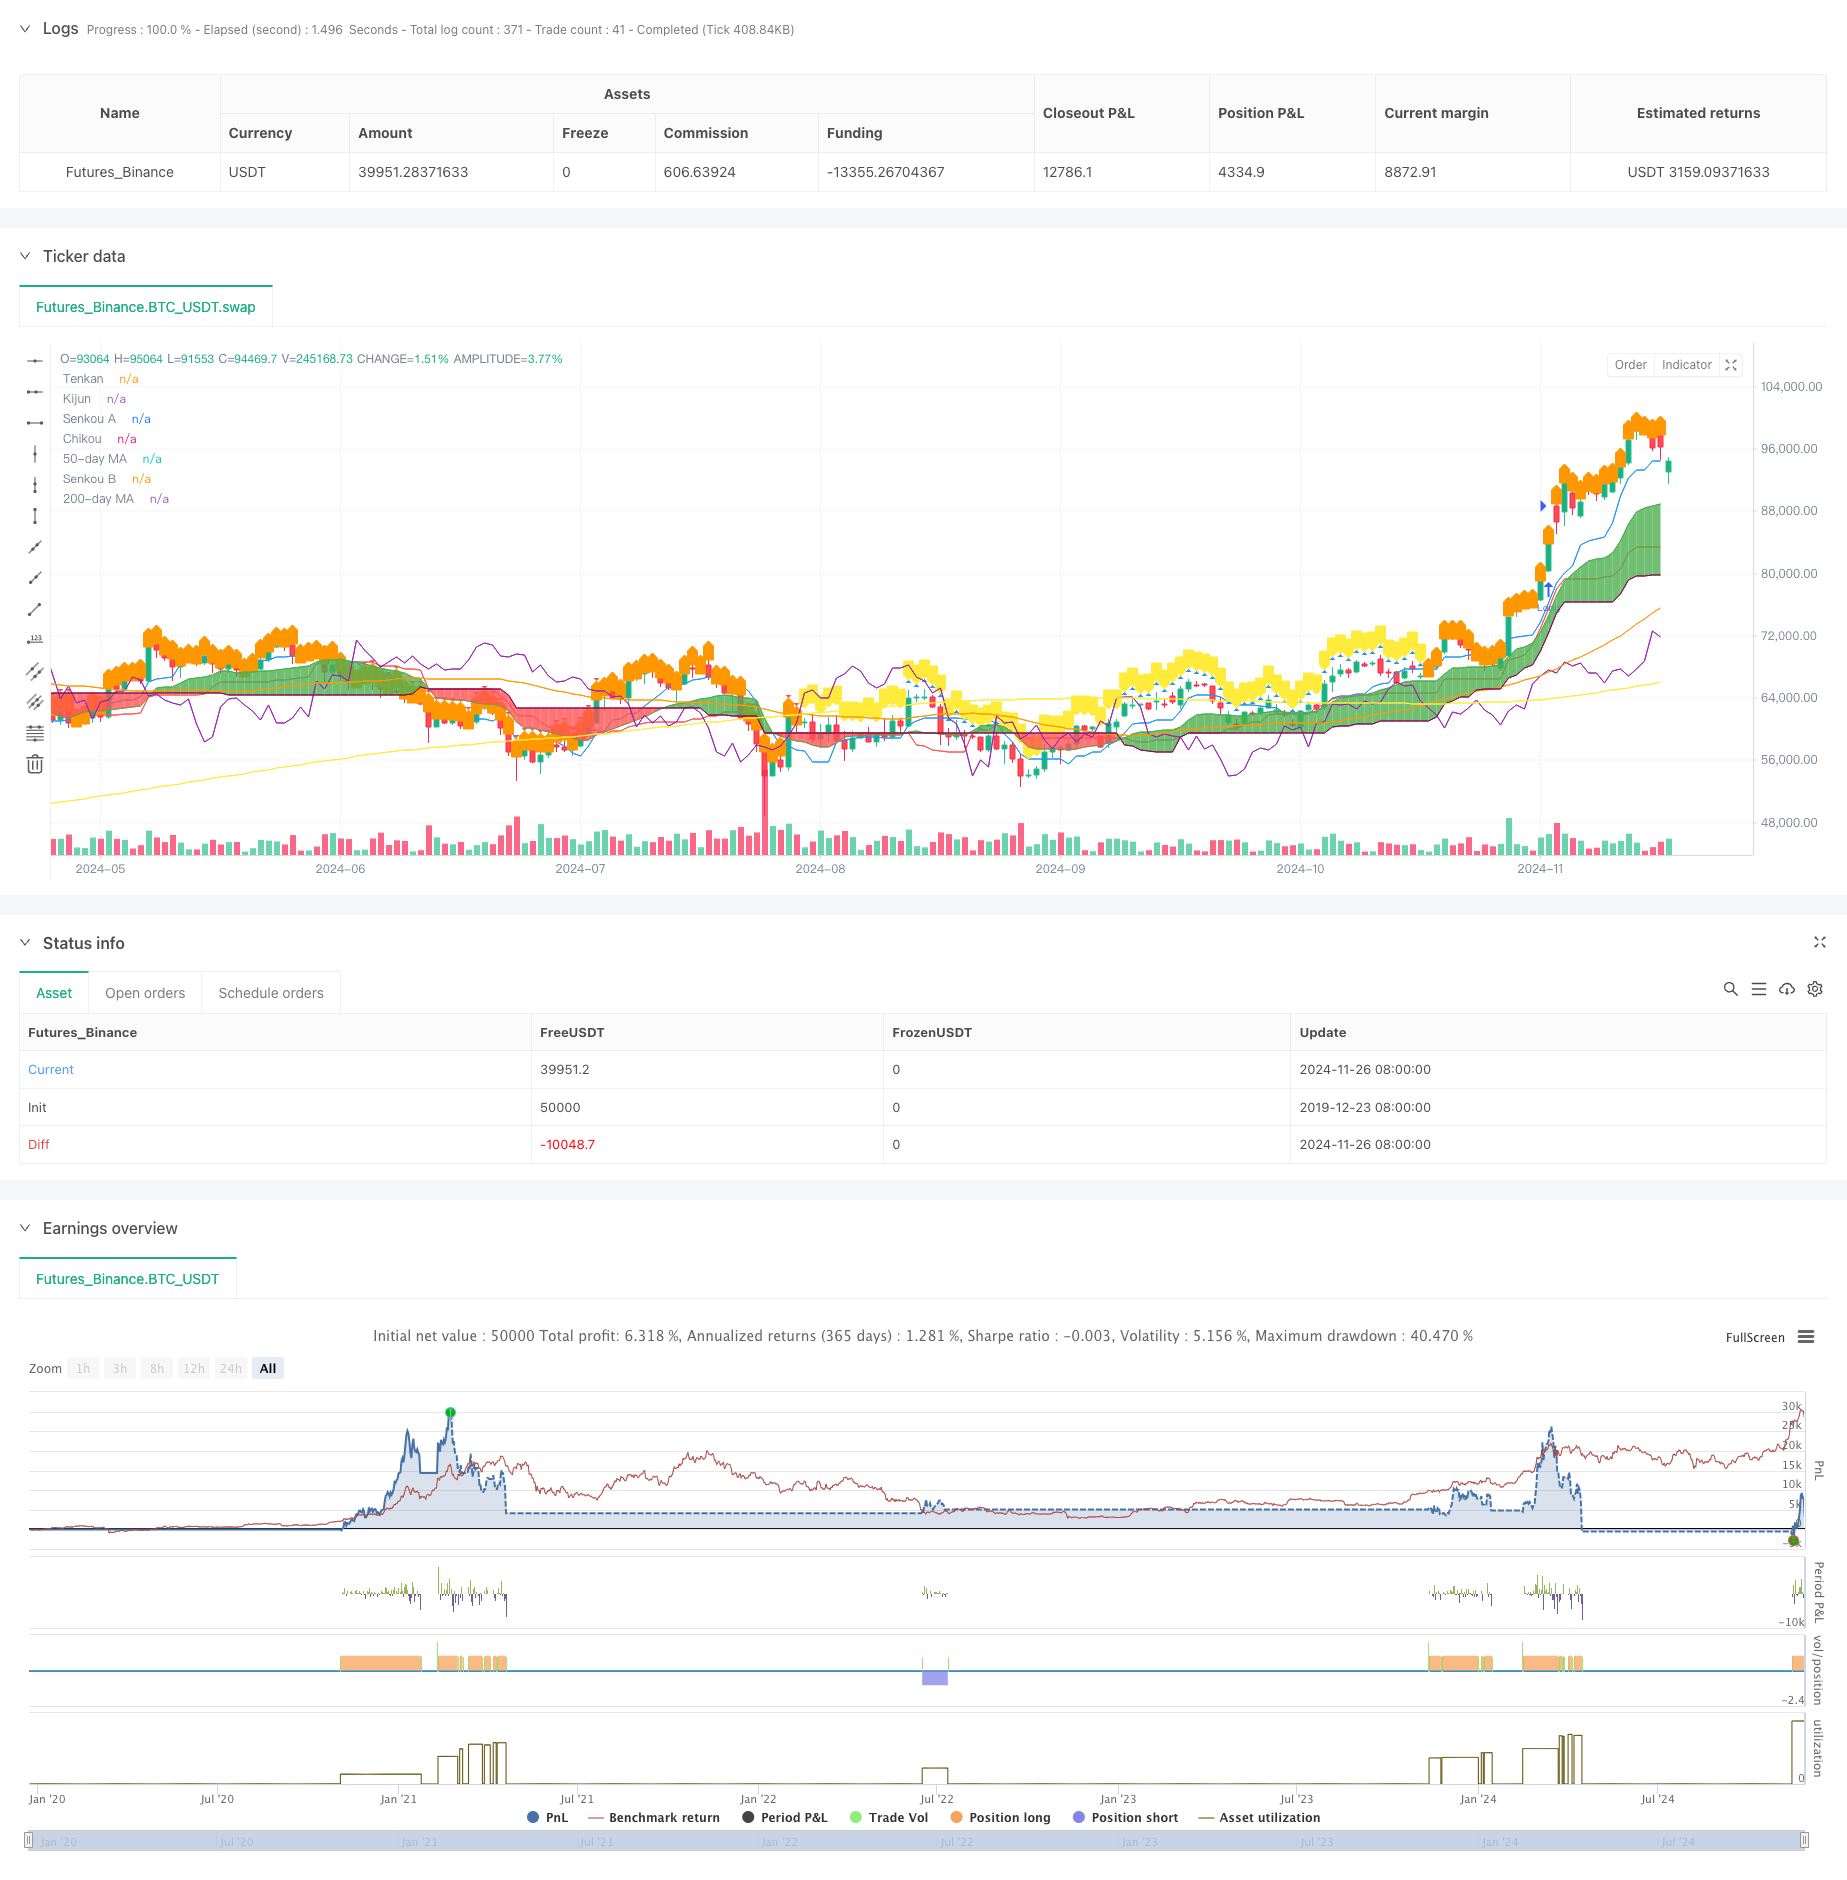
Overview
This strategy is a comprehensive trading system that combines multiple technical indicators, primarily based on the Ichimoku Cloud indicator for trading decisions. The system determines entry points through the crossing of Tenkan and Kijun lines, while incorporating RSI and Moving Averages as auxiliary filtering conditions. The strategy uses cloud components as dynamic stop-loss levels, forming a complete risk control system.
Strategy Principles
The core logic of the strategy is based on the following key elements:
- Entry signals are generated by Tenkan-Kijun crossovers, with upward crosses forming long signals and downward crosses forming short signals
- Price position relative to the Kumo (cloud) serves as trend confirmation, going long above the cloud and short below it
- The relationship between 50-day and 200-day moving averages acts as a trend filter
- Weekly RSI indicator confirms market strength, filtering out false signals
- Cloud boundaries are used as dynamic stop-loss positions for dynamic risk management
Strategy Advantages
- The combination of multiple technical indicators provides more reliable trading signals, significantly reducing the impact of false signals
- Using the cloud as a dynamic stop-loss can automatically adjust stop-loss positions based on market volatility, both protecting profits and allowing sufficient price movement
- Weekly RSI filtering effectively avoids unfavorable trades in overbought/oversold areas
- Moving average crossovers provide additional trend confirmation, improving trade success rates
- Complete risk control system covering entry, position holding, and exit phases
Strategy Risks
- Multiple indicator filtering may cause missing some potential good opportunities
- May generate frequent false breakout signals in ranging markets
- The Ichimoku Cloud indicator has inherent lag, which may affect entry timing
- Dynamic stop-loss positions may be too loose in rapidly volatile markets
- Excessive filtering conditions may reduce trading opportunities, affecting overall strategy returns
Strategy Optimization Directions
- Introduce volatility indicators to adjust strategy parameters based on market volatility
- Optimize cloud parameters to better suit different market environments
- Add volume analysis to improve signal reliability
- Implement time filtering mechanisms to avoid highly volatile periods
- Develop adaptive parameter optimization system for dynamic strategy adjustment
Summary
This strategy builds a complete trading system by combining multiple technical indicators. The strategy not only focuses on signal generation but also includes a comprehensive risk control mechanism. Through multiple filtering conditions, it effectively improves trade success rates. Meanwhile, the dynamic stop-loss design provides the strategy with a good risk-reward ratio. While there is room for optimization, it is overall a well-structured strategy system with clear logic.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-27 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Ichimoku Strategy with Optional RSI, MA Filters and Alerts", overlay=true)

// Input for date and time filter
startDate = input(timestamp("2020-01-01 00:00"), title="Start Date")
endDate = input(timestamp("2023-01-01 00:00"), title="End Date")

// Inputs for Ichimoku settings
tenkanPeriod = input.int(9, title="Tenkan Period")
kijunPeriod = input.int(26, title="Kijun Period")
senkouBPeriod = input.int(52, title="Senkou B Period")

// Inputs for Moving Average settings
useMAFilter = input.bool(true, title="Enable Moving Average Filter?")
ma50Period = input.int(50, title="50-day MA Period")
ma200Period = input.int(200, title="200-day MA Period")

// Inputs for RSI settings
useRSIFilter = input.bool(true, title="Enable RSI Filter?")
rsiPeriod = input.int(14, title="RSI Period")
rsiOverbought = input.int(70, title="RSI Overbought Level")
rsiOversold = input.int(30, title="RSI Oversold Level")

// Ichimoku Cloud components
tenkan = (ta.highest(high, tenkanPeriod) + ta.lowest(low, tenkanPeriod)) / 2
kijun = (ta.highest(high, kijunPeriod) + ta.lowest(low, kijunPeriod)) / 2
senkouA = ta.sma(tenkan + kijun, 2) / 2
senkouB = (ta.highest(high, senkouBPeriod) + ta.lowest(low, senkouBPeriod)) / 2
chikou = close[26]

// Moving Averages
ma50 = ta.sma(close, ma50Period)
ma200 = ta.sma(close, ma200Period)

// Weekly RSI
rsiSource = request.security(syminfo.tickerid, "W", ta.rsi(close, rsiPeriod))

// Plotting the Ichimoku Cloud components
pTenkan = plot(tenkan, color=color.blue, title="Tenkan")
pKijun = plot(kijun, color=color.red, title="Kijun")
pSenkouA = plot(senkouA, color=color.green, title="Senkou A")
pSenkouB = plot(senkouB, color=color.maroon, title="Senkou B")
plot(chikou, color=color.purple, title="Chikou")
plot(ma50, color=color.orange, title="50-day MA")
plot(ma200, color=color.yellow, title="200-day MA")

// Corrected fill function
fill(pSenkouA, pSenkouB, color=senkouA > senkouB ? color.green : color.red, transp=90)

// Debugging: Output values on the chart to see if conditions are ever met
plotshape(series=(tenkan > kijun), color=color.blue, style=shape.triangleup, title="Tenkan > Kijun")
plotshape(series=(tenkan < kijun), color=color.red, style=shape.triangledown, title="Tenkan < Kijun")
plotshape(series=(ma50 > ma200), color=color.orange, style=shape.labelup, title="MA 50 > MA 200")
plotshape(series=(ma50 < ma200), color=color.yellow, style=shape.labeldown, title="MA 50 < MA 200")

// Define the trailing stop loss using Kumo
var float trailingStopLoss = na

// Check for MA conditions (apply only if enabled)
maConditionLong = not useMAFilter or (useMAFilter and ma50 > ma200)
maConditionShort = not useMAFilter or (useMAFilter and ma50 < ma200)

// Check for Ichimoku Cloud conditions
ichimokuLongCondition = close > math.max(senkouA, senkouB)
ichimokuShortCondition = close < math.min(senkouA, senkouB)

// Check for RSI conditions (apply only if enabled)
rsiConditionLong = not useRSIFilter or (useRSIFilter and rsiSource > rsiOverbought)
rsiConditionShort = not useRSIFilter or (useRSIFilter and rsiSource < rsiOversold)

// Combine conditions for entry
longCondition = maConditionLong and tenkan > kijun and ichimokuLongCondition and rsiConditionLong
shortCondition = maConditionShort and tenkan < kijun and ichimokuShortCondition and rsiConditionShort

// Date and time filter
withinDateRange = true

// Check for Long Condition
if (longCondition and withinDateRange)
    strategy.entry("Long", strategy.long)
    trailingStopLoss := math.min(senkouA, senkouB)
    alert("Buy Signal: Entering Long Position", alert.freq_once_per_bar_close)

// Check for Short Condition
if (shortCondition and withinDateRange)
    strategy.entry("Short", strategy.short)
    trailingStopLoss := math.max(senkouA, senkouB)
    alert("Sell Signal: Entering Short Position", alert.freq_once_per_bar_close)

// Exit conditions
exitLongCondition = close < kijun or tenkan < kijun
exitShortCondition = close > kijun or tenkan > kijun

if (exitLongCondition and strategy.position_size > 0)
    strategy.close("Long")
    alert("Exit Signal: Closing Long Position", alert.freq_once_per_bar_close)

if (exitShortCondition and strategy.position_size < 0)
    strategy.close("Short")
    alert("Exit Signal: Closing Short Position", alert.freq_once_per_bar_close)

// Apply trailing stop loss
if (strategy.position_size > 0)
    strategy.exit("Trailing Stop Long", stop=trailingStopLoss)
else if (strategy.position_size < 0)
    strategy.exit("Trailing Stop Short", stop=trailingStopLoss)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Technical-Indicator-Trend-Following-Strategy-with-Ichimoku-Cloud-Breakout-and-Stop-Loss-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Quantitative Trading Strategy Based on Ichimoku with Multiple SignalsPine Script · Breakout · 1h
- Ichimoku Entries StrategyPine Script · Breakout · 1d
- MACD Bollinger Turtle Trading StrategyPine Script · Breakout · 1d
- Multi Dimensional Ichimoku Cloud Price Breakthrough Trend Confirmation Trading StrategyPine Script · Breakout · 10m
- Dynamic Filter Quant Trading StrategyPine Script · Breakout · 1d
- Multi Indicator Trend Following and Volatility Breakout StrategyPine Script · Breakout · 2h