Strategy vault / Multi-timeframe
Multi Timeframe Adaptive Dynamic KDJ Indicator Strategy
This is an innovative multi-timeframe adaptive KDJ oscillator strategy designed to provide more precise and flexible trading signals by dynamically adjusting indicator parameters and analyzing market trends across…
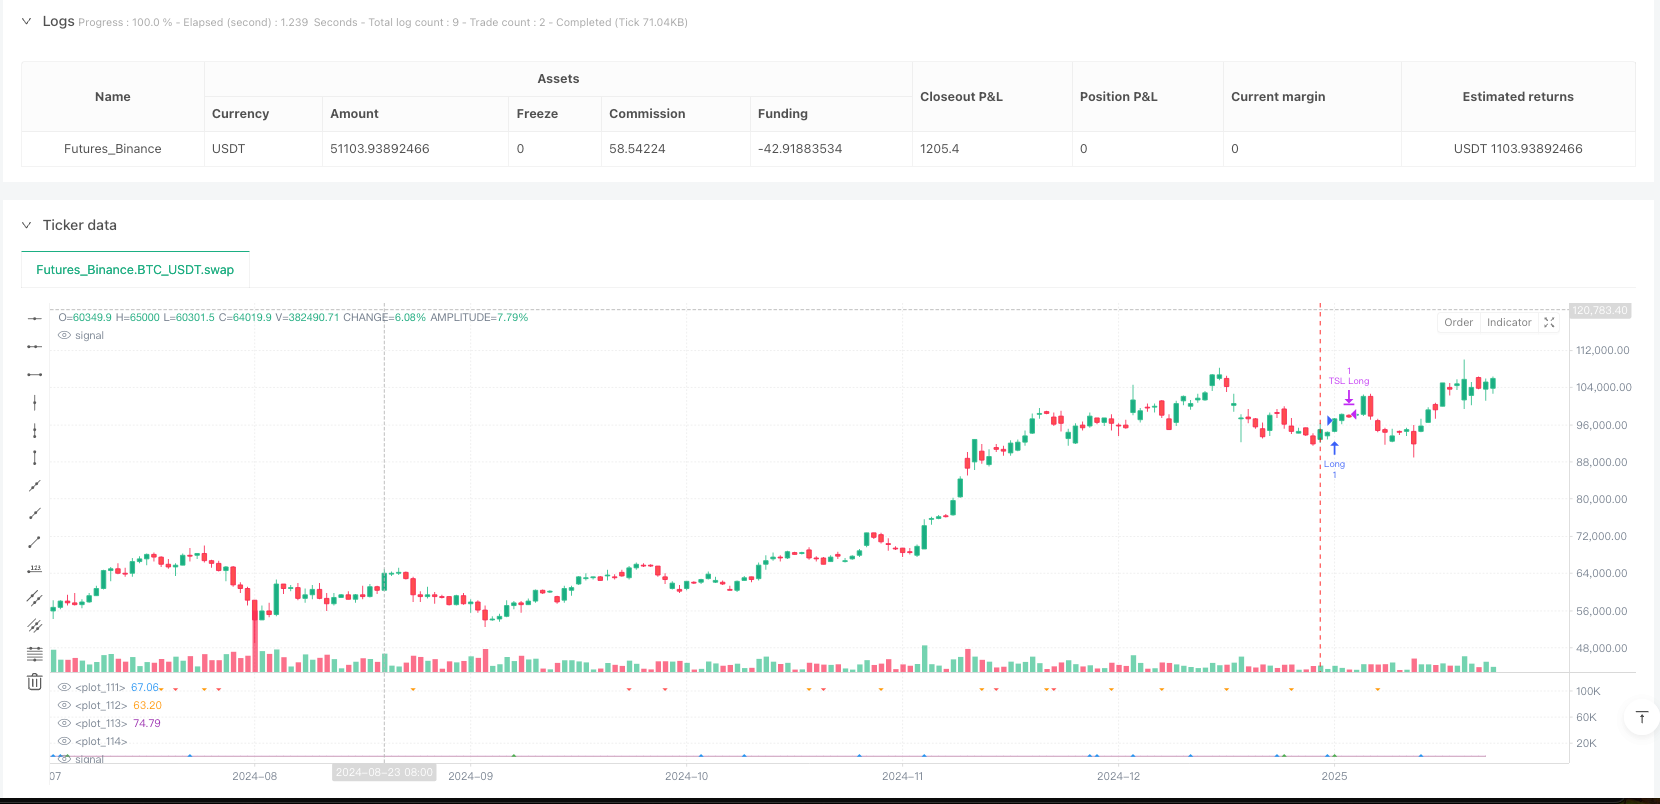
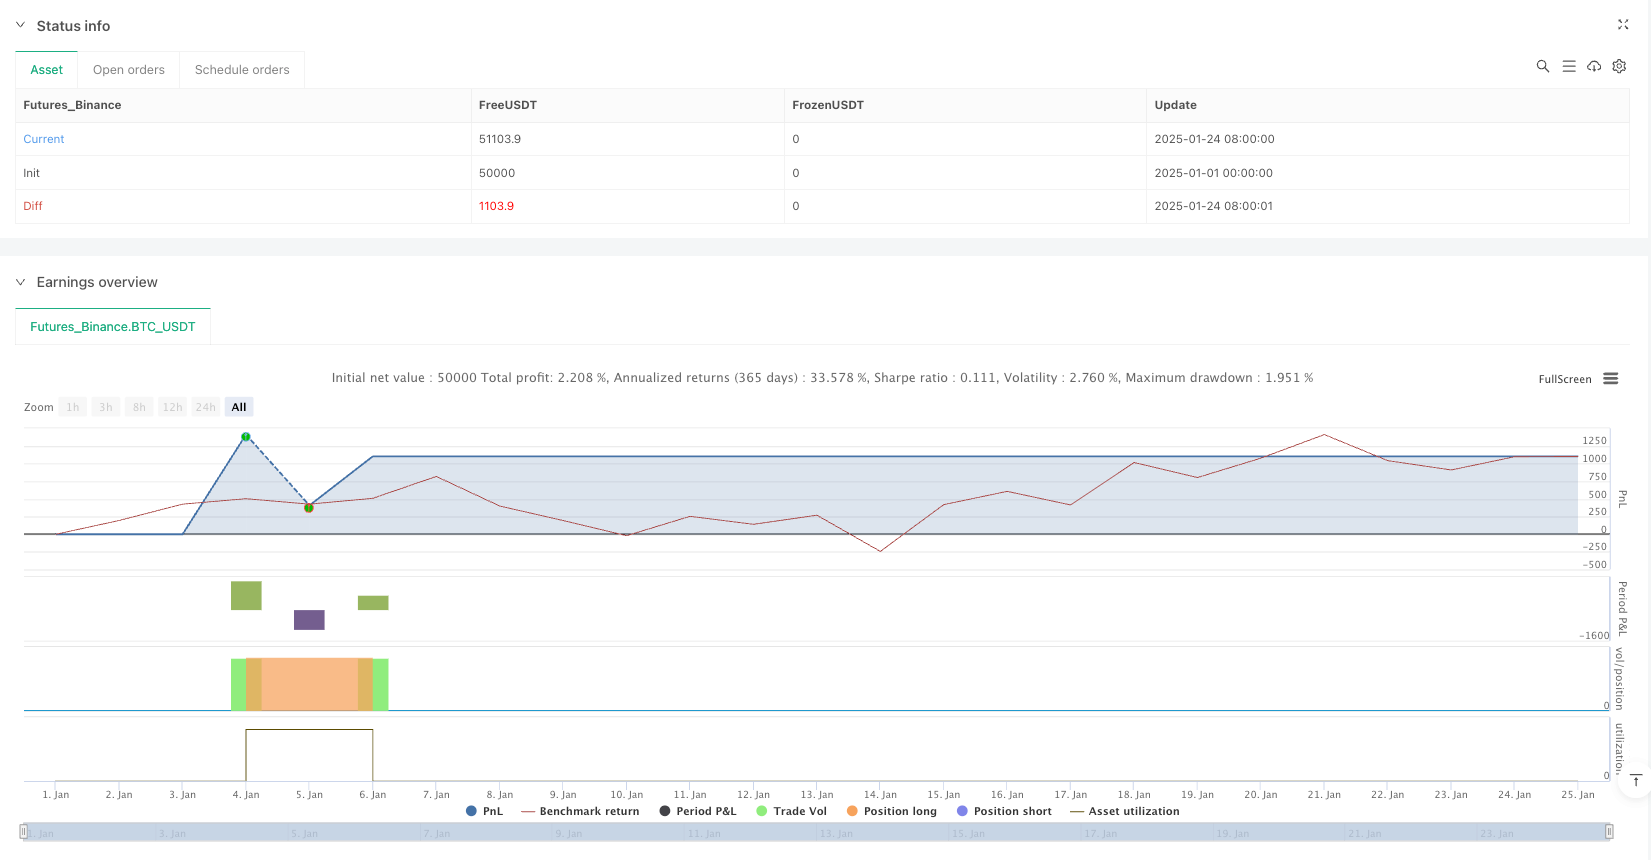
Overview
This is an innovative multi-timeframe adaptive KDJ oscillator strategy designed to provide more precise and flexible trading signals by dynamically adjusting indicator parameters and analyzing market trends across multiple timeframes. The strategy combines volatility-based length calculation, multi-timeframe weight allocation, and adaptive trend determination, offering traders a sophisticated and powerful analysis tool.
Strategy Principles
The core principles of the strategy include the following key technologies:
- Multi-timeframe analysis: Simultaneously using 1-minute, 5-minute, and 15-minute timeframes
- Adaptive swing length calculation: Dynamically adjusting indicator parameters based on market volatility
- Dynamic weight allocation: Assigning different weight coefficients to different timeframes
- Trend determination mechanism: Determining market trend direction by calculating the average of smoothAvgTotal
- Intelligent signal generation: Combining primary signals and anticipated signals to improve signal accuracy
Strategy Advantages
- High flexibility: Customizable timeframe and weight configuration
- Dynamic adaptability: Adjusting indicator parameters based on market volatility
- Multi-dimensional analysis: Integrating information from multiple timeframes
- Low-latency signals: Including primary and anticipated signals
- Built-in trend filtering: Reducing false signals in unfavorable market conditions
Strategy Risks
- Parameter overfitting risk
- Increased signal complexity with multiple timeframes
- Potential signal reliability reduction in extreme market conditions
- Requires additional confirmation indicators to validate signals
Strategy Optimization Directions
- Introduce machine learning algorithms for dynamic weight adjustment
- Add additional filtering conditions
- Optimize stop-loss mechanisms
- Develop cross-instrument adaptability
Summary
The multi-timeframe adaptive KDJ oscillator strategy provides traders with a flexible, dynamic, and multi-dimensional market analysis tool through innovative design, offering significant technical advantages and potential performance improvement space.
Source Pine Script
/*backtest
start: 2025-01-01 00:00:00
end: 2025-01-25 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ is subject to the Mozilla Public License 2.0 (https://mozilla.org/MPL/2.0/)
// © Lausekopf

//@version=5
strategy("Adaptive KDJ (MTF)", overlay=false)

// Dropdown for the swing length calculation method
method = input.int(1, title="Calculation Method", options=[1, 2, 3], tooltip="1: Volatility Based\n2: Inverse Volatility\n3: Fixed Length")

// Fixed length for method 3
fixedLength = input.int(9, title="Fixed KDJ Length", minval=3, maxval=15)

// Timeframes
tf1 = input.timeframe("1", title="Timeframe 1")
tf2 = input.timeframe("5", title="Timeframe 2")
tf3 = input.timeframe("15", title="Timeframe 3")

// Timeframe weighting
weightOption = input.int(1, title="Timeframe Weighting", options=[1, 2, 3, 4, 5])
weightTF1 = weightOption == 1 ? 0.5 : weightOption == 2 ? 0.4 : weightOption == 3 ? 0.33 : weightOption == 4 ? 0.2 : 0.1
weightTF2 = 0.33
weightTF3 = 1.0 - (weightTF1 + weightTF2)

// EMA smoothing length
smoothingLength = input.int(5, title="EMA Smoothing Length", minval=1, maxval=50)

// Trend calculation period
trendLength = input.int(40, title="Trend Calculation Period", minval=5, maxval=50)

// KDJ function
f_kdj(len, srcHigh, srcLow, srcClose) =>
    roundedLen = int(math.round(len))
    high_max = ta.highest(srcHigh, roundedLen)
    low_min = ta.lowest(srcLow, roundedLen)
    rsv = 100 * (srcClose - low_min) / (high_max - low_min)
    k = ta.sma(rsv, 3)
    d = ta.sma(k, 3)
    j = 3 * k - 2 * d
    [k, d, j]

// Swing length function
f_swingLength(tf) =>
    atrLen = 14
    volatility = request.security(syminfo.tickerid, tf, ta.atr(atrLen) / close)
    var float length = na
    if method == 1
        length := volatility > 0.03 ? 3 : volatility > 0.002 ? 14 : 15
    if method == 2
        length := 18
    if method == 3
        length := fixedLength
    length

// Calculate swing lengths for each timeframe
swingLength1 = f_swingLength(tf1)
swingLength2 = f_swingLength(tf2)
swingLength3 = f_swingLength(tf3)

// Calculate KDJ values
[k1, d1, j1] = f_kdj(swingLength1, request.security(syminfo.tickerid, tf1, high), request.security(syminfo.tickerid, tf1, low), request.security(syminfo.tickerid, tf1, close))
[k2, d2, j2] = f_kdj(swingLength2, request.security(syminfo.tickerid, tf2, high), request.security(syminfo.tickerid, tf2, low), request.security(syminfo.tickerid, tf2, close))
[k3, d3, j3] = f_kdj(swingLength3, request.security(syminfo.tickerid, tf3, high), request.security(syminfo.tickerid, tf3, low), request.security(syminfo.tickerid, tf3, close))

// Weighted averages
avgK = (k1 * weightTF1 + k2 * weightTF2 + k3 * weightTF3)
avgD = (d1 * weightTF1 + d2 * weightTF2 + d3 * weightTF3)
avgJ = (j1 * weightTF1 + j2 * weightTF2 + j3 * weightTF3)
smoothAvgK = ta.ema(avgK, smoothingLength)
smoothAvgD = ta.ema(avgD, smoothingLength)
smoothAvgJ = ta.ema(avgJ, smoothingLength)
smoothAvgTotal = ta.ema((avgK + avgD + avgJ) / 3, smoothingLength)

// Trend determination
trendAvg = ta.sma(smoothAvgTotal, trendLength)
isUptrend = trendAvg > 60
isDowntrend = trendAvg < 40

// Dynamic signal thresholds
buyLevel = isUptrend ? 40 : isDowntrend ? 15 : 25
sellLevel = isUptrend ? 85 : isDowntrend ? 60 : 75

// Buy/Sell signals
buySignal = smoothAvgJ < buyLevel and ta.crossover(smoothAvgK, smoothAvgD)
sellSignal = smoothAvgJ > sellLevel and ta.crossunder(smoothAvgK, smoothAvgD)

// Anticipated signals
anticipateBuy = (smoothAvgK - smoothAvgK[1]) > 0 and (smoothAvgD - smoothAvgD[1]) < 0 and math.abs(smoothAvgK - smoothAvgD) < 5
anticipateSell = (smoothAvgK - smoothAvgK[1]) < 0 and (smoothAvgD - smoothAvgD[1]) > 0 and math.abs(smoothAvgK - smoothAvgD) < 5

// Entry conditions
longEntryCondition = (buySignal or anticipateBuy) and smoothAvgTotal < 22
shortEntryCondition = (sellSignal or anticipateSell) and smoothAvgTotal > 78

// Entry orders
strategy.entry("Long", strategy.long, when=longEntryCondition)
strategy.entry("Short", strategy.short, when=shortEntryCondition)

// Trailing Stop-Loss
atrMultiplierTSL = 2.5
atrValueTSL = ta.atr(12) * atrMultiplierTSL
strategy.exit("TSL Long", from_entry="Long", trail_points=atrValueTSL / syminfo.mintick, stop=open * 0.9972)
strategy.exit("TSL Short", from_entry="Short", trail_points=atrValueTSL / syminfo.mintick, stop=open * 1.0028)

// Plot signals
plotshape(series=buySignal, location=location.bottom, style=shape.triangleup, color=color.green, size=size.small)
plotshape(series=sellSignal, location=location.top, style=shape.triangledown, color=color.red, size=size.small)
plotshape(series=anticipateBuy, location=location.bottom, style=shape.triangleup, color=color.blue, size=size.tiny, offset=-1)
plotshape(series=anticipateSell, location=location.top, style=shape.triangledown, color=color.orange, size=size.tiny, offset=-1)

// Plot KDJ lines
plot(smoothAvgK, color=color.blue, linewidth=1)
plot(smoothAvgD, color=color.orange, linewidth=1)
plot(smoothAvgJ, color=color.purple, linewidth=1)
plot(smoothAvgTotal, color=color.white, linewidth=1)

// Alert for impending signals
alertcondition(anticipateBuy or anticipateSell, title='Impending KDJ Crossover', message='Possible KDJ crossover detected!')
// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Lausekopf
Published by ianzeng123 on the FMZ strategy square · last modified 2025-04-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Timeframe-Adaptive-Dynamic-KDJ-Indicator-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA RSI and MACD Based Multi Timeframe Trading StrategyPine Script · Multi-timeframe · 1h
- Multi Timeframe Dynamic Stop Loss EMA Squeeze Trading StrategyPine Script · Multi-timeframe · 1h
- Multi Timeframe Adaptive Market Regime Quantitative Trading StrategyPine Script · Multi-timeframe · 1m
- Long and Short Opening Strategy Based on Multi Timeframe Moving Average and MACDPine Script · Multi-timeframe · 1h
- Multi Timeframe Dynamic EMA Trading StrategyPine Script · Multi-timeframe · 1h
- Multi Timeframe MACD Trading StrategyPine Script · Multi-timeframe · 1h