Multi Timeframe Donchian Channel and ATR Dynamic Interval Volatility Following Trading Strategy
This strategy is a trend-following trading system based on the Donchian Channel and Average True Range (ATR). It utilizes the deviation between the middle band of the Donchian Channel calculated on 4-hour candles and…
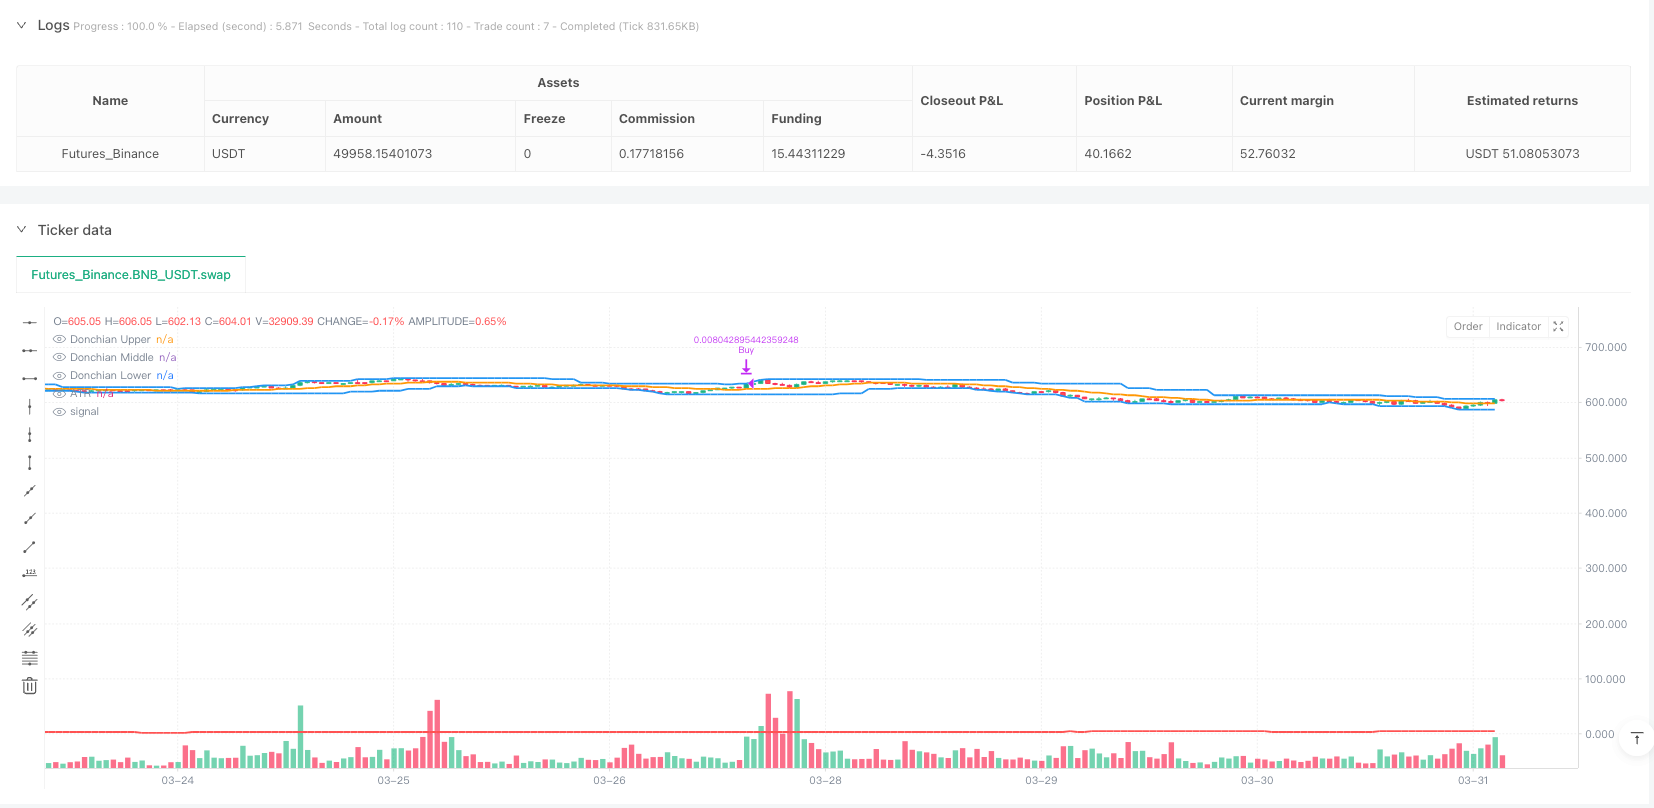
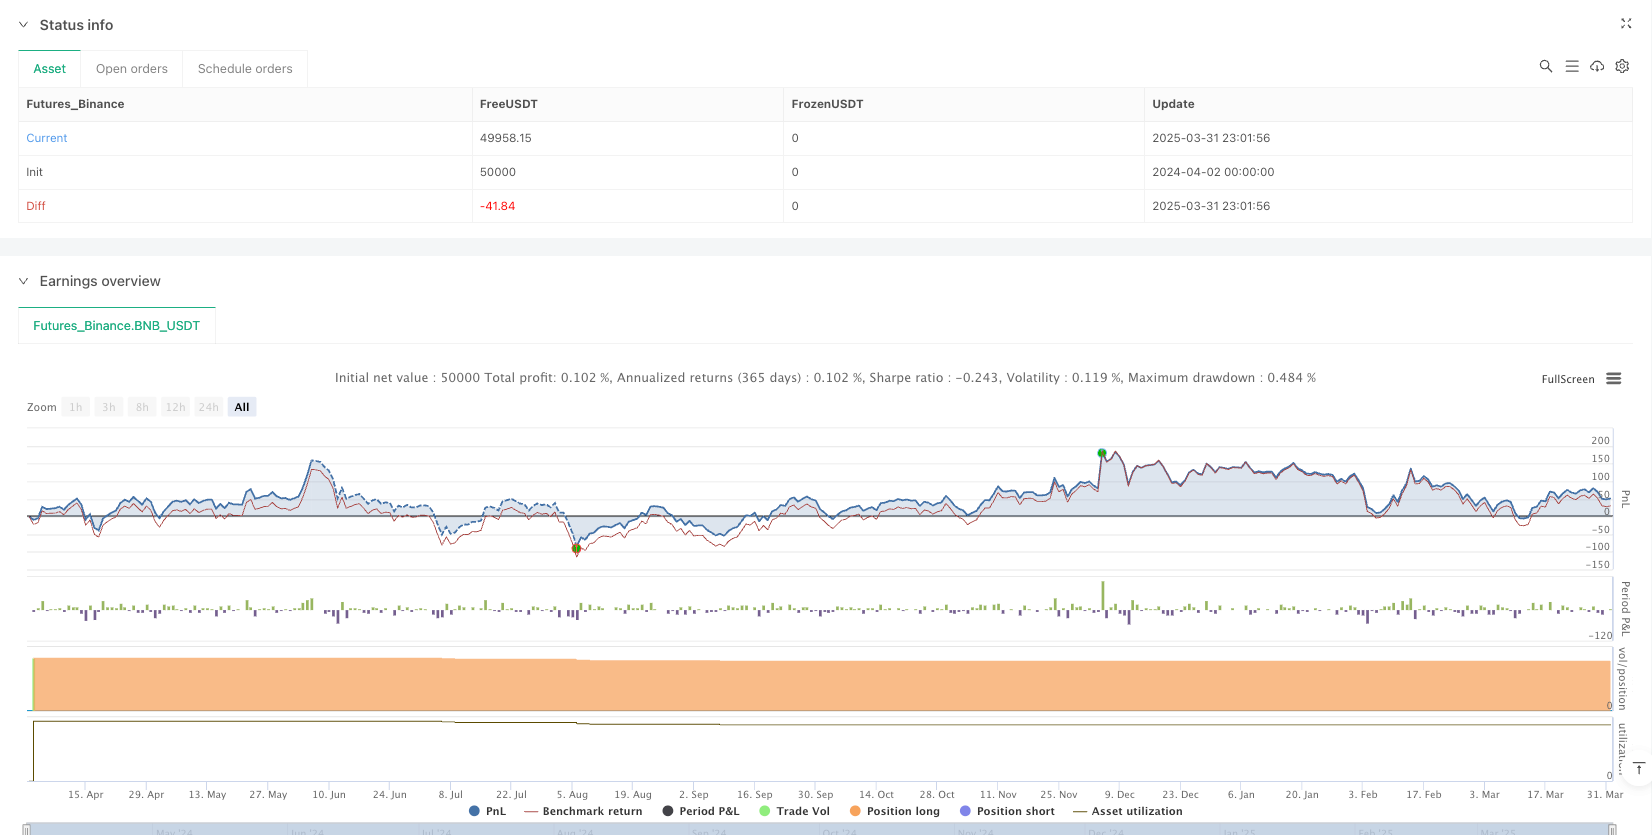
Strategy Overview
This strategy is a trend-following trading system based on the Donchian Channel and Average True Range (ATR). It utilizes the deviation between the middle band of the Donchian Channel calculated on 4-hour candles and the current price, combined with ATR as a dynamic volatility measurement indicator, to identify entry and exit opportunities in market fluctuations. The strategy employs a gradient position building and stop-loss mechanism, managing positions through fixed trading amounts (5.1 USDT) to achieve effective capital utilization during high volatility market conditions.
Strategy Principles
The core logic of the strategy is based on the following key elements:
- Multi-timeframe Analysis Framework: The strategy executes trades on 1-minute candles but calculates technical indicators using 4-hour candle (240-minute) data, leveraging the advantages of multi-timeframe analysis.
- Donchian Channel Calculation: Based on 20 periods of 4-hour candle data, it calculates the upper band (highest price), lower band (lowest price), and middle band (simple moving average of closing prices).
- Dynamic Interval Determination: Uses twice the ATR value as a dynamic trading interval, allowing the strategy to self-adapt to changes in market volatility.
- Trade Execution Logic:
- Initial state (no position): Executes first purchase when the Donchian middle band minus the current price exceeds the set interval.
- Position state: Adds or reduces positions when the difference between the base price and current price exceeds the interval.
- Position management: Fixed amount (5.1 USDT) per trade, calculating the trading quantity based on the current price.
- Closing mechanism: Executes selling when the price rises above the interval; if the position is insufficient, sells all available positions.
Strategy Advantages
- Multi-timeframe Analysis Benefits: By executing trades on shorter timeframes (1-minute candles) but making decisions based on longer timeframe (4-hour candles) technical indicators, it reduces interference from short-term market noise while maintaining the ability to track medium to long-term trends.
- Dynamic Adaptation to Market Volatility: Using ATR as a volatility measure, the strategy can automatically adjust trading intervals according to changes in market volatility, setting larger intervals in high-volatility markets and smaller intervals in low-volatility markets.
- Gradient Position Building Mechanism: When prices continue to fall, the strategy adds positions at each interval point, averaging entry costs and reducing risk exposure from single trades.
- Fixed Amount Trading: Each trade uses a fixed amount rather than a fixed quantity, which better aligns with risk management principles, avoiding excessive investment at high price points or insufficient investment at low price points.
- Comprehensive Logging: The strategy implements detailed trade logging and visual labeling, including trade type, price, interval, quantity, and total position information, facilitating backtesting analysis and strategy optimization.
Strategy Risks
- Trend Reversal Risk: During strong trend reversals, the strategy may fail to identify market turns in a timely manner, leading to significant losses after consecutive position additions. Solution: Introduce trend confirmation indicators or set limits on maximum position additions.
- Capital Depletion Risk: In continuous one-way markets, multiple fixed-amount additions may lead to rapid or excessive capital concentration. Solution: Set total capital usage ratio limits or dynamically adjust single trade amounts.
- Parameter Sensitivity: The choice of ATR multiplier (2x) and Donchian Channel period (20) significantly impacts strategy performance; improper parameter settings may lead to excessive or insufficient signals. Solution: Find optimal parameter combinations through historical backtesting or implement parameter adaptive mechanisms.
- Liquidity Risk: In low-liquidity markets, market orders may result in significant slippage, affecting the actual execution of the strategy. Solution: Consider using limit orders or adding liquidity filtering conditions.
- Commission Cost Accumulation: The strategy may trade frequently, generating substantial transaction costs (set at 0.1%), potentially eroding profits over time. Solution: Optimize trading frequency or consider exchanges with lower commissions.
Strategy Optimization Directions
- Add Market Environment Filtering: Combine volatility indicators (such as Bollinger Band width or relative ATR values) to determine the current market environment and adjust strategy parameters or pause trading in different market states. This helps avoid cost losses from frequent trading in low-volatility or oscillating markets.
- Dynamic Adjustment of ATR Multiplier: Dynamically adjust the ATR multiplier based on historical volatility or market trend strength, using smaller multipliers in strong trend markets to track prices more closely and larger multipliers in oscillating markets to reduce false signals.
- Introduce Stop-Loss Mechanisms: Set maximum loss limits or trailing stops to prevent excessive losses on single trades. Especially after multiple position additions, consider setting comprehensive stop-loss levels to protect capital.
- Optimize Position Management: Consider using decreasing or increasing trade amounts rather than fixed amounts, dynamically adjusting the capital proportion of each trade based on the size of existing positions or market volatility.
- Add Trading Time Filters: Analyze performance across different trading sessions to avoid inefficient or high-risk periods, such as crossover times between Asian, European, and American trading sessions or before/after major economic data releases.
- Integrate Other Confirmation Indicators: Combine with indicators such as RSI, MACD for auxiliary confirmation to improve signal quality and reduce false entries.
- Adaptive Donchian Channel Period: Dynamically adjust the calculation period of the Donchian Channel based on market conditions, using shorter periods in high-volatility markets to improve response speed and longer periods in low-volatility markets to reduce noise.
Conclusion
The Multi-Timeframe Donchian Channel and ATR Dynamic Interval Volatility Following Trading Strategy is a quantitative trading system that combines technical analysis and risk management. By utilizing 4-hour period data to execute decisions on 1-minute candles, the strategy achieves effective tracking of medium-term trends while using ATR to dynamically adjust trading intervals to adapt to different market environments. Fixed amount trading and gradient position building mechanisms help with risk control and cost averaging.
This strategy is particularly suitable for high-volatility market environments but requires attention to trend reversal risks and capital management issues. Through optimization measures such as adding market environment filtering, dynamic parameter adjustments, and stop-loss mechanisms, the strategy's robustness and long-term profitability can be further improved. In practical applications, it is recommended to conduct thorough backtesting, optimize parameters for specific trading instruments, and implement strict risk control measures to ensure capital safety.
Source Pine Script
/*backtest
start: 2024-04-02 00:00:00
end: 2025-04-01 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BNB_USDT"}]
*/

//@version=5
strategy("Donchian Channel and ATR Strategy", overlay=true, currency="USDT", commission_type=strategy.commission.percent, commission_value=0.1)

// UsepineWrite strategy, execute in real-time.
// Obtainsuiusdtcontract4Hourly K-Line,Use4HourkLine20Period, calculate Donchian Channel andATR.
// Latest ATR * 2 As interval. Each buy/sell amount is5.1usdt,calculate the trading quantity based on the amount.

// Strategy Based On1Minutekline execution.
// at start,basepriceis empty.
// if in the middle band of the Donchian Channel - Current Price  > Interval, then buy at market price5.1usdt,Record transaction price as baseprice.
// Recalculate Donchian Channel andATR, Still Use4Hourly K-Lineof20Periods.

// basepricenot empty,
// If baseprice - Current Price  > Interval, then buy at market price5.1usdt,Record transaction price as baseprice;
// If current price - baseprice > Interval, then sell at market price5.1usdt,Record transaction price as baseprice.
// When selling, judge whether the position is enough to sell. If not, sell the remaining position. After selling, if there is no position left, setbasepriceis empty.

// Labels and logging: Buy or Sell(buy/sell),First purchase marked asinitBuy,Price, interval, quantity purchased, total quantity of position after purchase.
// Use different colors to distinguish buy and sell.


// Obtain4Hourly K-LineData
resolution_4h = "240"  // 4Hourly K-Line
high_4h = request.security(syminfo.tickerid, resolution_4h, high)
low_4h = request.security(syminfo.tickerid, resolution_4h, low)
close_4h = request.security(syminfo.tickerid, resolution_4h, close)

// Calculate the Donchian channel sumATR(Based on4Hourly K-Line)
length = 20
donchian_upper = ta.highest(high_4h, length)
donchian_lower = ta.lowest(low_4h, length)
donchian_middle = ta.sma(close_4h, length)
atr_value = ta.atr(length)  // Use4Hourly K-LineCalculationATR

// Set trading parameters
trade_amount = 5.1  // Amount per trade(USDT)
var float baseprice = na  // Current reference price
var float total_position_qty = 0  // Total position quantity

// Logging function
log_trade(action, price, interval, qty, total_qty, color) =>
    log_text = str.format("{0} @ {1} | Interval: {2} | Qty: {3} | Total Qty: {4}",
                          action, str.tostring(price), str.tostring(interval),
                          str.tostring(qty), str.tostring(total_qty))


// Strategy Logic
interval = atr_value * 2  // Interval = ATR * 2
if (na(baseprice))
    if (donchian_middle - close > interval)  // Use1MinuteKLine'sclosePrice Judgment
        qty = trade_amount / close  // Calculate trading quantity
        strategy.entry("Buy", strategy.long, qty=qty)
        baseprice := close  // Update reference price
        total_position_qty += qty  // Update total position quantity
        log_trade("initBuy", baseprice, interval, qty, total_position_qty, color.green)  // Record logs and tags

else
    if (baseprice - close > interval)  // Use1MinuteKLine'sclosePrice Judgment
        qty = trade_amount / close
        strategy.entry("Buy", strategy.long, qty=qty)
        baseprice := close
        total_position_qty += qty
        log_trade("Buy", baseprice, interval, qty, total_position_qty, color.blue)

    else if (close - baseprice > interval)
        if (total_position_qty > 0)
            qty = trade_amount / close
            if (total_position_qty >= qty)
                strategy.close("Buy", qty=qty)
                total_position_qty -= qty
                log_trade("Sell", baseprice, interval, qty, total_position_qty, color.red)
            else
                strategy.close("Buy")
                total_position_qty := 0
                log_trade("Sell (Full Position)", baseprice, interval, total_position_qty, 0, color.red)
        baseprice := na  // Clear reference price

// Draw Tang Qian Channel andATR(Based on4Hourly K-Line)
plot(donchian_upper, title="Donchian Upper", color=color.blue, linewidth=2)
plot(donchian_middle, title="Donchian Middle", color=color.orange, linewidth=2)
plot(donchian_lower, title="Donchian Lower", color=color.blue, linewidth=2)
plot(atr_value, title="ATR", color=color.red, linewidth=2)Published by ianzeng123 on the FMZ strategy square · last modified 2025-04-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Timeframe-Donchian-Channel-and-ATR-Dynamic-Interval-Volatility-Following-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Multi Indicator Trend Breakout Strategy with Dynamic Stop LossPine Script · Breakout · 1d
- Trend Following Strategy with MACD and Donchian ChannelPine Script · Breakout · 1h
- Integrated Ichimoku Keltner Trading System Based on Moving Average StrategyPine Script · Breakout · 1h
- Dynamic Oscillation Breakout StrategyPine Script · Breakout · 1d