Strategy vault / Mean reversion
Multi Timeframe Pivot Reversal Strategy with Dynamic Percentage Based Take Profit and Stop Loss System
This strategy is an advanced trading system based on multi-timeframe analysis that captures market reversal opportunities by identifying key pivot points on higher timeframes. It incorporates dynamic percentage-based…
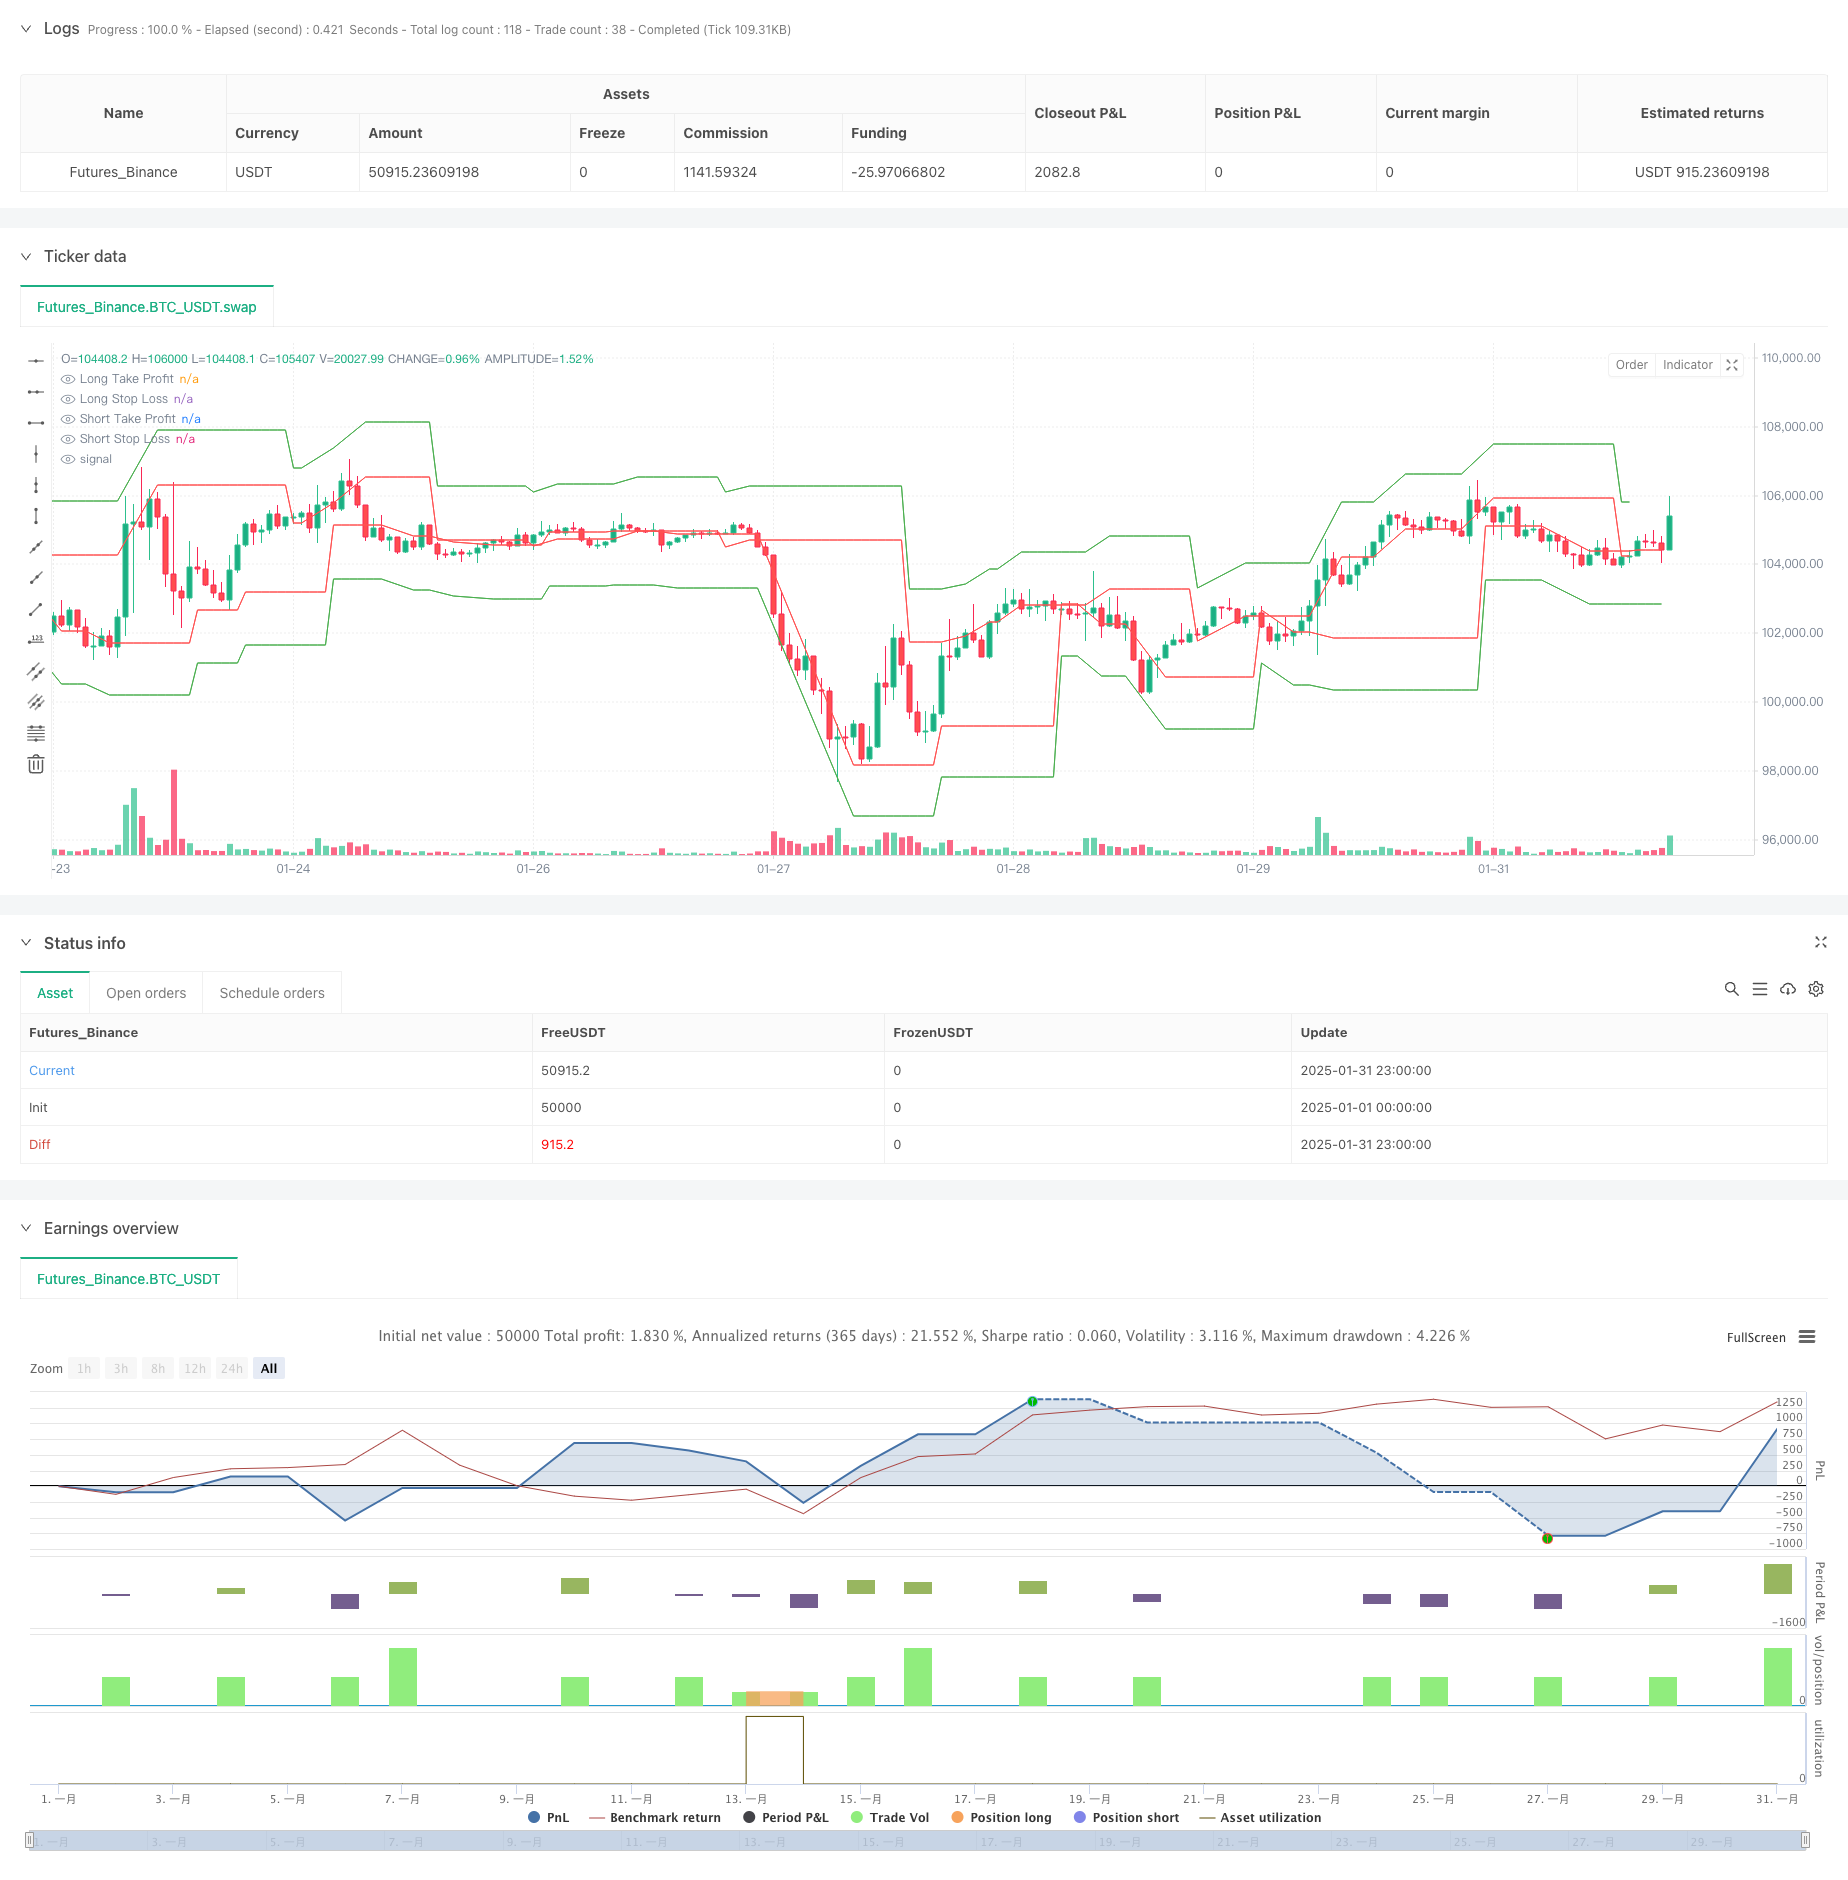
Overview
This strategy is an advanced trading system based on multi-timeframe analysis that captures market reversal opportunities by identifying key pivot points on higher timeframes. It incorporates dynamic percentage-based take profit and stop loss mechanisms, effectively controlling risk while pursuing stable returns. The system also includes trade interval control and time range testing functionality, making it more suitable for live trading environments.
Strategy Principles
The core logic of the strategy is based on several key elements:
- Pivot point analysis on a higher timeframe (default 60 minutes), defining pivot formation conditions through leftBars and rightBars parameters.
- Risk and profit targets managed through dynamically calculated percentage-based take profit and stop loss levels.
- Multi-timeframe analysis provides more reliable market structure judgment, reducing false signals.
- Trade interval control mechanism (default 1440 minutes) prevents overtrading and improves signal quality.
- Time range testing functionality allows strategy validation within specific historical periods.
Strategy Advantages
- Multi-timeframe analysis provides a more comprehensive market perspective, reducing false breakouts.
- Dynamic percentage-based take profit and stop loss adapt to different market conditions, improving strategy stability.
- Trade interval control effectively prevents overtrading and reduces transaction costs.
- Time range testing functionality facilitates strategy optimization and historical performance analysis.
- Clear code structure, easy to maintain and modify.
Strategy Risks
- Fixed percentage stops may not be flexible enough in highly volatile markets.
- Longer trade intervals might miss some valid signals.
- Lag in pivot point identification may lead to suboptimal entry timing.
- May generate excessive false signals in ranging markets.
Strategy Optimization Directions
- Introduce adaptive volatility indicators to dynamically adjust take profit and stop loss percentages.
- Add market environment filters to adjust strategy parameters under different trend strengths.
- Integrate volume analysis to improve entry signal reliability.
- Implement dynamic trade interval adjustments based on market volatility.
- Add trailing stop mechanism to protect accumulated profits.
Summary
The strategy provides a complete trading system framework through multi-timeframe analysis and dynamic risk management. While there are areas for optimization, the overall design concept is sound and practical. Through the suggested optimization directions, the strategy has the potential to achieve more stable performance across different market conditions.
Source Pine Script
/*backtest
start: 2025-01-01 00:00:00
end: 2025-01-31 23:59:59
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("Pivot Reversal Strategy with MTF TP & SL in Percent and Test Range", overlay=true)

// Входные параметры
higher_tf = input.timeframe("60", title="Higher Timeframe for Breakout Check")  // Таймфрейм для анализа пробоя
leftBars = input(4, title="Left Bars")
rightBars = input(2, title="Right Bars")
TP_percent = input.float(1.0, title="Take Profit (%)", minval=0.1, step=0.1)   // Тейк-профит в процентах
SL_percent = input.float(0.5, title="Stop Loss (%)", minval=0.1, step=0.1)    // Стоп-лосс в процентах
trade_interval = input.int(1440, title="Minimum Time Between Trades (Minutes)") // Интервал между сделками

// Диапазон тестирования (используем UNIX timestamps)
start_date = input(timestamp("2023-01-01 00:00 +0000"), title="Start Date")  // Стартовая дата для тестирования
end_date = input(timestamp("2023-12-31 23:59 +0000"), title="End Date")    // Конечная дата для тестирования

// Проверка, попадает ли текущая свеча в указанный диапазон времени
in_test_range = true

// Определение пивотов на более крупном таймфрейме
higher_tf_high = request.security(syminfo.tickerid, higher_tf, ta.pivothigh(leftBars, rightBars))
higher_tf_low = request.security(syminfo.tickerid, higher_tf, ta.pivotlow(leftBars, rightBars))

// Последнее время открытия сделки
var float last_trade_time = na

// Логика для лонга
swh_cond = not na(higher_tf_high)
hprice = 0.0
hprice := swh_cond ? higher_tf_high : hprice[1]
le = false
le := swh_cond ? true : (le[1] and high > hprice ? false : le[1])

if le and in_test_range and (na(last_trade_time) or (time - last_trade_time >= trade_interval * 60 * 1000))
    tp_price_long = hprice * (1 + TP_percent / 100)  // Тейк-профит в процентах
    sl_price_long = hprice * (1 - SL_percent / 100)  // Стоп-лосс в процентах
    strategy.entry("PivRevLE", strategy.long, stop=hprice + syminfo.mintick)
    strategy.exit("TP_SL_Long", from_entry="PivRevLE",
                  limit=tp_price_long,
                  stop=sl_price_long)
    last_trade_time := time

// Логика для шорта
swl_cond = not na(higher_tf_low)
lprice = 0.0
lprice := swl_cond ? higher_tf_low : lprice[1]
se = false
se := swl_cond ? true : (se[1] and low < lprice ? false : se[1])

if se and in_test_range and (na(last_trade_time) or (time - last_trade_time >= trade_interval * 60 * 1000))
    tp_price_short = lprice * (1 - TP_percent / 100)  // Тейк-профит в процентах
    sl_price_short = lprice * (1 + SL_percent / 100)  // Стоп-лосс в процентах
    strategy.entry("PivRevSE", strategy.short, stop=lprice - syminfo.mintick)
    strategy.exit("TP_SL_Short", from_entry="PivRevSE",
                  limit=tp_price_short,
                  stop=sl_price_short)
    last_trade_time := time

// Для наглядности отображаем уровни на графике
plot(le and in_test_range ? hprice * (1 + TP_percent / 100) : na, color=color.green, title="Long Take Profit")
plot(le and in_test_range ? hprice * (1 - SL_percent / 100) : na, color=color.red, title="Long Stop Loss")
plot(se and in_test_range ? lprice * (1 - TP_percent / 100) : na, color=color.green, title="Short Take Profit")
plot(se and in_test_range ? lprice * (1 + SL_percent / 100) : na, color=color.red, title="Short Stop Loss")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Timeframe-Pivot-Reversal-Strategy-with-Dynamic-Percentage-Based-Take-Profit-and-Stop-Loss-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced Fibonacci Retracement Trend Following and Reversal Trading StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Dual factor Cycle Trading StrategyPine Script · Mean reversion · 1h