Strategy vault / Trend following
Multifactor Driven Trend Trading Strategy
This strategy combines the Moving Average Convergence Divergence (MACD) indicator and the Stochastic Relative Strength Index (Stoch RSI) indicator to determine market trend direction, going long when the trend is up…
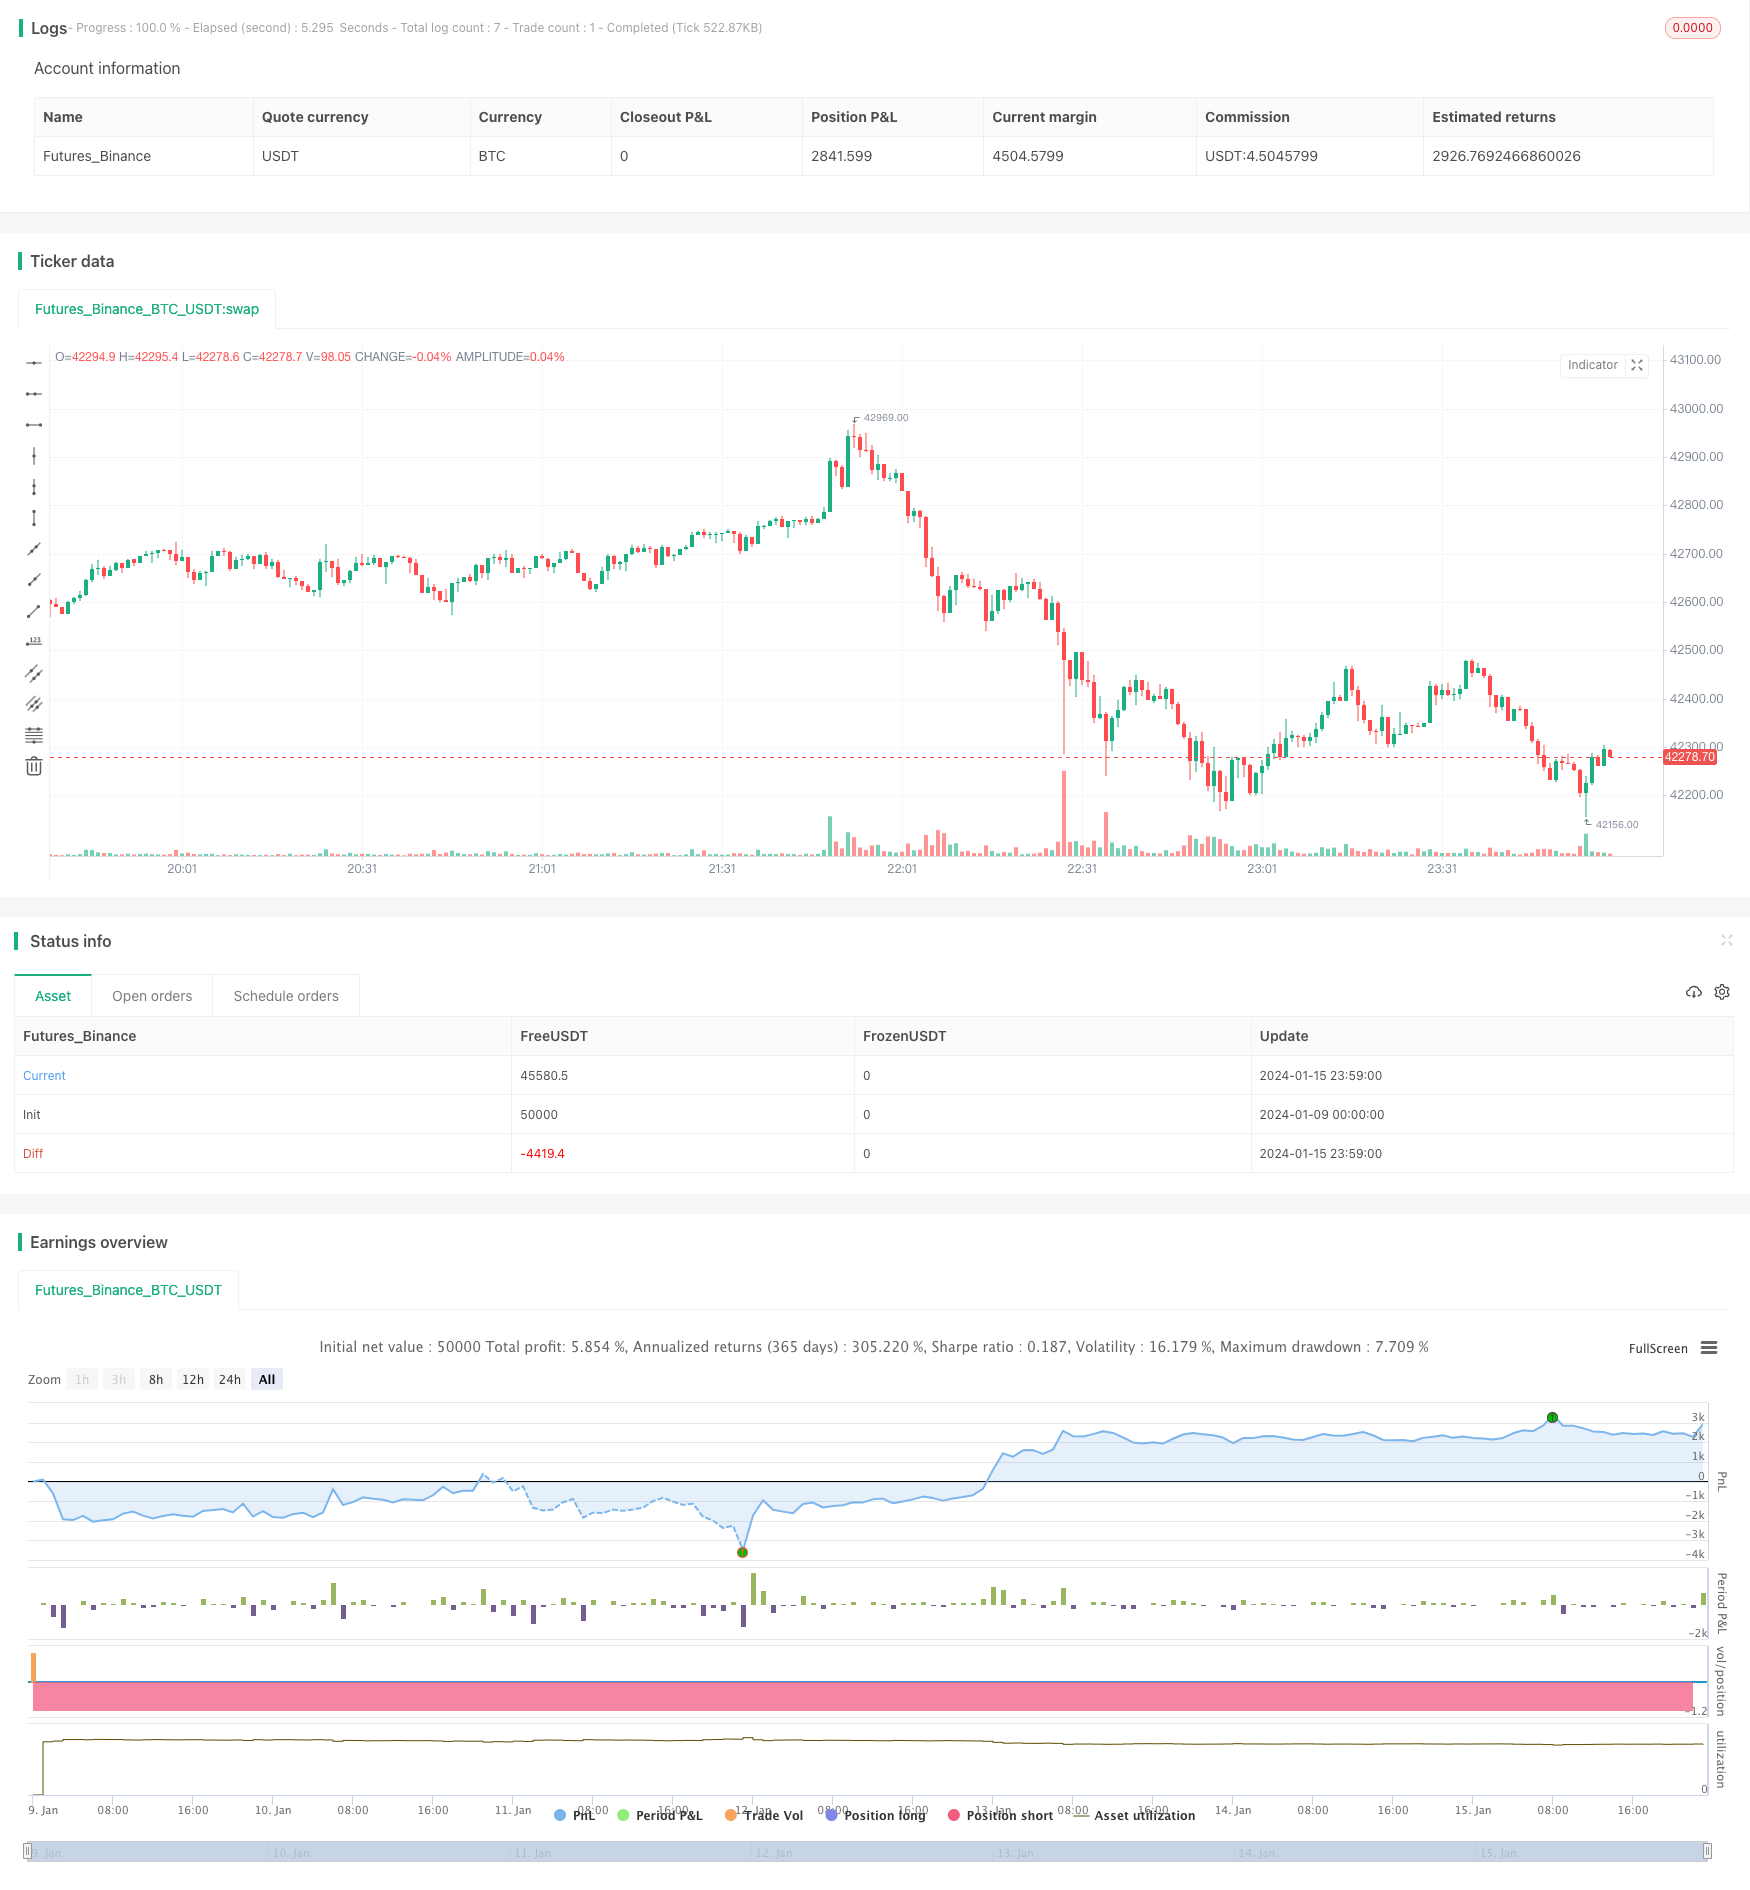
Summary
This strategy combines the Moving Average Convergence Divergence (MACD) indicator and the Stochastic Relative Strength Index (Stoch RSI) indicator to determine market trend direction, going long when the trend is up and going short when the trend is down. It belongs to the trend trading strategy category.
Strategy Logic
This strategy utilizes the MACD and Stoch RSI indicators to determine market trend direction.
The MACD indicator consists of the fast EMA line, slow EMA line and the difference between them, reflecting the convergence and divergence of short-term and long-term moving averages. When the fast line crosses above the slow line, it is a buy signal. When the fast line crosses below the slow line, it is a sell signal.
The Stoch RSI indicator combines the strengths of both the RSI and Stoch indicators to show overbought and oversold levels in the market. When Stoch RSI is greater than the Stoch RSI signal line, it is a buy signal. When it is lower than the signal line, it is a sell signal.
This strategy uses MACD and Stoch RSI on the daily and 4-hour timeframes to determine market trend. When both indicators generate buy signals on the daily and 4-hour charts, go long. When both generate sell signals, go short. This can effectively filter out false signals and improve reliability.
Advantages
Combining double factors to judge market moves can filter false signals effectively and improve signal accuracy
Validating signals across high and low timeframes (daily and 4H) avoids getting whipsawed
Following trends avoids choppy markets
Simple and clear strategy logic, easy to understand and execute
Risks and Solutions
- Inability to effectively determine trend reversal points may cause stop loss being triggered
- Optimize parameters or add other indicators to judge
- Single contract cannot diversify market systematic risks
- Increase other contracts or stocks to diversify
- Cannot determine impact of sudden big events
- Combine fundamental analysis to enhance risk awareness
Optimization Directions
Adjust MACD and Stoch RSI parameters to optimize entry and exit points
Add trailing stop strategies to lock in profits
Add position sizing to control per trade risk
Add more factors to judge to improve signal accuracy
Use machine learning methods to dynamically optimize parameters
Summary
This strategy determines trend direction via a dual factor model and validates signals across timeframes. It is a relatively stable and reliable trend following strategy, with certain risk management capabilities and room for error. Its performance can be further enhanced by adding parameters optimization, stop loss, position sizing and other modules.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | MACD Source:: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 12 | MACD Fast Length: |
| v_input_3 | 26 | MACD Slow Length: |
| v_input_4 | 9 | MACD Signal Smoothing: |
| v_input_5_close | 0 | SRSI Source:: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | 14 | SRSI RSI Length: |
| v_input_7 | 14 | SRSI Stoch Length: |
| v_input_8 | 3 | SRSI Smoothing: |
| v_input_9 | 3 | SRSI Signal Smoothing: |
| v_input_10 | true | Trade Size in USD: |
| v_input_11 | true | Perform buy trading? |
| v_input_12 | true | Perform sell trading? |
Source Pine Script
/*backtest
start: 2024-01-09 00:00:00
end: 2024-01-16 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title='[RS]Khizon (UGAZ) Strategy V0', shorttitle='K', overlay=false, pyramiding=0, initial_capital=100000, currency=currency.USD)
//  ||  Inputs:
macd_src = input(title='MACD Source:',  defval=close)
macd_fast = input(title='MACD Fast Length:',  defval=12)
macd_slow = input(title='MACD Slow Length:',  defval=26)
macd_signal_smooth = input(title='MACD Signal Smoothing:',  defval=9)
srsi_src = input(title='SRSI Source:',  defval=close)
srsi_rsi_length = input(title='SRSI RSI Length:',  defval=14)
srsi_stoch_length = input(title='SRSI Stoch Length:',  defval=14)
srsi_smooth = input(title='SRSI Smoothing:',  defval=3)
srsi_signal_smooth = input(title='SRSI Signal Smoothing:',  defval=3)
//  ||  Strategy Inputs:
trade_size = input(title='Trade Size in USD:', type=float, defval=1)
buy_trade = input(title='Perform buy trading?', type=bool, defval=true)
sel_trade = input(title='Perform sell trading?', type=bool, defval=true)
//  ||  MACD(close, 12, 26, 9):     ||---------------------------------------------||
f_macd_trigger(_src, _fast, _slow, _signal_smooth)=>
    _macd = ema(_src, _fast) - ema(_src, _slow)
    _signal = sma(_macd, _signal_smooth)
    _return_trigger = _macd >= _signal ? true : false
//  ||  Stoch RSI(close, 14, 14, 3, 3)  ||-----------------------------------------||
f_srsi_trigger(_src, _rsi_length, _stoch_length, _smooth, _signal_smooth)=>
    _rsi = rsi(_src, _rsi_length)
    _stoch = sma(stoch(_rsi, _rsi, _rsi, _stoch_length), _smooth)
    _signal = sma(_stoch, _signal_smooth)
    _return_trigger = _stoch >= _signal ? true : false
//  ||-----------------------------------------------------------------------------||
//  ||-----------------------------------------------------------------------------||
//  ||  Check Directional Bias from daily timeframe:
daily_trigger = security('NGAS', 'D', f_macd_trigger(macd_src, macd_fast, macd_slow, macd_signal_smooth) and f_srsi_trigger(srsi_src, srsi_rsi_length, srsi_stoch_length, srsi_smooth, srsi_signal_smooth))
h4_trigger = security('NGAS', '240', f_macd_trigger(macd_src, macd_fast, macd_slow, macd_signal_smooth) and f_srsi_trigger(srsi_src, srsi_rsi_length, srsi_stoch_length, srsi_smooth, srsi_signal_smooth))

plot(title='D1T', series=daily_trigger?0:na, style=circles, color=blue, linewidth=4, transp=65)
plot(title='H4T', series=h4_trigger?0:na, style=circles, color=navy, linewidth=2, transp=0)

sel_open = sel_trade and not daily_trigger and not h4_trigger
buy_open = buy_trade and daily_trigger and h4_trigger
sel_close = not buy_trade and daily_trigger and h4_trigger
buy_close = not sel_trade and not daily_trigger and not h4_trigger
strategy.entry('sel', long=false, qty=trade_size, comment='sel', when=sel_open)
strategy.close('sel', when=sel_close)
strategy.entry('buy', long=true, qty=trade_size, comment='buy', when=buy_open)
strategy.close('buy', when=buy_close)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multifactor-Driven-Trend-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Trading Strategy Following Dual Timeframe TrendsPine Script · Trend following · 1h
- BlackBit Trader XO Macro Trend Scanner StrategyPine Script · Trend following · 1h
- Mini Pullback Supertrend StrategyPine Script · Trend following · 1h
- Multi Technical Indicator Moving Average Crossover Trend Following Quantitative Trading StrategyPine Script · Trend following · 1h
- Three Exponential Moving Averages and Stochastic Relative Strength Index Trading StrategyPine Script · Trend following · 1h