Strategy vault / Trend following
Multiple Moving Average Crossover Trend Capture Strategy
This strategy is a trading system based on the crossing signals of 1/2/4-period Simple Moving Averages (SMA). It captures market trend reversal points by observing the simultaneous crossing of short-period and…
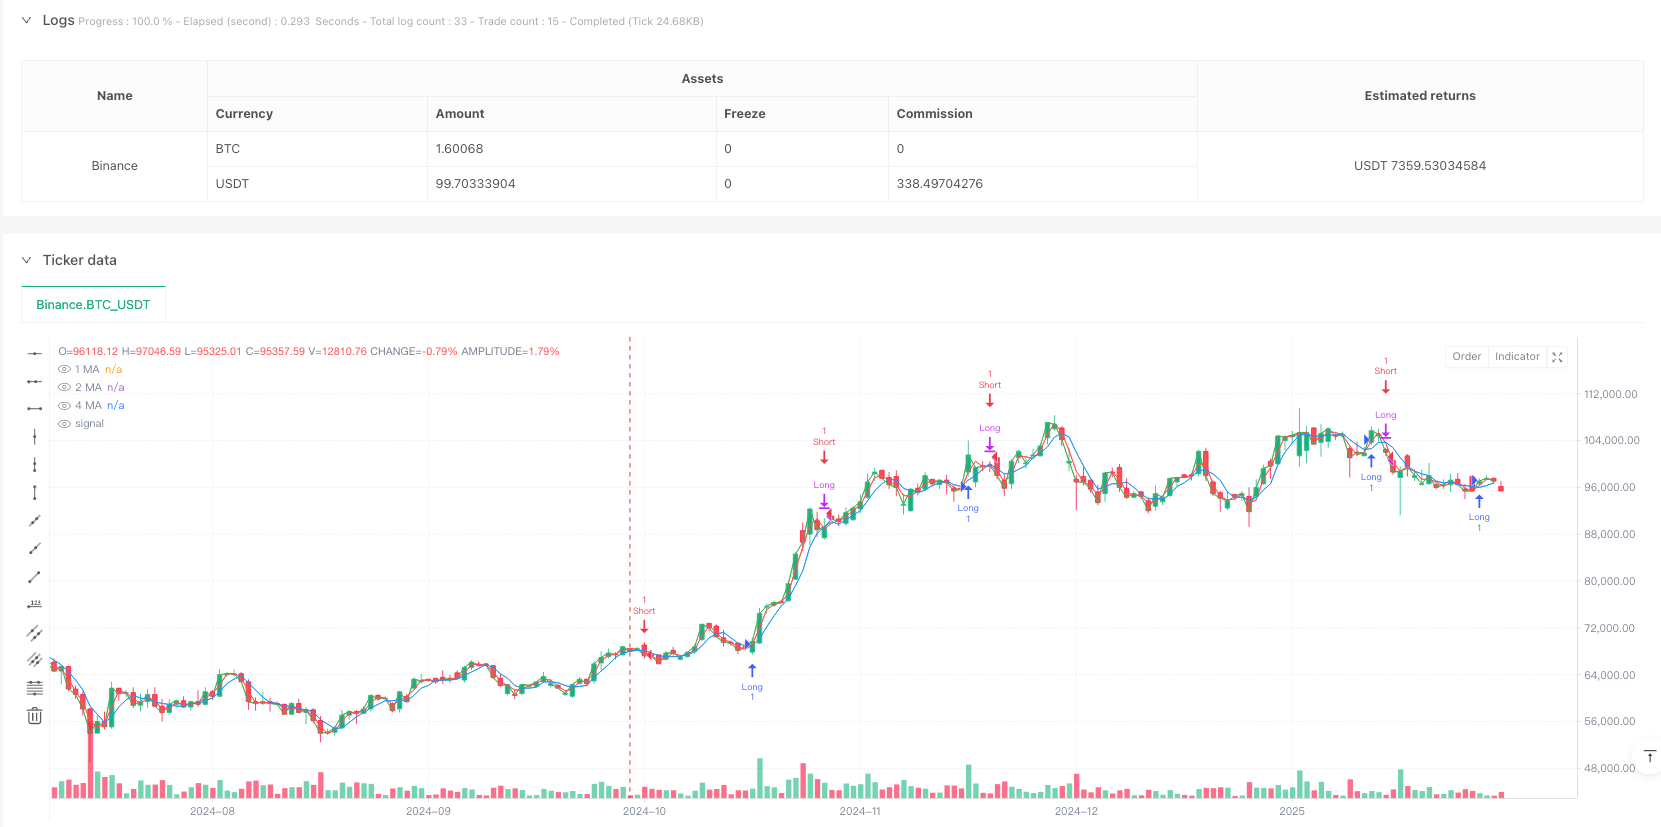
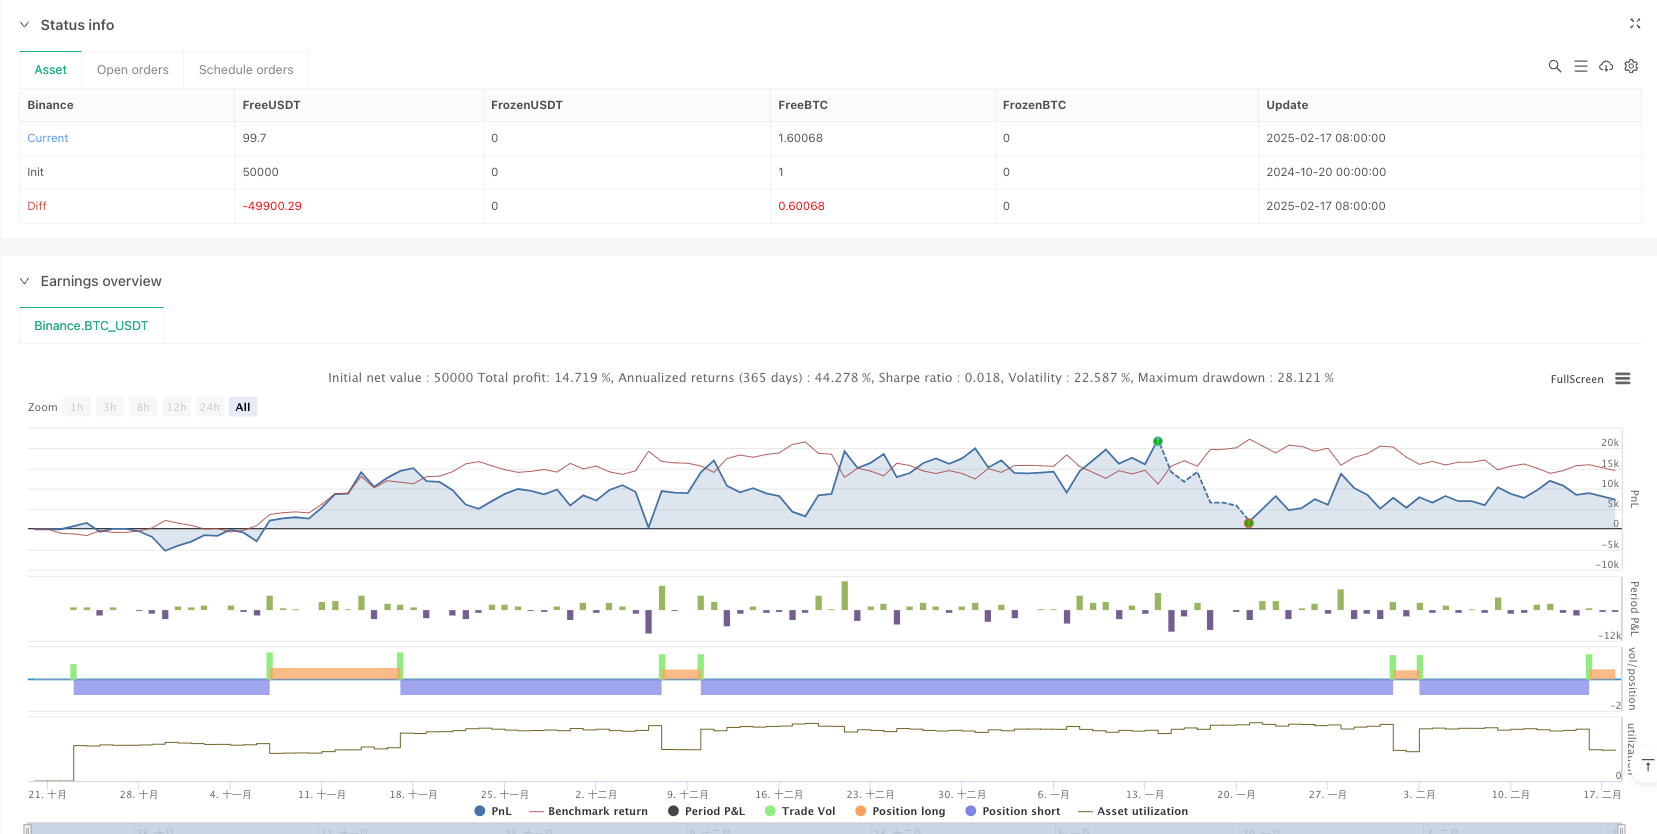
Overview
This strategy is a trading system based on the crossing signals of 1/2/4-period Simple Moving Averages (SMA). It captures market trend reversal points by observing the simultaneous crossing of short-period and medium-period moving averages over the long-period moving average, achieving trend following and timely stop-loss. The strategy design is concise, efficient, and easy to understand and implement.
Strategy Principle
The core of the strategy utilizes three SMAs of different periods (1/2/4), determining buy signals when both short-period (1-period) and medium-period (2-period) moving averages simultaneously cross above the long-period (4-period) moving average. Conversely, sell signals are generated when both shorter moving averages cross below the longer one. This multiple confirmation mechanism effectively reduces false signals and improves trading accuracy. In implementation, ta.crossover() and ta.crossunder() functions are used to detect crossovers, initiating long positions when buy conditions are met and short positions when sell conditions are satisfied.
Strategy Advantages
- Robust signal confirmation mechanism: requiring simultaneous crossing of two moving averages significantly reduces false signals
- Simple calculation logic: uses only simple moving averages, minimal computational load, high execution efficiency
- Flexible parameter settings: moving average periods can be adjusted according to different market characteristics
- Bi-directional trading: supports both long and short positions, fully capturing market opportunities
- Clear stop-loss mechanism: exits positions on reverse signals, providing explicit risk control
Strategy Risks
- Choppy market risk: may generate frequent false breakout signals in sideways markets
- Lag risk: moving averages have inherent lag, potentially missing optimal entry points
- Gap risk: price gaps may lead to suboptimal stop-loss execution
- Parameter sensitivity: different period combinations can yield significantly different results, requiring thorough testing
Strategy Optimization Directions
- Incorporate volume indicators: validate breakout effectiveness using volume changes
- Add trend filters: design trend identification modules to trade in the primary trend direction
- Optimize stop-loss mechanism: consider implementing trailing stops or volatility-based dynamic stops
- Enhance position management: dynamically adjust position sizes based on signal strength and market volatility
- Design signal confirmation: add price patterns and technical indicators as auxiliary confirmation mechanisms
Summary
This strategy captures market trends through multiple moving average crossovers, with clear design concepts and simple yet effective implementation. While it has certain lag and false signal risks, reasonable parameter optimization and supplementary indicators can build a more comprehensive trading system. The strategy offers strong extensibility and serves as an excellent foundation for further optimization and refinement.
Source Pine Script
/*backtest
start: 2024-10-20 00:00:00
end: 2025-02-18 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("1/2/4 Moving Average STR 1.0.0", overlay=true)


o_length = input(1, title="1 Closed")
t_length = input(2, title="2 Closed")
f_length = input(4, title="4 Closed")

// Calculate the simple moving averages.
ma_o = ta.sma(close, o_length)
ma_t = ta.sma(close, t_length)
ma_f = ta.sma(close, f_length)

// Plot the moving averages on the chart.
plot(ma_o, color=color.green, title="1 MA")
plot(ma_t, color=color.red, title="2 MA")
plot(ma_f, color=color.blue, title="4 MA")

// Assign the crossover and crossunder results to global variables.
crossover_o = ta.crossover(ma_o, ma_f)
crossover_t = ta.crossover(ma_t, ma_f)
crossunder_o = ta.crossunder(ma_o, ma_f)
crossunder_t = ta.crossunder(ma_t, ma_f)

// Generate signals based on the global crossover variables.
// Buy signal: both 1 and 2 SMAs cross over the 4 SMA on the same bar.
buy_signal = crossover_o and crossover_t
// Sell signal: both 1 and 2 SMAs cross under the 4 SMA on the same bar.
sell_signal = crossunder_o and crossunder_t

// Enter trades based on the signals.
// For a long position, enter on a buy signal and exit when a sell signal occurs.
if buy_signal
    strategy.entry("Long", strategy.long)
if sell_signal
    strategy.close("Long")

// For a short position, enter on a sell signal and exit when a buy signal occurs.
if sell_signal
    strategy.entry("Short", strategy.short)
if buy_signal
    strategy.close("Short")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multiple-Moving-Average-Crossover-Trend-Capture-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m