MyLanguage Turtle Strategy Experience
Quick start Based on the powerful lower layer of the inventor, it fully supports digital currency spot futures and domestic commodity futures. Automatic position rollover, truly reflecting the main contract switching…
Quick start
- Based on the powerful lower layer of the inventor, it fully supports digital currency spot futures and domestic commodity futures.
- Automatic position rollover, truly reflecting the main contract switching process
- APIDocumentation https://www.fmz.com/bbs-topic/2569
Language Enhancement
The inventor Quantified not only implemented the interpreter of the Mai language, but also enhanced it to enable mixed programming with the high-level language Javascript. Here is an example
%%
// Here you can call any of the inventor's quantifiedAPI
scope.TEST = function(obj) {
    return obj.val * 100;
}
%%
Closing price:C;
Closing price multiplied by 100:TEST(C);
Magnify the previous closing price 100 times: TEST(REF(C, 1)); // Move the mouse to the candlestick of the backtest and the variable value will be prompted
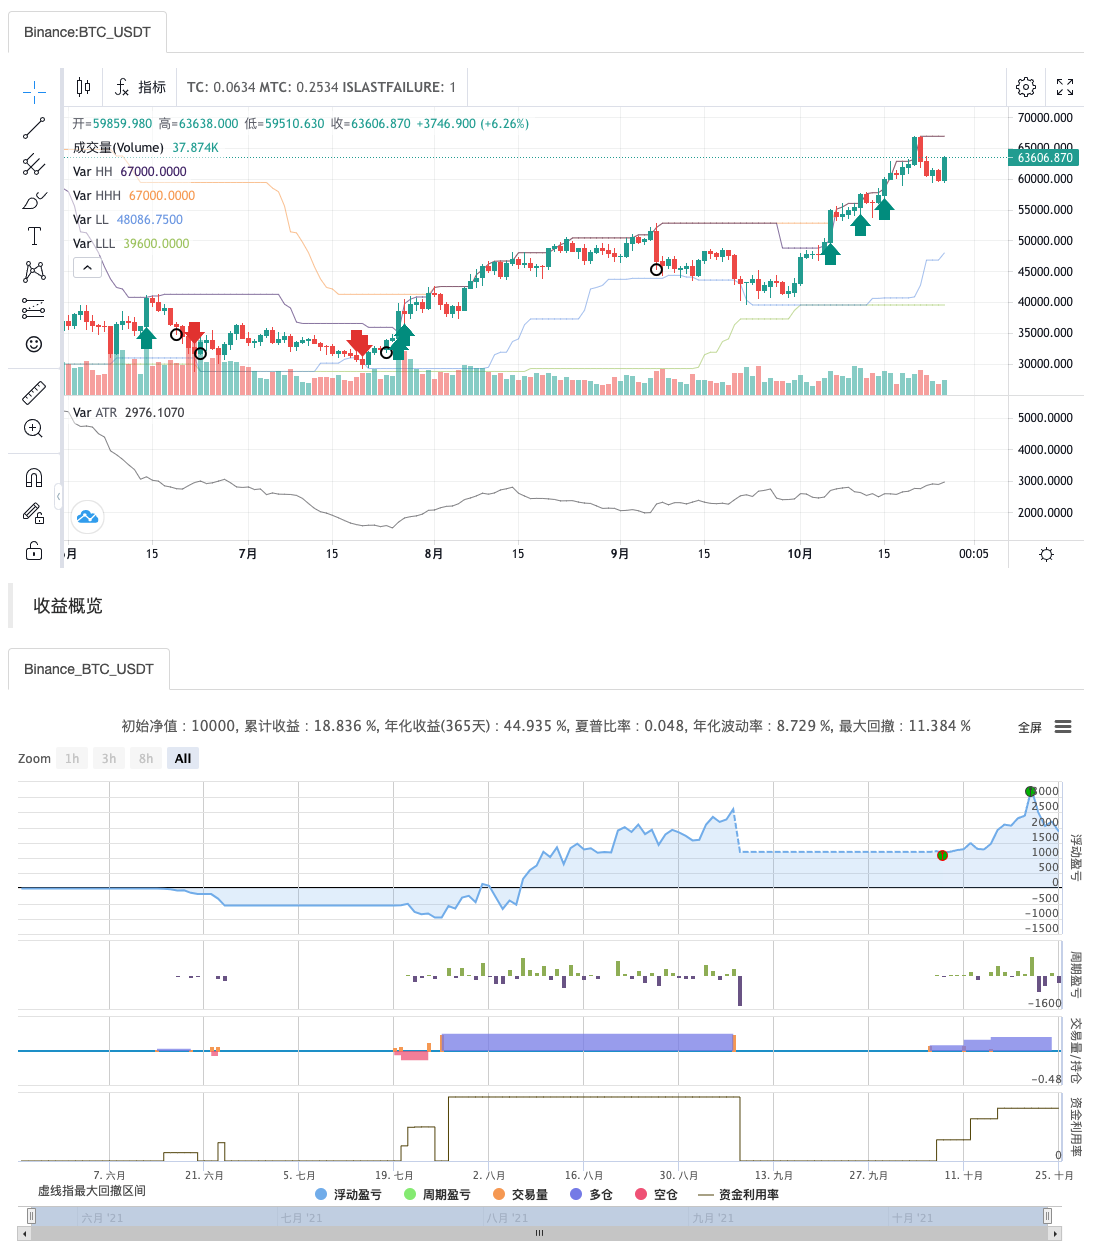
Parameters
| Name | Default | What it controls |
|---|---|---|
| RATIO | 0.01 | Funding Ratio |
Source MyLanguage
(*backtest
start: 2020-10-26 00:00:00
end: 2021-10-25 23:59:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Binance","currency":"BTC_USDT"}]
*)

//This demonstration mainly uses the Turtle Trading Rules to demonstrate"Position calculation, maximum position control, and other fund management"Compilation Method of
//In writing demonstrations, only key sentences are annotated; other sentences should be translated by yourself, or customer service may be consulted
//This model is for demonstration purposes only. Enter the market based on this at your own risk.
ATRPERIOD:=20; // ATRFluctuation cycle
SHORTPERIOD:=20; // Short-term Market Entry
LONGPERIOD:= 55; // Long-term Market Entry
VARIABLE:ISLASTFAILURE:=1; // Whether to stop loss and leave the market last time, global variables filter signals
TR:=MAX(MAX((HIGH-LOW),ABS(REF(CLOSE,1)-HIGH)),ABS(REF(CLOSE,1)-LOW));//True amplitude
ATR:MA(TR,ATRPERIOD); //Calculate the simple moving average of the true range over 20 periods, displayed in the attached chart
ZOOM:=IFELSE(ISCONTRACT('@Futures_(?!CTP).*'), CLOSE, 1); // Use digital currency futures as margin
LOT:=((MONEYTOT*RATIO*ZOOM)/(UNIT*ATR))*ZOOM;//Calculate the order quantity based on 1% of equity
TC..IFELSE(ISCONTRACT('@Futures.*'), INTPART(LOT), LOT); // Compatible with futures and spot. ISCONTRACT starting with @ indicates matching the exchange name, supports regex
MTC..4*TC; //Total Position
HH^^HV(H,SHORTPERIOD); // Attached to the main image display
LL^^LV(L,SHORTPERIOD);
HHH^^HV(H,LONGPERIOD);
LLL^^LV(L,LONGPERIOD);
ISEMPTY:=ISLASTBK=0&&ISLASTSK=0;
CROSSUP(C,HH)&&ISEMPTY&&ISLASTFAILURE,BK(TC);//If the latest price exceeds the highest value of the short period, buy to open for the first time, lots set to TC lots
CROSSDOWN(C,LL)&&ISEMPTY&&ISLASTFAILURE,SK(TC); //If the latest price falls below the lowest value of the short period, sell to open for the first time, lots set to TC lots
CROSSUP(C,HHH)&&ISEMPTY,BK(TC);//If the latest price exceeds the highest value of the long period, buy to open for the first time, lots set to TC lots
CROSSDOWN(C,LLL)&&ISEMPTY,SK(TC); //If the latest price falls below the lowest value of the long period, sell to open for the first time, lots set to TC lots
C>=BKPRICE+0.5*ATR&&BKVOL<MTC&&ISLASTBK,BK(TC);//The price increases by 0.5 times ATR based on the last position opened. When the lot size does not exceed 4 times TC, buy and add TC lots.
C<=SKPRICE-0.5*ATR&&SKVOL<MTC&&ISLASTSK,SK(TC);//The price drops by 0.5 times ATR based on the last position opened. When the lot size does not exceed 4 times TC, sell and add TC lots.
NEEDSTOP:=(C<=(BKPRICE-2*ATR)&&BKVOL>0) OR (C>=(SKPRICE+2*ATR)&&SKVOL>0);
NEEDLEAVE:=(CROSSUP(H,HV(H,10))&&SKVOL>0) OR (CROSSDOWN(L,LV(L,10))&&BKVOL>0);
NEEDSTOP OR NEEDLEAVE,CLOSEOUT;
ISLASTFAILURE..IF(NEEDSTOP OR NEEDLEAVE, NEEDSTOP, ISLASTFAILURE);
INFO(NEEDSTOP, 'Stop Loss Exit');
INFO(NEEDLEAVE, 'Successfully exited');
TRADE_AGAIN(10);
MULTSIG(1, 1, 10);
Published by Zero on the FMZ strategy square · last modified 2021-10-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MyLanguage-Turtle-Strategy-Experience.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- M Language Turtle Trading strategy implementationsV 10MyLanguage · Breakout
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Bull Flag Breakout StrategyPine Script · Breakout · 1h
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h