Strategy vault / Multi-timeframe
MZ MA Cross Multiple TimeFrame Strategy
This strategy mainly uses MA line crossovers across multiple timeframes to determine trend direction, and trades long or short when the trend is clear after filtering signals with specific criteria. It belongs to the…
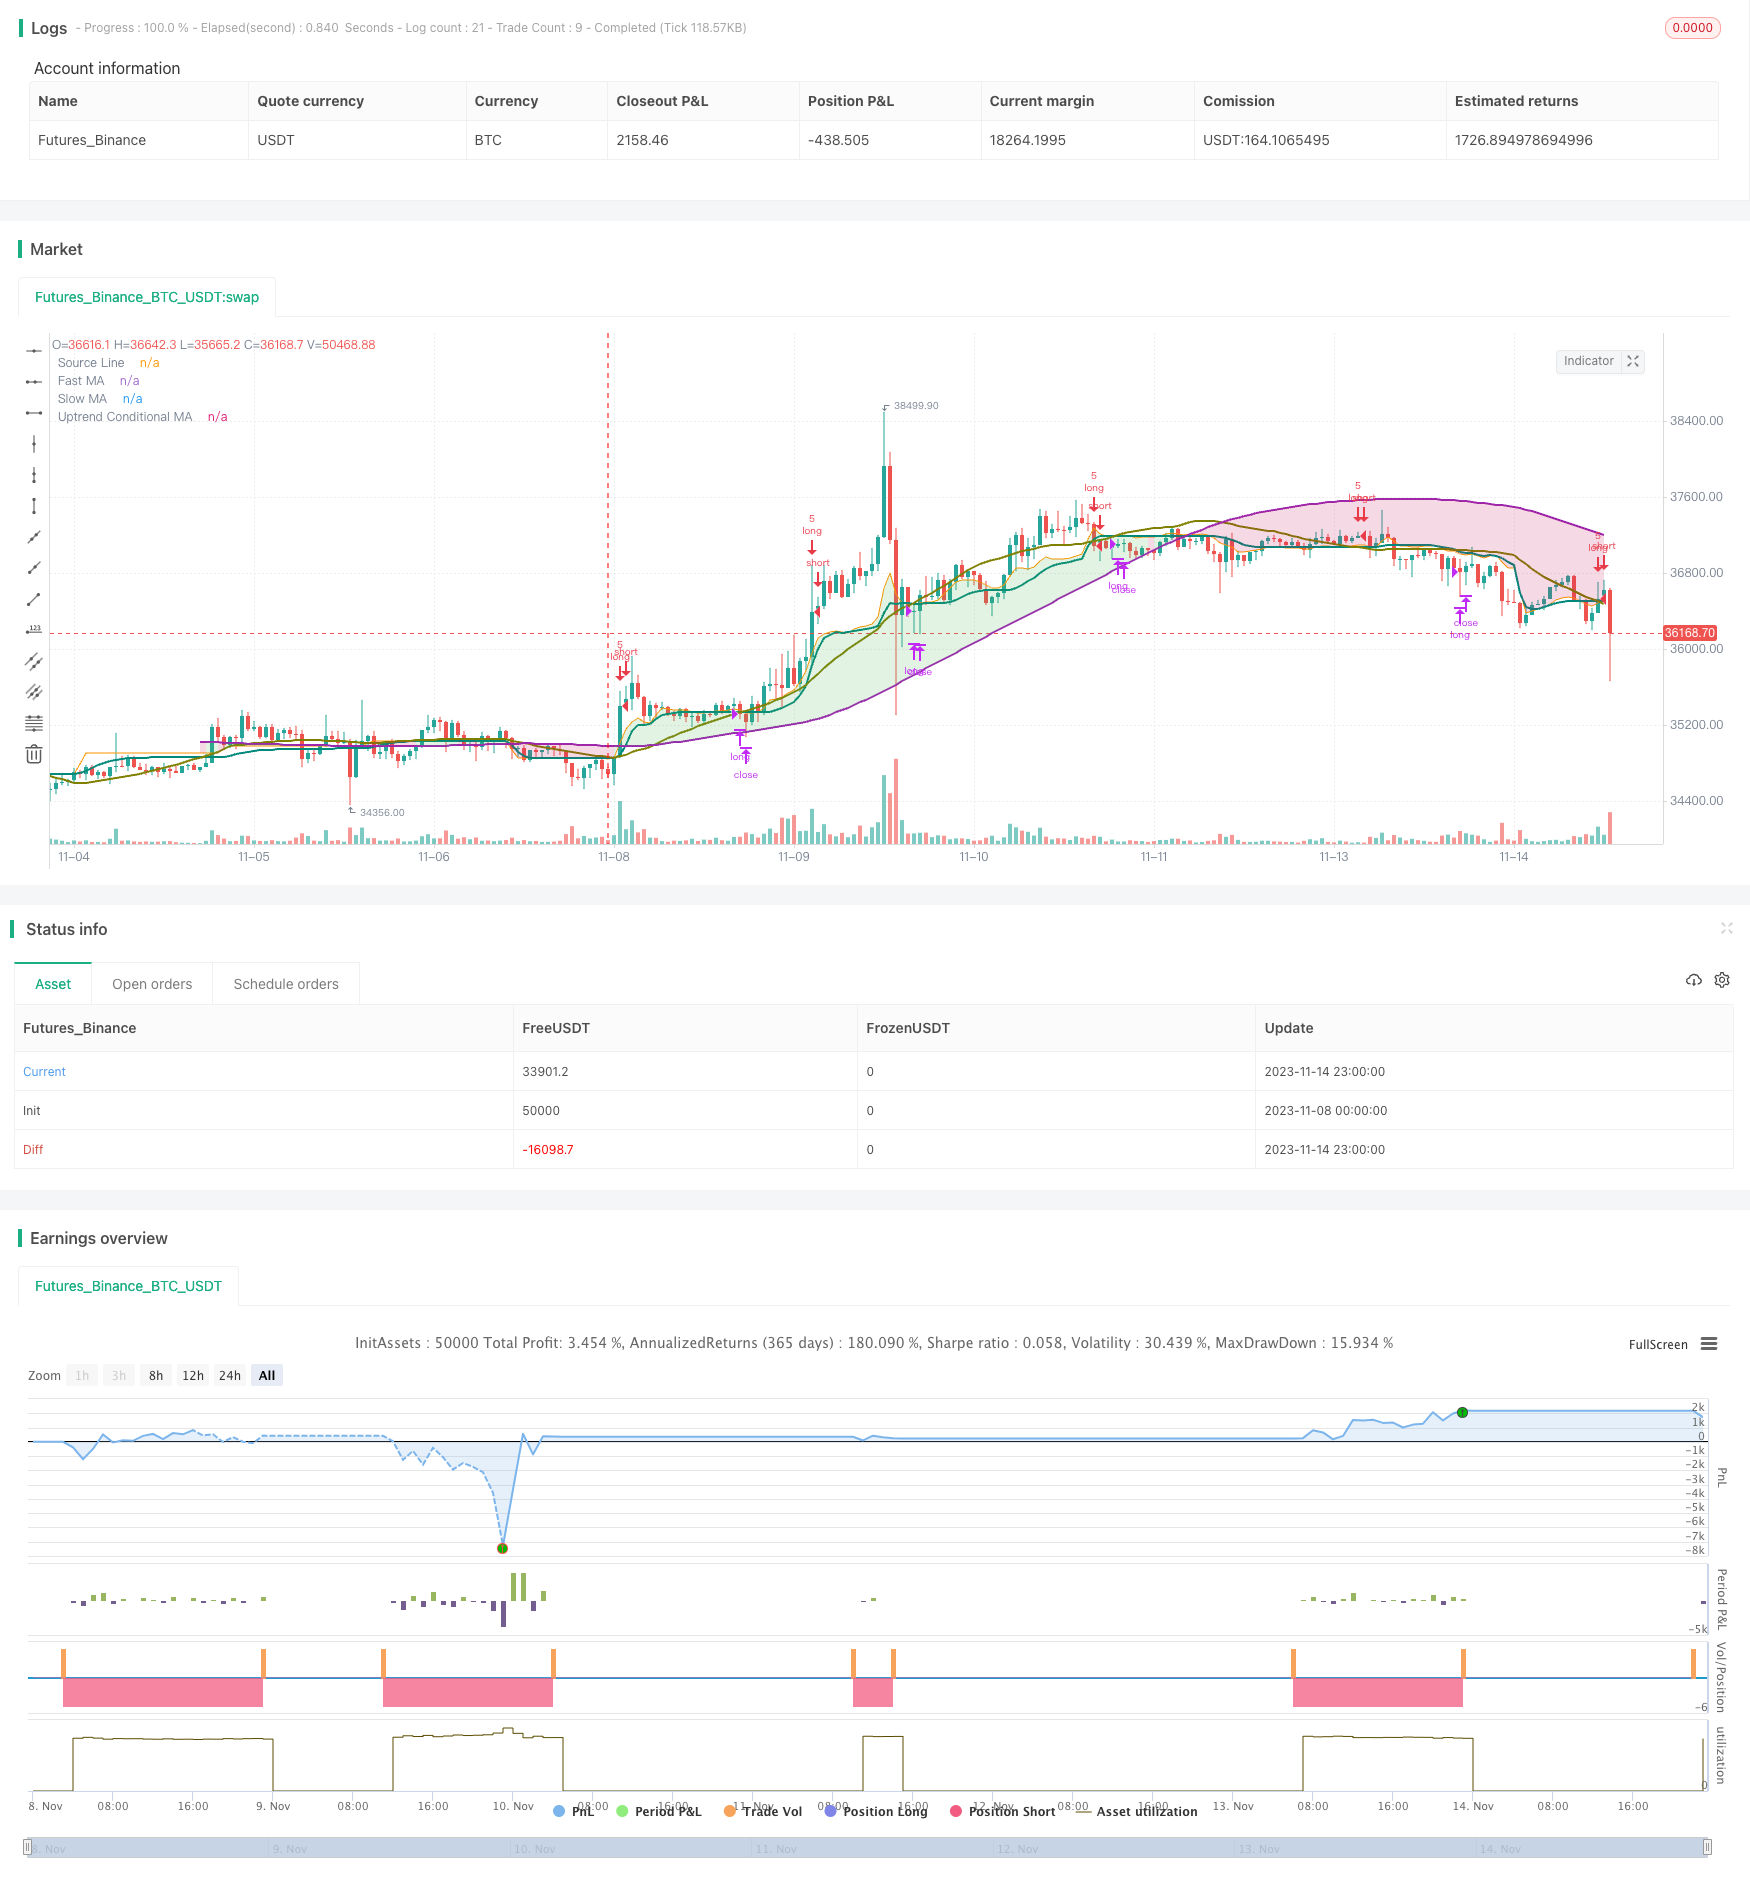
This strategy mainly uses MA line crossovers across multiple timeframes to determine trend direction, and trades long or short when the trend is clear after filtering signals with specific criteria. It belongs to the trend following strategy category.
Strategy Logic
User inputs custom backtest time range.
Choose to use Heikin-Ashi candles or normal candles.
Define slow, fast and optional third MA line for uptrends.
Customize MA type, timeframe and parameters for each MA line.
Long signal when fast MA crosses above slow MA, short signal when crossing below.
Optional to only long when close is above the third MA line.
Use strategy.entry for automated trading.
Fixed trade size or calculate based on account percentage.
Advantages
Uses MTF structure, each MA has own timeframe to identify trends across timescales.
Customizable MA types, can use Smooth MAs for stability or Fast MAs for responsiveness.
Heikin-Ashi filters false breakouts.
Optional third MA line filters whipsaws.
Flexible MA periods suit different market environments.
strategy.entry module automates trading.
Backtest optimization finds best parameters.
Risks
MA crosses prone to false signals, causing unnecessary trades. Can optimize periods or add filters.
Whipsaws cause losses in choppy markets. Can widen MA spacing or lengthen periods.
Fixed trade size doesn't control risk. Consider percentage of account size.
Fees and slippage also impact profitability. Ensure high enough win rate.
Optimization
Test different MA types for best combinations of stability and responsiveness.
Optimize MA periods to balance trend identification and sensitivity.
Refine entry conditions, consider stronger uptrend filters.
Optimize periods for specific products.
Add other indicators as filters, e.g. volume.
Parameter optimization on backtest data to maximize performance.
Conclusion
The MTF MA crossover strategy is a common trend following system. Benefits include simplicity, flexibility and adaptability. But false signals remain a risk. Parameters and filters can be optimized via backtesting to find best combinations. More suitable for trending markets. Use cautiously or stop trading during choppy conditions. As a traditional trend following technique, MTF MA crossovers are still worth dedicated research and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | D | Chart Timeframe |
| v_input_2 | true | Use Heikin Ashi Candles |
| v_input_3 | true | From Month |
| v_input_4 | true | From Day |
| v_input_5 | 2021 | From Year |
| v_input_6 | 12 | Thru Month |
| v_input_7 | 30 | Thru Day |
| v_input_8 | 2021 | Thru Year |
| v_input_9 | true | Show Date Range |
| v_input_10 | 0 | Slow MA Type: LRC | EMA | DEMA | TEMA | SMA | WMA | MF | VAMA | TMA | HMA | JMA | Kijun v2 | EDSMA | McGinley |
| v_input_11 | 0 | Fast MA Type: EDSMA | EMA | DEMA | TEMA | LRC | WMA | MF | VAMA | TMA | HMA | JMA | Kijun v2 | SMA | McGinley |
| v_input_12 | false | Use Uptrend Conditional 3rd MA for Confirmation |
| v_input_13 | 0 | Uptrend Conditional MA Type: HMA | EMA | DEMA | TEMA | LRC | WMA | MF | VAMA | TMA | SMA | JMA | Kijun v2 | EDSMA | McGinley |
| v_input_14 | D | Slow MA Resolution |
| v_input_15 | D | Fast MA Resolution |
| v_input_16 | D | Uptrend Conditional MA Resolution |
| v_input_17 | 50 | Slow MA Length |
| v_input_18 | 30 | Fast MA Length |
| v_input_19 | 200 | Uptrend Conditional MA Length |
| v_input_20 | true | Kijun MOD Divider |
| v_input_21 | 3 | * Jurik (JMA) Only - Phase |
| v_input_22 | true | * Jurik (JMA) Only - Power |
| v_input_23 | 10 | * Volatility Adjusted (VAMA) Only - Volatility lookback length |
| v_input_24 | 0.8 | Modular Filter, General Filter Only - Beta |
| v_input_25 | false | Modular Filter Only - Feedback |
| v_input_26 | 0.5 | Modular Filter Only - Feedback Weighting |
| v_input_27 | 20 | EDSMA - Super Smoother Filter Length |
| v_input_28 | 0 | EDSMA - Super Smoother Filter Poles: 2 | 3 |
Source Pine Script
/*backtest
start: 2023-11-08 00:00:00
end: 2023-11-15 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(shorttitle="MZ MA Cross",title="MA MTF Cross Strategy", overlay=true, calc_on_order_fills=false, calc_on_every_tick=false, default_qty_type=strategy.fixed, default_qty_value=5,commission_value=0.1)

timeFrameticker  = input('D',type=input.resolution, title="Chart Timeframe")
uha   =input(true, title="Use Heikin Ashi Candles")

// Use only Heikinashi Candles for all calculations
haclose = uha ? security(heikinashi(syminfo.tickerid), timeFrameticker, close) : security(syminfo.tickerid, timeFrameticker, close)
haopen = uha ? security(heikinashi(syminfo.tickerid), timeFrameticker, open) : security(syminfo.tickerid, timeFrameticker, open)
hahigh = uha ? security(heikinashi(syminfo.tickerid), timeFrameticker, high) : security(syminfo.tickerid, timeFrameticker, high)
halow = uha ?security(heikinashi(syminfo.tickerid), timeFrameticker, low) : security(syminfo.tickerid, timeFrameticker, low)

//Backtest dates
fromMonth = input(defval = 1,    title = "From Month",      type = input.integer, minval = 1, maxval = 12)
fromDay   = input(defval = 1,    title = "From Day",        type = input.integer, minval = 1, maxval = 31)
fromYear  = input(defval = 2021, title = "From Year",       type = input.integer, minval = 1970)
thruMonth = input(defval = 12,    title = "Thru Month",      type = input.integer, minval = 1, maxval = 12)
thruDay   = input(defval = 30,    title = "Thru Day",        type = input.integer, minval = 1, maxval = 31)
thruYear  = input(defval = 2021, title = "Thru Year",       type = input.integer, minval = 1970)

showDate  = input(defval = true, title = "Show Date Range", type = input.bool)

start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)        // backtest start window
finish    = timestamp(thruYear, thruMonth, thruDay, 23, 59)        // backtest finish window
window()  => true

src = security(heikinashi(syminfo.tickerid), timeFrameticker, close)

//  INPUT MA TYPE
slowMAtype = input(title="Slow MA Type", type=input.string, defval="LRC", options=["SMA","EMA","DEMA","TEMA","LRC","WMA","MF","VAMA","TMA","HMA", "JMA", "Kijun v2", "EDSMA","McGinley"])
fastMAtype = input(title="Fast MA Type", type=input.string, defval="EDSMA", options=["SMA","EMA","DEMA","TEMA","LRC","WMA","MF","VAMA","TMA","HMA", "JMA", "Kijun v2", "EDSMA","McGinley"])
upMAcond =input(false, title="Use Uptrend Conditional 3rd MA for Confirmation")
upMAtype=input(title="Uptrend Conditional MA Type", type=input.string, defval="HMA", options=["SMA","EMA","DEMA","TEMA","LRC","WMA","MF","VAMA","TMA","HMA", "JMA", "Kijun v2", "EDSMA","McGinley"])


//  INPUT RESOLUTION
slowMAresolution = input("D",type=input.resolution, title="Slow MA Resolution")
fastMAresolution = input("D",type=input.resolution, title="Fast MA Resolution")
upMAresolution = input("D",type=input.resolution, title="Uptrend Conditional MA Resolution")
haMAslow = uha ? security(heikinashi(syminfo.tickerid), slowMAresolution, close) : security(syminfo.tickerid, slowMAresolution, close)
haMAfast = uha ?security(heikinashi(syminfo.tickerid), fastMAresolution, close) : security(syminfo.tickerid, fastMAresolution, close)
haMAup =  uha ?security(heikinashi(syminfo.tickerid), upMAresolution, close) : security(syminfo.tickerid, upMAresolution, close)

//  INPUT LENGTHS
slowMAlength = input(50, minval=1, title="Slow MA Length")
fastMAlength = input(30, minval=1, title="Fast MA Length")
upMAlength =  input(200, minval=1, title="Uptrend Conditional MA Length")

/////////////////////////////////////////////////////////////////////
/////////////////////////////////////////////////////////////////////
/////                      MA Function                         //////
/////////////////////////////////////////////////////////////////////
/////////////////////////////////////////////////////////////////////

//           Pre-reqs
//
tema(src, len) =>
    ema1 = ema(src, len)
    ema2 = ema(ema1, len)
    ema3 = ema(ema2, len)
    (3 * ema1) - (3 * ema2) + ema3
kidiv = input(defval=1,maxval=4,  title="Kijun MOD Divider")

jurik_phase = input(title="* Jurik (JMA) Only - Phase", type=input.integer, defval=3)
jurik_power = input(title="* Jurik (JMA) Only - Power", type=input.integer, defval=1)
volatility_lookback = input(10, title="* Volatility Adjusted (VAMA) Only - Volatility lookback length")
//                  MF
beta = input(0.8,minval=0,maxval=1,step=0.1,  title="Modular Filter, General Filter Only - Beta")
feedback = input(false, title="Modular Filter Only - Feedback")
z = input(0.5,title="Modular Filter Only - Feedback Weighting",step=0.1, minval=0, maxval=1)
//EDSMA
ssfLength = input(title="EDSMA - Super Smoother Filter Length", type=input.integer, minval=1, defval=20)
ssfPoles = input(title="EDSMA - Super Smoother Filter Poles", type=input.integer, defval=2, options=[2, 3])

//----
//                  EDSMA
get2PoleSSF(src, length) =>
    PI = 2 * asin(1)
    arg = sqrt(2) * PI / length
    a1 = exp(-arg)
    b1 = 2 * a1 * cos(arg)
    c2 = b1
    c3 = -pow(a1, 2)
    c1 = 1 - c2 - c3

    ssf = 0.0
    ssf := c1 * src + c2 * nz(ssf[1]) + c3 * nz(ssf[2])

get3PoleSSF(src, length) =>
    PI = 2 * asin(1)

    arg = PI / length
    a1 = exp(-arg)
    b1 = 2 * a1 * cos(1.738 * arg)
    c1 = pow(a1, 2)

    coef2 = b1 + c1
    coef3 = -(c1 + b1 * c1)
    coef4 = pow(c1, 2)
    coef1 = 1 - coef2 - coef3 - coef4

    ssf = 0.0
    ssf := coef1 * src + coef2 * nz(ssf[1]) + coef3 * nz(ssf[2]) + coef4 * nz(ssf[3])

//          MA Main function
ma(type, src, len) =>
    float result = 0
    if type=="TMA"
        result := sma(sma(src, ceil(len / 2)), floor(len / 2) + 1)
    if type=="MF"
        ts=0.,b=0.,c=0.,os=0.
        //----
        alpha = 2/(len+1)
        a = feedback ? z*src + (1-z)*nz(ts[1],src) : src
        //----
        b := a > alpha*a+(1-alpha)*nz(b[1],a) ? a : alpha*a+(1-alpha)*nz(b[1],a)
        c := a < alpha*a+(1-alpha)*nz(c[1],a) ? a : alpha*a+(1-alpha)*nz(c[1],a)
        os := a == b ? 1 : a == c ? 0 : os[1]
        //----
        upper = beta*b+(1-beta)*c
        lower = beta*c+(1-beta)*b
        ts := os*upper+(1-os)*lower
        result := ts
    if type=="LRC"
        result := linreg(src, len, 0)
    if type=="SMA" // Simple
        result := sma(src, len)
    if type=="EMA" // Exponential
        result := ema(src, len)
    if type=="DEMA" // Double Exponential
        e = ema(src, len)
        result := 2 * e - ema(e, len)
    if type=="TEMA" // Triple Exponential
        e = ema(src, len)
        result := 3 * (e - ema(e, len)) + ema(ema(e, len), len)
    if type=="WMA" // Weighted
        result := wma(src, len)
    if type=="VAMA" // Volatility Adjusted
        /// Copyright © 2019 to present, Joris Duyck (JD)
        mid=ema(src,len)
        dev=src-mid
        vol_up=highest(dev,volatility_lookback)
        vol_down=lowest(dev,volatility_lookback)
        result := mid+avg(vol_up,vol_down)
    if type=="HMA" // Hull
        result := wma(2 * wma(src, len / 2) - wma(src, len), round(sqrt(len)))
    if type=="JMA" // Jurik
        /// Copyright © 2018 Alex Orekhov (everget)
        /// Copyright © 2017 Jurik Research and Consulting.
        phaseRatio = jurik_phase < -100 ? 0.5 : jurik_phase > 100 ? 2.5 : jurik_phase / 100 + 1.5
        beta = 0.45 * (len - 1) / (0.45 * (len - 1) + 2)
        alpha = pow(beta, jurik_power)
        jma = 0.0
        e0 = 0.0
        e0 := (1 - alpha) * src + alpha * nz(e0[1])
        e1 = 0.0
        e1 := (src - e0) * (1 - beta) + beta * nz(e1[1])
        e2 = 0.0
        e2 := (e0 + phaseRatio * e1 - nz(jma[1])) * pow(1 - alpha, 2) + pow(alpha, 2) * nz(e2[1])
        jma := e2 + nz(jma[1])
        result := jma
    if type=="Kijun v2"
        kijun = avg(lowest(len), highest(len))//, (open + close)/2)
        conversionLine = avg(lowest(len/kidiv), highest(len/kidiv))
        delta = (kijun + conversionLine)/2
        result :=delta
    if type=="McGinley"
        mg = 0.0
        mg := na(mg[1]) ? ema(src, len) : mg[1] + (src - mg[1]) / (len * pow(src/mg[1], 4))
        result :=mg
    if type=="EDSMA"

        zeros = src - nz(src[2])
        avgZeros = (zeros + zeros[1]) / 2

        // Ehlers Super Smoother Filter
        ssf = ssfPoles == 2
             ? get2PoleSSF(avgZeros, ssfLength)
             : get3PoleSSF(avgZeros, ssfLength)

        // Rescale filter in terms of Standard Deviations
        stdev = stdev(ssf, len)
        scaledFilter = stdev != 0
             ? ssf / stdev
             : 0

        alpha = 5 * abs(scaledFilter) / len

        edsma = 0.0
        edsma := alpha * src + (1 - alpha) * nz(edsma[1])
        result :=  edsma
    result
/////////////////////////////////////////////////////////////////////
/////////////////////////////////////////////////////////////////////


//  MA DEFINITION
slowMA = ma(slowMAtype, haMAslow , slowMAlength)
//fastMA = ma(fastMAtype, slowMA , fastMAlength)
fastMA = ma(fastMAtype, haMAfast , fastMAlength)
upMA = ma(upMAtype, haMAup , upMAlength)
closeMA = ma('SMA', src , 2)

//  Strategy Conditions
L1 = crossover(fastMA,slowMA)
L2 = close > upMA
S1 = crossunder(fastMA,slowMA)
S2 = close < upMA
longcondition = upMAcond ? L1 and L2 : L1
shortcondition = upMAcond ? S1 or S2 : S1

//  Plots
color_fill_uptrend = color.new(#4caf50, 80)
color_fill_downtrend = color.new(#c2185b, 80)
plot(slowMA, title='Slow MA', color=color.olive, linewidth=2)
plot(fastMA, title='Fast MA', color=color.teal, linewidth=2)
cls=plot(closeMA, title='Source Line', color=na, linewidth=1)
up = plot(upMA, title='Uptrend Conditional MA', color=color.purple, linewidth=2)
fill(up,cls, color = close > upMA ? color_fill_uptrend : color_fill_downtrend )

//plotshape(longcondition, style = shape.triangleup, color = color.green, location = location.belowbar, text = "Long", size = size.small)
//plotshape(shortcondition, style = shape.triangledown, color = color.red, location = location.abovebar, text = "Short", size = size.small)


strategy.entry(id="long", long = true, when = longcondition and window())
strategy.close("long", when = shortcondition and window())

//if (longcondition)
//    strategy.entry("BUY", strategy.long, when = window())

//if (shortcondition)
// strategy.entry("SELL", strategy.short, when = window())Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MZ-MA-Cross-Multiple-TimeFrame-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA RSI and MACD Based Multi Timeframe Trading StrategyPine Script · Multi-timeframe · 1h
- Low Pyramid Risk Tracking StrategyPine Script · Multi-timeframe · 1d
- MacD Custom Indicator Multiple Time FrameAll Available OptionsPine Script · Multi-timeframe · 1h
- Multi Timeframe Adaptive Dynamic KDJ Indicator StrategyPine Script · Multi-timeframe · 1d
- Multi Timeframe Dynamic Stop Loss EMA Squeeze Trading StrategyPine Script · Multi-timeframe · 1h
- Multi Timeframe Smart Money Concept Support and Resistance Dynamic Trading StrategyPine Script · Multi-timeframe · 2d