NMVOB S
backtest
backtest
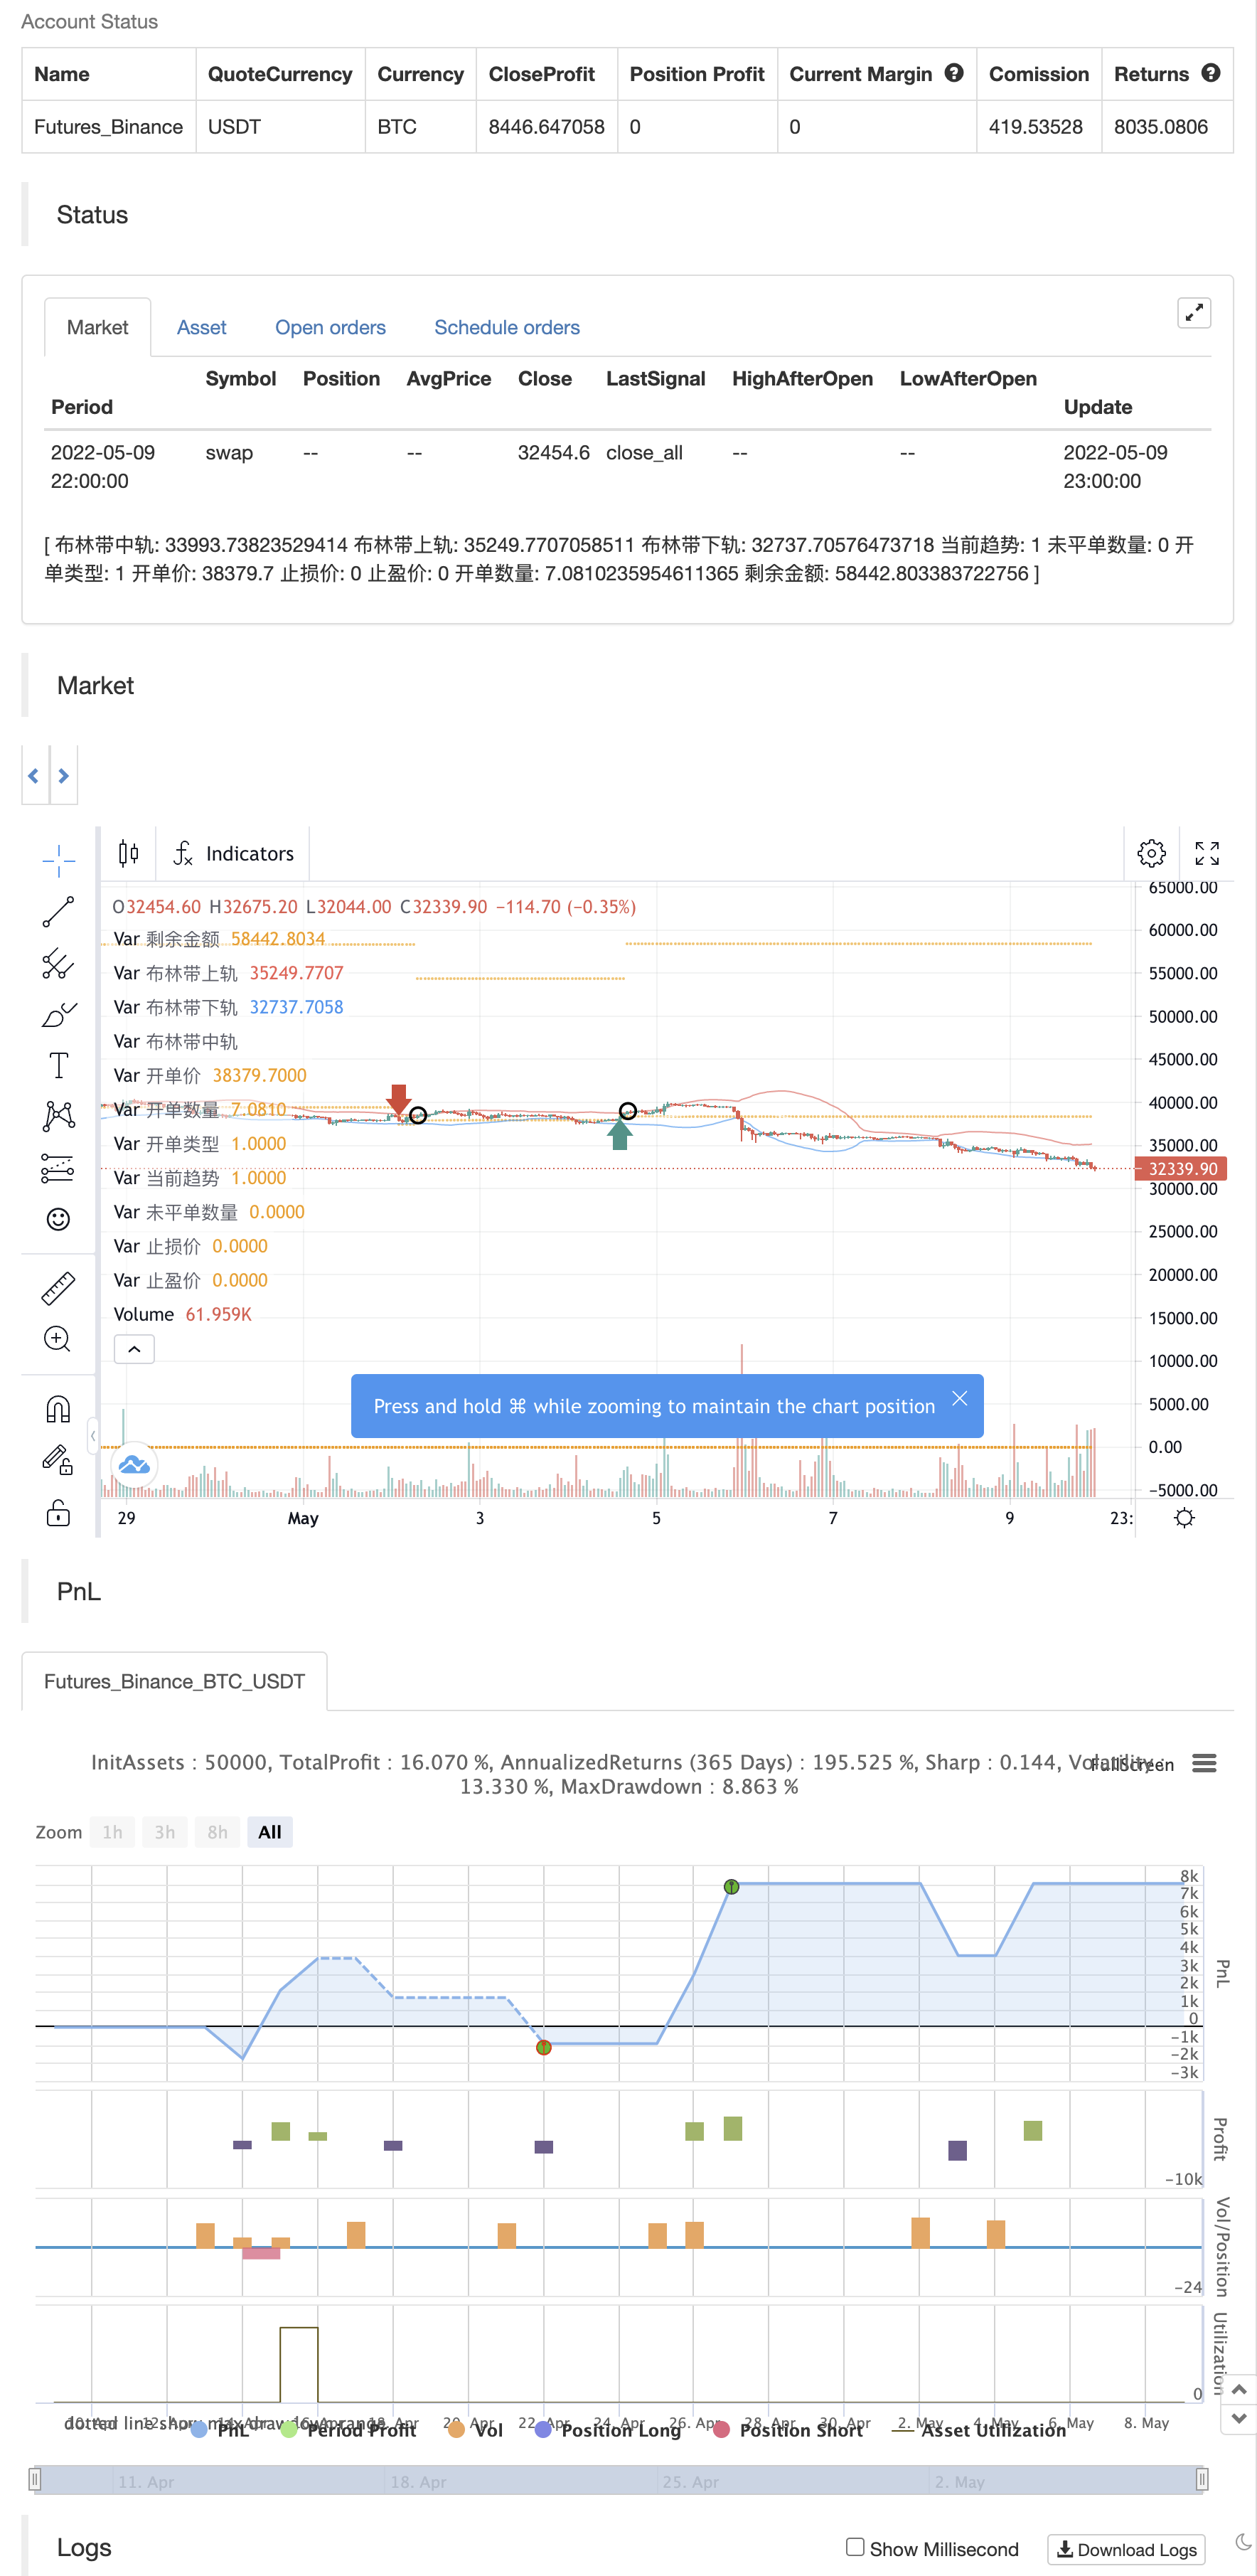
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | 50000 | Starting Capital |
| v_input_int_1 | 5 | leverage |
| v_input_1 | false | Number of Stop-Loss Bars |
| v_input_float_2 | true | Take Profit Ratio |
| v_input_2 | 13 | MACD Fast MA |
| v_input_3 | 21 | MACD Slow MA |
| v_input_4 | 9 | MACD Trigger |
| v_input_5 | 50 | MACD Normalize |
| v_input_int_2 | true | (MACD) 1=Ema, 2=Wma, 3=Sma |
| v_input_6 | 100 | VS timeframe |
| v_input_int_3 | 34 | Bollinger Bands Period |
| v_input_7_close | 0 | Boollinger Bands Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_float_3 | 2 | StdDev |
Source Pine Script
/*backtest
start: 2022-04-10 00:00:00
end: 2022-05-09 23:59:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5

// # ========================================================================= #
// #                   |   STRATEGY  |
// # ========================================================================= #
strategy(title = "NMVOB-S", shorttitle = "NMVOB-S", overlay = true , calc_on_every_tick = false , initial_capital = 0)
// # ========================================================================= #
// #                   |  Global Variables START  |
// # ========================================================================= #
var current_trend = int(na)
var open_order_type = int(na)
var stop_loss_price = float(na)
var stop_profit_price = float(na)
var sl = float(na)
var open_order_price = float(na)
var open_type_flag = int(na)
var stop_profit_flag = 0

var macd_signal_position = 0
var macd_signal_type = int(na)

var start_price = input.float(50000, "Starting Capital")
var gg = input.int(5, "leverage")

// # ========================================================================= #
// #                   |  Global Variables END  |
// # ========================================================================= #

// # ========================================================================= #
// #                   |  Custom Function START  |
// # ========================================================================= #
stop_loss_pillars = input(defval = 0, title = "Number of Stop-Loss Bars")
stop_profit_proportion = input.float(1,"Take Profit Ratio")
//Calculate Stop-Loss Price
calculate_stop_loss() =>
    if current_trend == 1
        stop_loss_price_buy = low
        if stop_loss_pillars == 0
            stop_loss_price_buy
        else
            for i = 1 to stop_loss_pillars
                if low[i] < stop_loss_price_buy
                    stop_loss_price_buy := low[i]
                else if low[i] > stop_loss_price_buy
                    stop_loss_price_buy
            stop_loss_price_buy
    else
        stop_loss_price_sell = high
        if stop_loss_pillars == 0
            stop_loss_price_sell
        else
            for i = 1 to stop_loss_pillars
                if high[i] < stop_loss_price_sell
                    stop_loss_price_sell
                else if high[i] > stop_loss_price_sell
                    stop_loss_price_sell := high[i]
            stop_loss_price_sell

//Calculate Take Profit
calculate_stop_profit(cur_stop_loss_price) =>
    value = math.abs(close - cur_stop_loss_price) * stop_profit_proportion
    if current_trend == 1
        close + value
    else
        close - value

// # ========================================================================= #
// #                   |  Custom Function END  |
// # ========================================================================= #


// # ========================================================================= #
// #                   |   Normalized MACD  |
// # ========================================================================= #
sma = input(13,title='MACD Fast MA')
lma = input(21,title='MACD Slow MA')
tsp = input(9,title='MACD Trigger')
np = input(50,title='MACD Normalize')
type = input.int(1,minval=1,maxval=3,title="(MACD) 1=Ema, 2=Wma, 3=Sma")

sh = type == 1 ? ta.ema(close,sma)
 : type == 2 ? ta.wma(close, sma)
 : ta.sma(close, sma)

lon=type == 1 ? ta.ema(close,lma)
 : type == 2 ? ta.wma(close, lma)
 : ta.sma(close, lma)

ratio = math.min(sh,lon)/math.max(sh,lon)

Mac = if sh>lon
    2 - ratio - 1
else
    ratio - 1
//Fast line
MacNorm = ((Mac-ta.lowest(Mac, np)) /(ta.highest(Mac, np)-ta.lowest(Mac, np)+.000001)*2)- 1

MacNorm2 = if np < 2
    Mac
else
    MacNorm
//Slow line
Trigger = ta.wma(MacNorm2, tsp)

if ta.crossover(source1 = MacNorm, source2 = Trigger)
    macd_signal_position := 0
    macd_signal_type := 1
else if ta.crossunder(source1 = MacNorm, source2 = Trigger)
    macd_signal_position := 0
    macd_signal_type := 0
else
    macd_signal_position += 1

// # ========================================================================= #
// #                   |   Normalized MACD  |
// # ========================================================================= #


// # ========================================================================= #
// #                   |  Volatility Oscillator START  |
// # ========================================================================= #
length = input(100, title="VS timeframe")
spike = close - open
vs_up_line = ta.stdev(spike,length)
vs_low_line = ta.stdev(spike,length) * -1
// # ========================================================================= #
// #                   |  Volatility Oscillator END  |
// # ========================================================================= #


// # ========================================================================= #
// #                   |  Bollinger Bands  |
// # ========================================================================= #
b_length = input.int(34, minval=1 , title="Bollinger Bands Period")
src = input(close, title="Boollinger Bands Source")
mult = input.float(2.0, minval=0.001, maxval=50, title="StdDev")
basis = ta.sma(src, b_length)
dev = mult * ta.stdev(src, b_length)
upper = basis + dev
lower = basis - dev
offset = 0
plot(basis, "Bollinger Bands Middle Line", color=color.white, offset = offset)
plot(upper, "Bollinger Band is on track", color=color.red, offset = offset)
plot(lower, "Bollinger Bands are off track", color=color.blue, offset = offset)
// # ========================================================================= #
// #                   |  Bollinger Bands  |
// # ========================================================================= #

if true
    if strategy.opentrades == 0 and barstate.isnew
        //macdUp/Down Condition
        long_macd_conditions = macd_signal_type == 1 and macd_signal_position <= 10
        short_macd_conditions = macd_signal_type == 0 and macd_signal_position <= 10
        // Volatility Oscillator Up/Down Condition
        long_vs_conditions = ta.crossover(source1 = spike, source2 = vs_up_line)
        short_vs_conditions = ta.crossunder(source1 = spike, source2 = vs_low_line)
        //Bollinger Bands rise and fall conditions
        long_bollinger_conditions = low < basis and close > basis and high < upper
        short_bollinger_conditions = high > basis and close < basis and low > lower

        //Conditions for opening long orders
        open_long_order_conditions = long_macd_conditions and long_vs_conditions and long_bollinger_conditions
        //Conditions for opening short orders
        open_short_order_conditions = short_macd_conditions and short_vs_conditions and short_bollinger_conditions

        if open_long_order_conditions
            current_trend := 1
            stop_loss_price := calculate_stop_loss()
            stop_profit_price := calculate_stop_profit(stop_loss_price)
            open_order_type := 1
            sl := (start_price * gg) / close
            open_order_price := close
            open_type_flag := 1
            if sl > 0
                strategy.order(id = "long order", direction = strategy.long , qty = sl, limit = close, stop = stop_loss_price, comment = "Long position", when = open_long_order_conditions)
        else if open_short_order_conditions
            current_trend := 0
            stop_loss_price := calculate_stop_loss()
            stop_profit_price := calculate_stop_profit(stop_loss_price)
            open_order_type := 0
            sl := (start_price * gg) / close
            open_order_price := close
            open_type_flag := 0
            if sl > 0
                strategy.order(id = "short order", direction = strategy.short , qty = sl, limit = close, stop = stop_loss_price, comment = "Short position", when = open_short_order_conditions)

    else if strategy.opentrades == 1
        if open_order_type == 1
            if close <= stop_loss_price or close >= stop_profit_price
                stop_loss_price := float(na)
                stop_profit_price := float(na)
                lr = (close - open_order_price) * sl
                start_price := start_price + lr
                strategy.close_all(when = true, comment = "close long")

        if open_order_type == 0
            if close >= stop_loss_price or close <= stop_profit_price
                stop_loss_price := float(na)
                stop_profit_price := float(na)
                lr = (open_order_price - close) * sl
                start_price := start_price + lr
                strategy.close_all(when = true, comment = "close short")


plot(series = current_trend, title = "Current Trend", color = color.orange, style = plot.style_circles)
plot(series = strategy.opentrades, title = "Unclosed order quantity", color = color.orange, style = plot.style_circles)
plot(series = open_order_type, title = "Order Type", color = color.orange, style = plot.style_circles)
plot(series = open_order_price, title = "Opening price", color = color.orange, style = plot.style_circles)
plot(series = stop_loss_price, title = "Stop loss price", color = color.orange, style = plot.style_circles)
plot(series = stop_profit_price, title = "Take-profit price", color = color.orange, style = plot.style_circles)
plot(series = sl, title = "Order Quantity", color = color.orange, style = plot.style_circles)
plot(series = start_price, title = "Remaining Amount", color = color.orange, style = plot.style_circles)
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/NMVOB-S.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.