Strategy vault / Trend following
Noro Shifted Moving Average Stop Loss Strategy
The Noro Shifted Moving Average Stop Loss Strategy is a trend following strategy. It calculates the 3-day simple moving average line, and sets a long line above it and a stop loss line below it at given percentages…
Overview
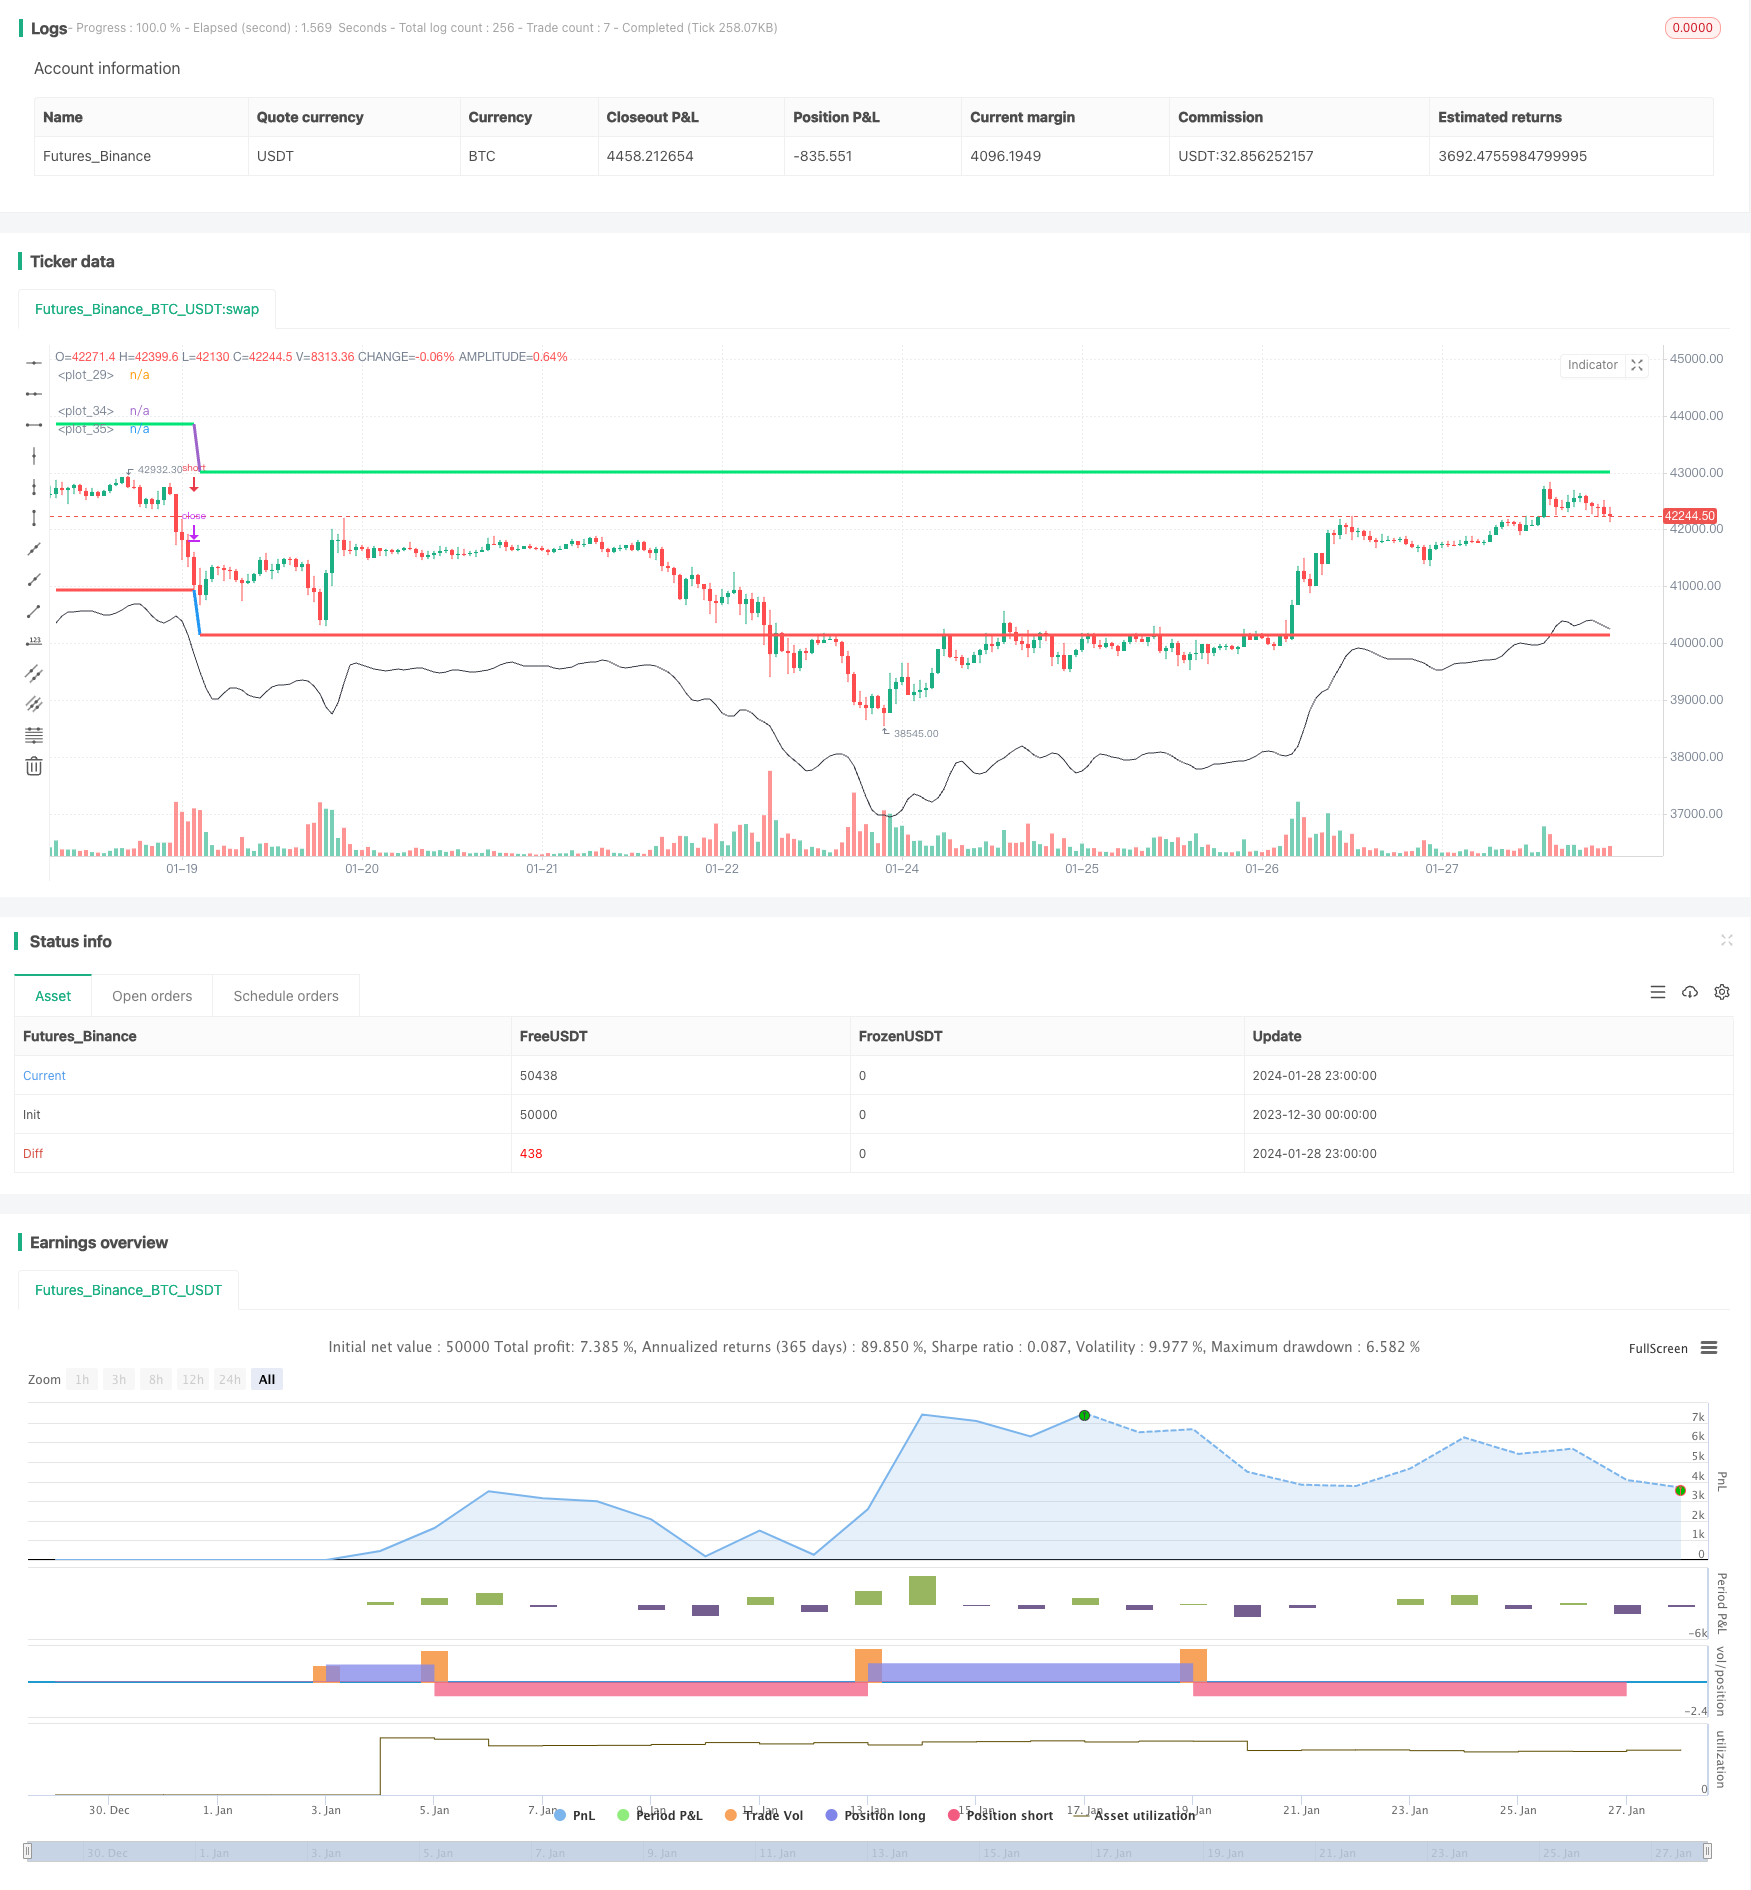
The Noro Shifted Moving Average Stop Loss Strategy is a trend following strategy. It calculates the 3-day simple moving average line, and sets a long line above it and a stop loss line below it at given percentages. Take profit lines are also set. This allows opening positions when trends start, and stopping out when trends reverse.
Strategy Logic
The core of this strategy is calculating the 3-day simple moving average line ma. Then a percentage lo is added above ma to get the long line long for entries. When price crosses above long, long positions are opened. Below ma a percentage sl is subtracted to get the stop loss line stop. When price drops below stop, positions are stopped out. There are also take profit lines take set at a percentage tp above the current average holding price.
The specific rules are:
- Calculate 3-day simple moving average ma
- Long line long = ma + ma * lo%
- Take profit line take = Current average holding price + Current average holding price * tp%
- Stop loss line stop = Current average holding price - Current average holding price * sl%
This constructs a trend following strategy that sets entry, take profit and stop loss lines based on the ma benchmark and configurable percentages.
Advantage Analysis
The biggest advantage of this strategy is it can automatically track trends. By going long to catch uptrends and short for downtrends without needing pattern recognition, it catches trends. Adding take profit and stop loss further allows it to stop out automatically when trends end to limit drawdowns.
Another advantage is flexible parameter adjustment. By changing the percentages for long, take profit and stop loss, position sizing and stop loss spacing can be easily controlled.
Risk Analysis
The biggest risk of this strategy is slippage. As a stop order is used for stop loss, in a fast dropping market prices can gap down way below the stop loss before orders are filled. This can lead to catastrophic losses.
Another risk comes from poorly set parameters causing too frequent entries and exits, increasing commission costs.
Optimization Directions
The strategy can be optimized in the following ways:
Use limit orders instead of stop orders for stop losses to avoid slippage risks
Add position sizing settings to scale in and out smoothly, reducing trade frequency
Add trend detection filters to avoid false signals in non-trending markets
Optimize parameter settings to find optimum combinations
Conclusion
The Noro Shifted Moving Average Stop Loss Strategy is a simple and practical trend following strategy. It can automatically track trends with take profit and stop loss controlling risk. The biggest risks come from potential slippage and overly frequent trading from poor parameter optimization. By improving stop loss technique and optimizing parameters, the strategy can be made more robust.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | -5 | Long-line, % |
| v_input_2 | 5 | Take-profit |
| v_input_3 | 2 | Stop-loss |
Source Pine Script
/*backtest
start: 2023-12-30 00:00:00
end: 2024-01-29 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//2019
//Noro

//@version=4
strategy("Stop-loss", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 0)

//Settings
lo = input(-5.0, title = "Long-line, %")
tp = input(5.0, title = "Take-profit")
sl = input(2.0, title = "Stop-loss")

//SMA
ma = sma(ohlc4, 3)
long = ma + ((ma / 100) * lo)

//Orders
avg = strategy.position_avg_price
if ma > 0
    strategy.entry("Long", strategy.long, limit = long)
    strategy.entry("Take", strategy.short, 0, limit = avg + ((avg / 100) * tp))
    strategy.entry("Stop", strategy.short, 0, stop = avg - ((avg / 100) * sl))

//Cancel order
if strategy.position_size == 0
    strategy.cancel("Take")
    strategy.cancel("Stop")

//Lines
plot(long, offset = 1, color = color.black, transp = 0)
take = avg != 0 ? avg + ((avg / 100) * tp) : long + ((long / 100) * tp)
stop = avg != 0 ? avg - ((avg / 100) * sl) : long - ((long / 100) * sl)
takelinecolor = avg == avg[1] and avg != 0 ? color.lime : na
stoplinecolor = avg == avg[1] and avg != 0 ? color.red : na
plot(take, offset = 1, color = takelinecolor, linewidth = 3, transp = 0)
plot(stop, offset = 1, color = stoplinecolor, linewidth = 3, transp = 0)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-30. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Noro-Shifted-Moving-Average-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m