Strategy vault / Mean reversion
Open Close Cross Point Strategy
The open close cross point strategy is a quantitative trading strategy based on moving average crossovers. It determines price trends by calculating crosses between fast and slow moving average lines and generates…
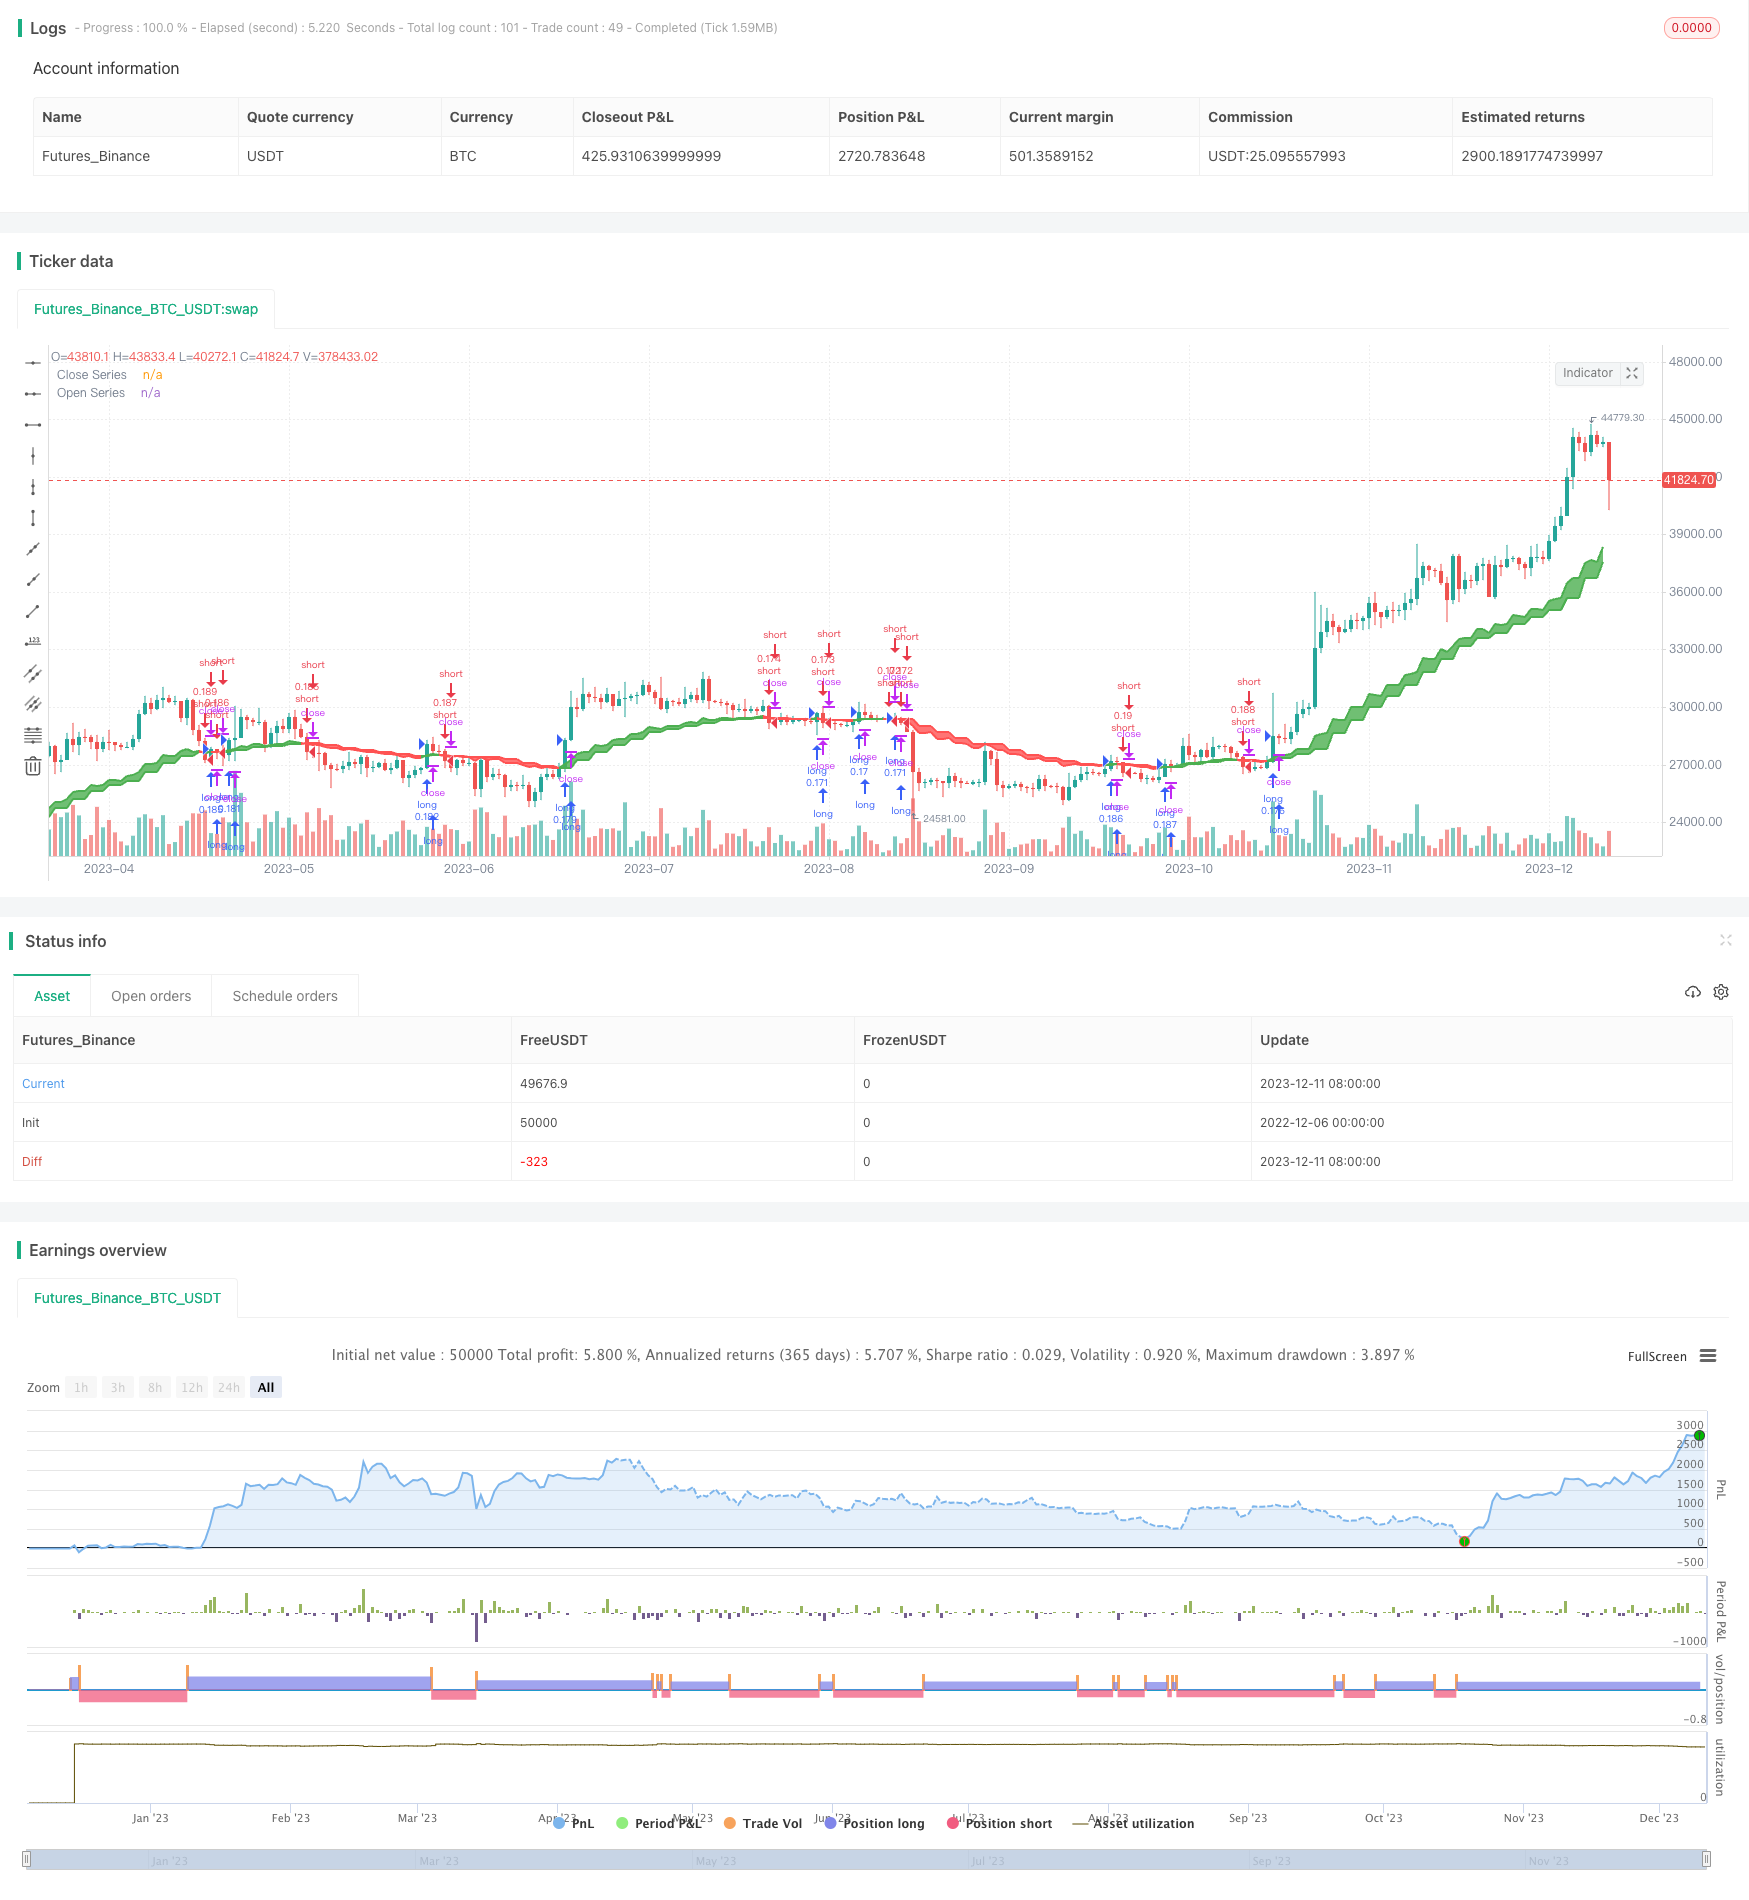
Overview
The open close cross point strategy is a quantitative trading strategy based on moving average crossovers. It determines price trends by calculating crosses between fast and slow moving average lines and generates buy and sell signals at crossover points. This strategy uses Hull Moving Average as the fast line and Super Smoother filter as the slow line. This combination incorporates both the smoothness and trend determination ability of moving averages and can effectively identify price movements to produce relatively reliable trading signals.
Strategy Principle
The formulas for calculating the open close cross point strategy are: Fast line (Hull MA): WMA(2 * WMA(price, n/2) - WMA(price, n), SQRT(n)) Slow line (Super Smoother Filter): Price triple filter
Where WMA is the Weighted Moving Average, SQRT is the square root, and the filter contains one first order lag term and two second order lag terms.
The strategy judges the relationship between the fast and slow lines by calculating their values. Where:
Upward crossover of fast line is buy signal
Downward crossover of fast line is sell signal
Advantage Analysis
The open close cross point strategy combines the advantages of dual moving average judgments and point trading. It can accurately capture trend turning points for timely entries and exits. Compared to single moving average strategies, it has the following advantages:
- Dual moving average combination eliminates false signals. Fast line determines trend direction/strength, slow line filters out oscillations so signals become more reliable.
- Super Smoother filter has superb data fitting capabilities to effectively extract price trends.
- Hull MA has high sensitivity to price changes and can timely spot reversals.
Risk Analysis
The open close cross point strategy also carries certain risks:
- More whipsaw signals may occur during ranging markets. Can widen interval between MAs to reduce false signals.
- Excessively wide intervals between MAs may miss some opportunities. Need to balance signal quantity and quality.
- This strategy is more suitable for products with clearer trends, not advisable for highly volatile products.
Optimization Directions
The open close cross point strategy can be optimized in the following dimensions:
- Adjust MA parameters to suit products of different periods and volatility ranges.
- Add in supplementary indicators or filters to determine trend quality to reduce whipsaws.
- Optimize position sizing by incorporating trend strength indicators.
Conclusion
The open close cross point strategy inherits the advantages of moving average strategies while expanding the use of dual moving average judgments and point trading models to form a more advanced and reliable quantitative trading scheme. It has unique advantages in timing trading which deserve live testing and application exploration. This article thoroughly parses the principles, strengths and weaknesses of this strategy, and provides optimization ideas for reference. It is believed that with continuous improvements on the model and parameters, this strategy will become a formidable market timing tool.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Use Alternate Resolution? |
| v_input_2 | 3 | Multiplier for Alernate Resolution |
| v_input_string_1 | 0 | MA Type: : SMMA | EMA | DEMA | TEMA | WMA | VWMA | SMA | HullMA | LSMA | ALMA | SSMA | TMA |
| v_input_int_1 | 8 | MA Period |
| v_input_int_2 | 6 | Offset for LSMA / Sigma for ALMA |
| v_input_float_1 | 0.85 | Offset for ALMA |
| v_input_3 | false | Show coloured Bars to indicate Trend? |
| v_input_int_3 | false | Delay Open/Close MA (Forces Non-Repainting) |
| v_input_string_2 | 0 | What trades should be taken : : BOTH | SHORT | LONG | NONE |
| v_input_int_4 | false | Initial Stop Loss Points (zero to disable) |
| v_input_int_5 | false | Initial Target Profit Points (zero for disable) |
| v_input_int_6 | 10000 | Number of Bars for Back Testing |
| v_input_4 | false | - SET to ZERO for Daily or Longer Timeframes |
Source Pine Script
/*backtest
start: 2022-12-06 00:00:00
end: 2023-12-12 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
//

strategy(title='Open Close Cross Strategy ', shorttitle='sacinvesting', overlay=true, pyramiding=0, default_qty_type=strategy.percent_of_equity, default_qty_value=10, calc_on_every_tick=false)

// === INPUTS ===
useRes = input(defval=true, title='Use Alternate Resolution?')
intRes = input(defval=3, title='Multiplier for Alernate Resolution')
stratRes = timeframe.ismonthly ? str.tostring(timeframe.multiplier * intRes, '###M') : timeframe.isweekly ? str.tostring(timeframe.multiplier * intRes, '###W') : timeframe.isdaily ? str.tostring(timeframe.multiplier * intRes, '###D') : timeframe.isintraday ? str.tostring(timeframe.multiplier * intRes, '####') : '60'
basisType = input.string(defval='SMMA', title='MA Type: ', options=['SMA', 'EMA', 'DEMA', 'TEMA', 'WMA', 'VWMA', 'SMMA', 'HullMA', 'LSMA', 'ALMA', 'SSMA', 'TMA'])
basisLen = input.int(defval=8, title='MA Period', minval=1)
offsetSigma = input.int(defval=6, title='Offset for LSMA / Sigma for ALMA', minval=0)
offsetALMA = input.float(defval=0.85, title='Offset for ALMA', minval=0, step=0.01)
scolor = input(false, title='Show coloured Bars to indicate Trend?')
delayOffset = input.int(defval=0, title='Delay Open/Close MA (Forces Non-Repainting)', minval=0, step=1)
tradeType = input.string('BOTH', title='What trades should be taken : ', options=['LONG', 'SHORT', 'BOTH', 'NONE'])
// === /INPUTS ===

// Constants colours that include fully non-transparent option.
green100 = #008000FF
lime100 = #00FF00FF
red100 = #FF0000FF
blue100 = #0000FFFF
aqua100 = #00FFFFFF
darkred100 = #8B0000FF
gray100 = #808080FF

// === BASE FUNCTIONS ===
// Returns MA input selection variant, default to SMA if blank or typo.
variant(type, src, len, offSig, offALMA) =>
    v1 = ta.sma(src, len)  // Simple
    v2 = ta.ema(src, len)  // Exponential
    v3 = 2 * v2 - ta.ema(v2, len)  // Double Exponential
    v4 = 3 * (v2 - ta.ema(v2, len)) + ta.ema(ta.ema(v2, len), len)  // Triple Exponential
    v5 = ta.wma(src, len)  // Weighted
    v6 = ta.vwma(src, len)  // Volume Weighted
    v7 = 0.0
    sma_1 = ta.sma(src, len)  // Smoothed
    v7 := na(v7[1]) ? sma_1 : (v7[1] * (len - 1) + src) / len
    v8 = ta.wma(2 * ta.wma(src, len / 2) - ta.wma(src, len), math.round(math.sqrt(len)))  // Hull
    v9 = ta.linreg(src, len, offSig)  // Least Squares
    v10 = ta.alma(src, len, offALMA, offSig)  // Arnaud Legoux
    v11 = ta.sma(v1, len)  // Triangular (extreme smooth)
    // SuperSmoother filter
    // ©️ 2013 John F. Ehlers
    a1 = math.exp(-1.414 * 3.14159 / len)
    b1 = 2 * a1 * math.cos(1.414 * 3.14159 / len)
    c2 = b1
    c3 = -a1 * a1
    c1 = 1 - c2 - c3
    v12 = 0.0
    v12 := c1 * (src + nz(src[1])) / 2 + c2 * nz(v12[1]) + c3 * nz(v12[2])
    type == 'EMA' ? v2 : type == 'DEMA' ? v3 : type == 'TEMA' ? v4 : type == 'WMA' ? v5 : type == 'VWMA' ? v6 : type == 'SMMA' ? v7 : type == 'HullMA' ? v8 : type == 'LSMA' ? v9 : type == 'ALMA' ? v10 : type == 'TMA' ? v11 : type == 'SSMA' ? v12 : v1

// security wrapper for repeat calls
reso(exp, use, res) =>
    security_1 = request.security(syminfo.tickerid, res, exp, gaps=barmerge.gaps_off, lookahead=barmerge.lookahead_on)
    use ? security_1 : exp

// === /BASE FUNCTIONS ===

// === SERIES SETUP ===
closeSeries = variant(basisType, close[delayOffset], basisLen, offsetSigma, offsetALMA)
openSeries = variant(basisType, open[delayOffset], basisLen, offsetSigma, offsetALMA)
// === /SERIES ===

// === PLOTTING ===

// Get Alternate resolution Series if selected.
closeSeriesAlt = reso(closeSeries, useRes, stratRes)
openSeriesAlt = reso(openSeries, useRes, stratRes)
//
trendColour = closeSeriesAlt > openSeriesAlt ? color.green : color.red
bcolour = closeSeries > openSeriesAlt ? lime100 : red100
barcolor(scolor ? bcolour : na, title='Bar Colours')
closeP = plot(closeSeriesAlt, title='Close Series', color=trendColour, linewidth=2, style=plot.style_line, transp=20)
openP = plot(openSeriesAlt, title='Open Series', color=trendColour, linewidth=2, style=plot.style_line, transp=20)
fill(closeP, openP, color=trendColour, transp=80)

// === /PLOTTING ===
//
//
// === ALERT conditions
xlong = ta.crossover(closeSeriesAlt, openSeriesAlt)
xshort = ta.crossunder(closeSeriesAlt, openSeriesAlt)
longCond = xlong  // alternative: longCond[1]? false : (xlong or xlong[1]) and close>closeSeriesAlt and close>=open
shortCond = xshort  // alternative: shortCond[1]? false : (xshort or xshort[1]) and close<closeSeriesAlt and close<=open
// === /ALERT conditions.

// === STRATEGY ===
// stop loss
slPoints = input.int(defval=0, title='Initial Stop Loss Points (zero to disable)', minval=0)
tpPoints = input.int(defval=0, title='Initial Target Profit Points (zero for disable)', minval=0)
// Include bar limiting algorithm
ebar = input.int(defval=10000, title='Number of Bars for Back Testing', minval=0)
dummy = input(false, title='- SET to ZERO for Daily or Longer Timeframes')
//
// Calculate how many mars since last bar
tdays = (timenow - time) / 60000.0  // number of minutes since last bar
tdays := timeframe.ismonthly ? tdays / 1440.0 / 5.0 / 4.3 / timeframe.multiplier : timeframe.isweekly ? tdays / 1440.0 / 5.0 / timeframe.multiplier : timeframe.isdaily ? tdays / 1440.0 / timeframe.multiplier : tdays / timeframe.multiplier  // number of bars since last bar
//
//set up exit parameters
TP = tpPoints > 0 ? tpPoints : na
SL = slPoints > 0 ? slPoints : na

// Make sure we are within the bar range, Set up entries and exit conditions
if (ebar == 0 or tdays <= ebar) and tradeType != 'NONE'
    strategy.entry('long', strategy.long, when=longCond == true and tradeType != 'SHORT')
    strategy.entry('short', strategy.short, when=shortCond == true and tradeType != 'LONG')
    strategy.close('long', when=shortCond == true and tradeType == 'LONG')
    strategy.close('short', when=longCond == true and tradeType == 'SHORT')
    strategy.exit('XL', from_entry='long', profit=TP, loss=SL)
    strategy.exit('XS', from_entry='short', profit=TP, loss=SL)

// === /STRATEGY ===
// eof
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Open-Close-Cross-Point-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Advanced Quantitative Trend Following and Cloud Reversal Composite Trading StrategyPine Script · Mean reversion · 1d
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Bidirectional Moving Average Reversion Trading StrategyPine Script · Mean reversion · 1h