Open Drive Strategy
The open drive strategy observes price behavior in the first 30 minutes after market open each trading day, identifies strong directional breakouts, and enters trend trades in that direction. It mainly utilizes the…
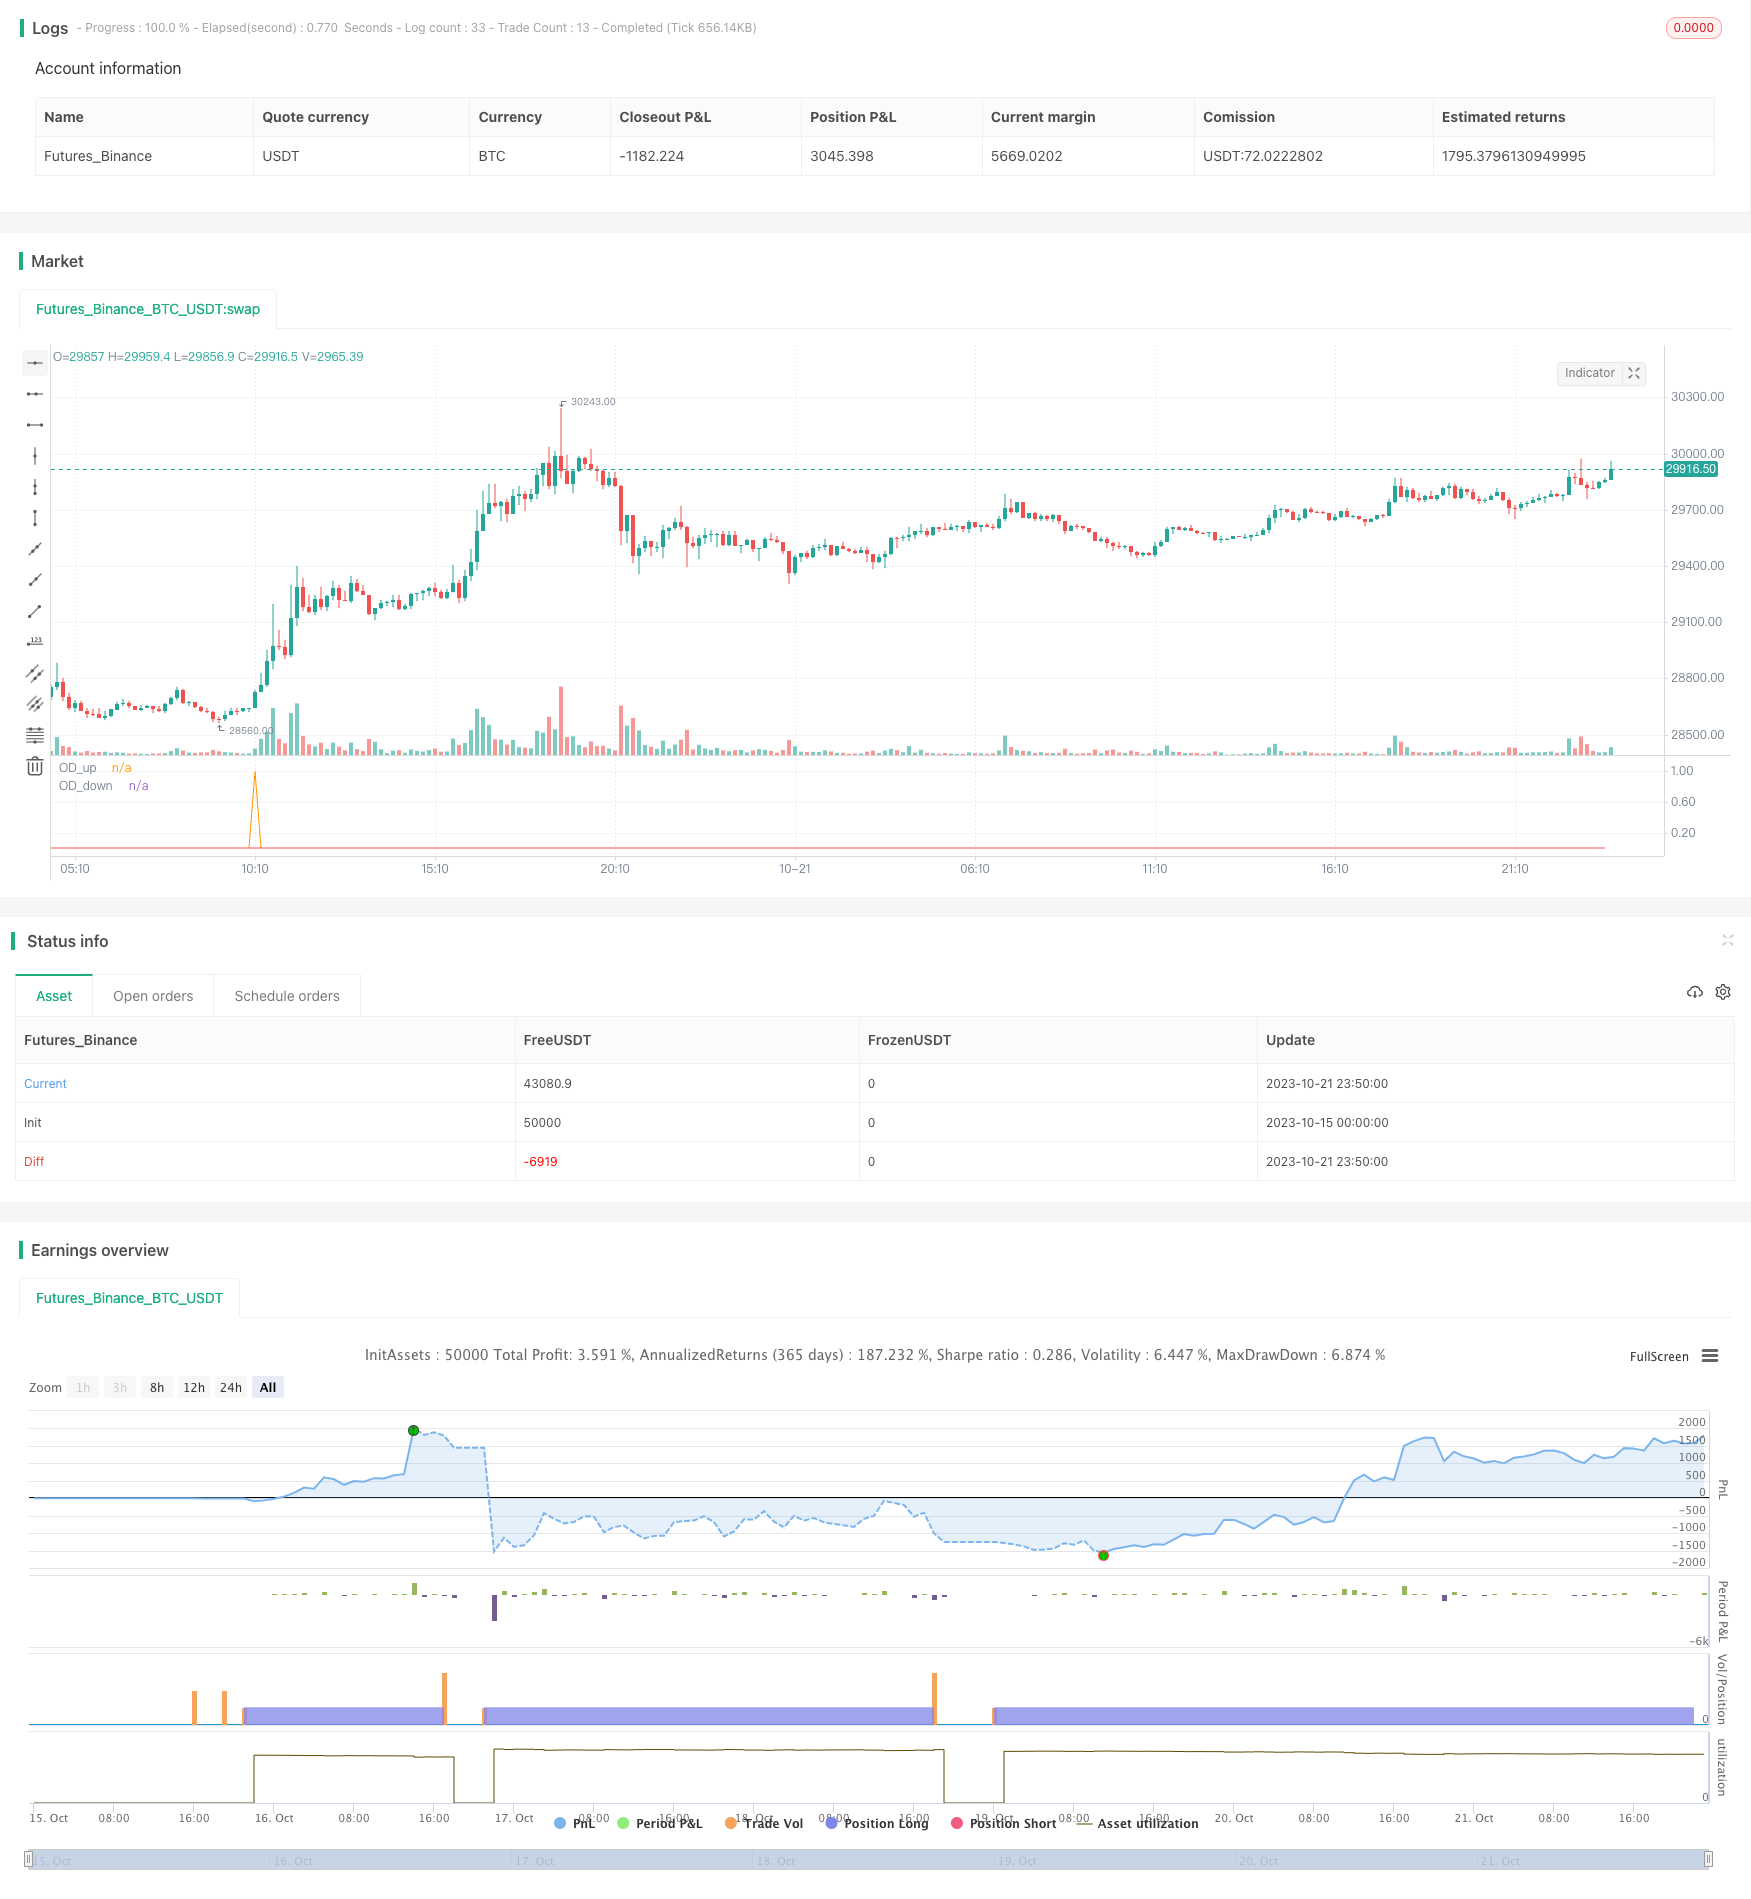
Overview
The open drive strategy observes price behavior in the first 30 minutes after market open each trading day, identifies strong directional breakouts, and enters trend trades in that direction. It mainly utilizes the increased liquidity and trading volume after open, which can generate larger price swings and directional forces.
Strategy Logic
Use 30-minute bars, as there needs to be enough time to measure extreme price moves after open.
Identify bars opening during these time periods: 0700-0715, 0800-0815, 1300-1315, 1430-1445.
Check if open bar satisfies:
Open near bar low, close near bar high (up bar)
Or open near bar high, close near bar low (down bar)
And high exceeds previous 5-bar high by 1 x 5-bar range, or low breaks previous 5-bar low by 1 x 5-bar range (breakout)
If above conditions met, enter trend trade in that direction 3 bars after signal bar.
Set stop loss at high/low of entry bar.
Hold position for 3 bars (90 mins), then exit.
Advantage Analysis
- Captures strong directional moves resulting from high liquidity after open
- Breakout filters avoid false signals from choppy conditions
- Higher timeframe reduces over-trading
- Stop loss avoids excessive losses
Risk Analysis
- Fixed open time periods risk missing trending breakouts
- Inadequate breakout threshold may filter valid signals
- Fixed holding time cannot adapt to specific conditions
- No trailing stop fails to follow trends
Consider:
- Dynamically determine open period with more parameters
- Optimize breakout threshold
- Adjust holding time based on volatility
- Add trailing stop procedures
Improvement Directions
- Incorporate more indicators to improve signal quality
- Enter trades on lower timeframes for more frequency
- Optimize parameters like open period, breakout threshold, stops etc. based on backtests
- Consider trailing stops, re-entries etc. to boost profits
- Backtest across various products to find best fit
Summary
The open drive strategy follows trend by capturing strong directional breakouts after open. Compared to random entries, it provides better risk-reward characteristics. The key is proper parameter tuning, instrument selection, and balancing frequency and profitability. It suits experienced traders with additional analysis.
Source Pine Script
/*backtest
start: 2023-10-15 00:00:00
end: 2023-10-22 00:00:00
period: 10m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Marcns_

//@version=5
// a script that highlights open drives around cash market opens throughout the day
// this indicator identifies the following cash open, open drives 0700 - 0715 / 0800 - 0815 / 1300 - 1315 / 1430 - 1445
// an open drive is when a cash market opens and price runs either up or down away from the opening price, often this will be the high or the low the remainer of the session or day
// and often identify a trend session
strategy("Open Drive", commission_type =  strategy.commission.cash_per_contract, commission_value = 3.8 )

// open drive filter times - all times GMT
eu_sev = time(timeframe.period, "0700-0715", "GB")
eu_eig = time(timeframe.period, "0800-0815", "GB")
us_one = time(timeframe.period, "1300-1315", "GB")
us_two = time(timeframe.period, "1430-1445", "GB")


// identify bar that opens at low and closes at high + vice versa
// bar needs to open at one extreme and close at another
TrndExThreshold_Open = 0.15
TrndExThreshold_Close = 0.15

// add a bar range expansion filter - range of bar correlates to volume, high volume = wider range. This script will be able to filter for a break of a 5 bar range +100% or -100%

fbhi = ta.highest(5)
fblo = ta.lowest(5)

fbr = (fbhi - fblo)

RangeEx_up = 0.0

if high >= (fbhi[1] + fbr[1])
    RangeEx_up := 1.0
else
    na

// range ex down

RangeEx_do = 0.0

if low <= (fblo[1] - fbr[1])
    RangeEx_do := 1.0
else
    na


//#1 open within 5% of low

OpenAtLow = 0.0

if (close > open) and (open-low) / (high-low) < TrndExThreshold_Open
    OpenAtLow := 1.0
else
    na

//#2 close within 5% of high

CloseAtHigh = 0.0

if (close > open) and (high-close) / (high-low) < TrndExThreshold_Close
    CloseAtHigh := 1.0
else
    na

OD_Up = 0.0

if (OpenAtLow + CloseAtHigh + RangeEx_up == 3.0) and ( eu_sev or eu_eig or us_one or us_two)
    OD_Up := 1
else
    na

plot(OD_Up, title = "OD_up")


OpenAtHigh = 0.0

if (close < open) and (high-open) / (high-low) < TrndExThreshold_Open
    OpenAtHigh := 1.0
else
    na

//#2 close within 5% of high

CloseAtLow = 0.0

if (close < open) and (close-low) / (high-low) < TrndExThreshold_Close
    CloseAtLow := 1.0
else
    na

OD_Down = 0.0

if (OpenAtHigh + CloseAtLow + RangeEx_do == 3.0) and ( eu_sev or eu_eig or us_one or us_two)
    OD_Down := -1
else
    na

plot(OD_Down, title = "OD_down", color = color.red)


//3sma

ma = ta.sma(close,3)

// one time framing - highlight bars the make a series of lower highs or higher lows to identify trend
// one time frame up
otf_u = 0.0

if close > ma and close[1] > ma[1]
    otf_u := 1
else
    na
// one time frame down
otf_d = 0.0

if close < ma and close[1] < ma[1]
    otf_d := 1
else
    na


//bgcolor(otf_u ? color.rgb(76, 175, 79, 70) : na)
//bgcolor(otf_d ? color.rgb(255, 82, 82, 66) : na)

// record high and low of entry bar into variable for absolute stop
// buy stop
bs = 0.0

if OD_Up
    bs := low[1]
else
    na

// sell stop
ss = 0.0

if OD_Down
    ss := high[1]
else
    na


// strategy entry and exits
// long
if OD_Up
    strategy.entry("el", strategy.long, 2)
if ta.barssince(OD_Up)> 3
    strategy.exit(id = "ex" , from_entry = "el", limit = close)

// short
if OD_Down
    strategy.entry("es", strategy.short, 2)
if ta.barssince(OD_Down)> 3
    strategy.exit(id = "ex" , from_entry = "es", limit = close)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Open-Drive-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Adaptive Trading Strategy Based on ADX IndicatorPine Script · Breakout · 1d
- Average Line Breakthrough StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d