Strategy vault / Trend following
Open Market Exposure Dynamic Position Adjustment Quantitative Trading Strategy
This strategy is a quantitative trading system based on Open Market Exposure (OME), which makes trading decisions by calculating cumulative OME values to judge market trends, combined with risk control indicators…
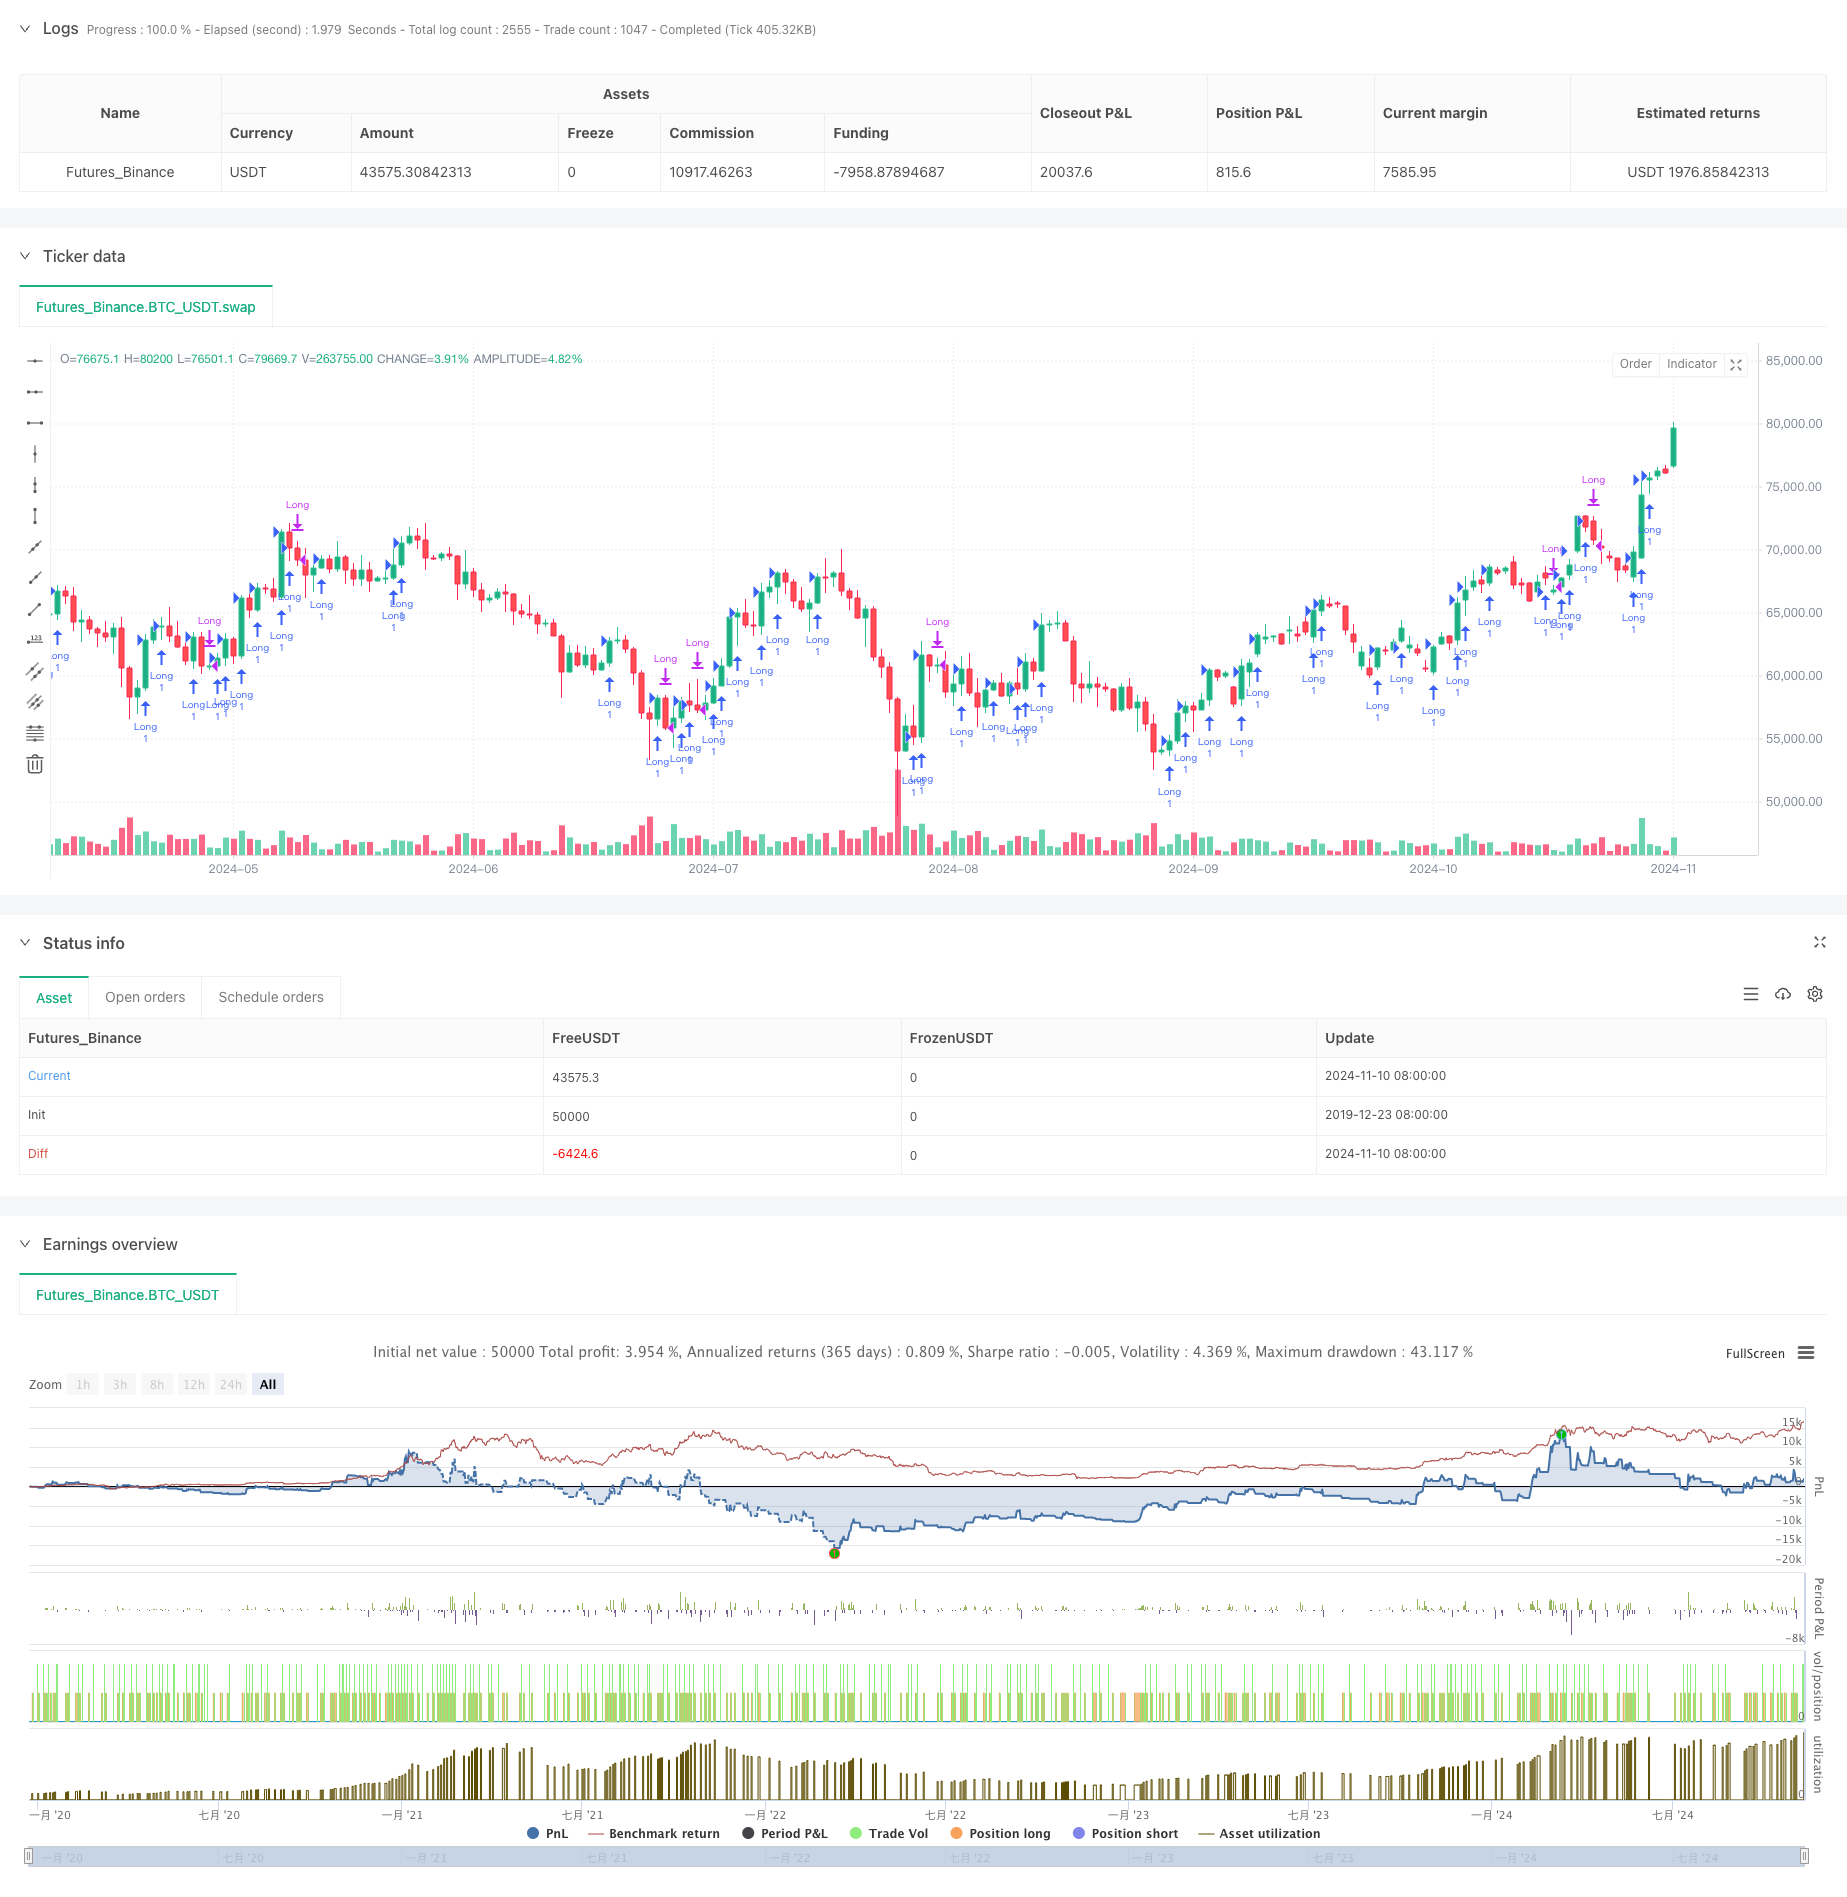
Overview
This strategy is a quantitative trading system based on Open Market Exposure (OME), which makes trading decisions by calculating cumulative OME values to judge market trends, combined with risk control indicators such as the Sharpe Ratio. The strategy adopts a dynamic take-profit and stop-loss mechanism to effectively control risk while ensuring returns. It mainly focuses on how price movements after market opening affect overall trends, using scientific methods to judge changes in market sentiment and trends.
Strategy Principle
The core of the strategy is to measure market trends by calculating Open Market Exposure (OME). OME is calculated as the ratio of the difference between the current closing price and the previous day's opening price relative to the previous opening price. The strategy sets cumulative OME thresholds as trading signals, entering long positions when cumulative OME exceeds the set threshold and closing positions when it falls below the negative threshold. The Sharpe Ratio is introduced as a risk assessment indicator, measuring the risk-return ratio by calculating the mean and standard deviation of cumulative OME. The strategy also includes a fixed percentage take-profit and stop-loss mechanism to protect profits and control losses.
Strategy Advantages
- High market sensitivity: Quickly captures trend changes after market opening through the OME indicator
- Comprehensive risk control: Forms a multi-level risk control system combining Sharpe Ratio and stop-loss mechanisms
- Good adaptability: Strategy parameters can be adjusted according to different market conditions
- Clear calculation logic: Simple and intuitive indicator calculations, easy to understand and implement
- High capital efficiency: Adopts dynamic position management to improve capital utilization
Strategy Risks
- Market volatility risk: May generate false signals in highly volatile markets
- Slippage risk: Frequent trading may lead to higher slippage costs
- Parameter sensitivity: Strategy effectiveness is sensitive to parameter settings
- Trend dependency: May underperform in oscillating markets
- Drawdown risk: Major trend turning points may cause significant drawdowns
Strategy Optimization Directions
- Introduce volatility filtering: Add indicators like ATR or Bollinger Bands to filter market volatility
- Optimize take-profit and stop-loss: Consider replacing fixed percentages with dynamic mechanisms
- Enhance market environment judgment: Introduce trend strength indicators to optimize trading timing
- Improve position management: Dynamically adjust position sizes based on Sharpe Ratio
- Add fund management: Design more comprehensive fund management rules
Summary
The Open Market Exposure Dynamic Position Adjustment Strategy is a complete trading system that combines technical analysis and risk management. Through innovative application of the OME indicator, it achieves effective grasp of market trends. The strategy's overall design is reasonable, with strong practicality and scalability. Through continuous optimization and improvement, this strategy has the potential to achieve better performance in actual trading.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-11 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Open Market Exposure (OME) Strategy", overlay=true)

// Input parameters
length = input(14, title="Length for Variance")
sharpe_length = input(30, title="Length for Sharpe Ratio")
threshold = input(0.01, title="Cumulative OME Threshold")  // Define a threshold for entry
take_profit = input(0.02, title="Take Profit (%)")  // Define a take profit percentage
stop_loss = input(0.01, title="Stop Loss (%)")  // Define a stop loss percentage

// Calculate Daily Returns
daily_return = (close - close[1]) / close[1]

// Open Market Exposure (OME) calculation
ome = (close - open[1]) / open[1]

// Cumulative OME
var float cum_ome = na
if na(cum_ome)
    cum_ome := 0.0
if (dayofweek != dayofweek[1])  // Reset cumulative OME daily
    cum_ome := 0.0
cum_ome := cum_ome + ome

// Performance Metrics Calculation (Sharpe Ratio)
mean_return = ta.sma(cum_ome, sharpe_length)
std_dev = ta.stdev(cum_ome, sharpe_length)
sharpe_ratio = na(cum_ome) or (std_dev == 0) ? na : mean_return / std_dev

// Entry Condition: Buy when Cumulative OME crosses above the threshold
if (cum_ome > threshold)
    strategy.entry("Long", strategy.long)

// Exit Condition: Sell when Cumulative OME crosses below the threshold
if (cum_ome < -threshold)
    strategy.close("Long")

// Take Profit and Stop Loss
if (strategy.position_size > 0)
    // Calculate target and stop levels
    target_price = close * (1 + take_profit)
    stop_price = close * (1 - stop_loss)

    // Place limit and stop orders
    strategy.exit("Take Profit", "Long", limit=target_price)
    strategy.exit("Stop Loss", "Long", stop=stop_price)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Open-Market-Exposure-Dynamic-Position-Adjustment-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h
- Dynamic Moving Average and Bollinger Bands Cross Strategy with Fixed Stop Loss Optimization ModelPine Script · Trend following · 3h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h