Strategy vault / Mean reversion
Origix Ashi Strategy Based on Smoothed Moving Average
The main idea of this strategy is to use the smoothed moving average to calculate the smoothed Heiken Ashi to identify price trends, and go long when the price has a golden cross with the smoothed Heiken Ashi, and go…
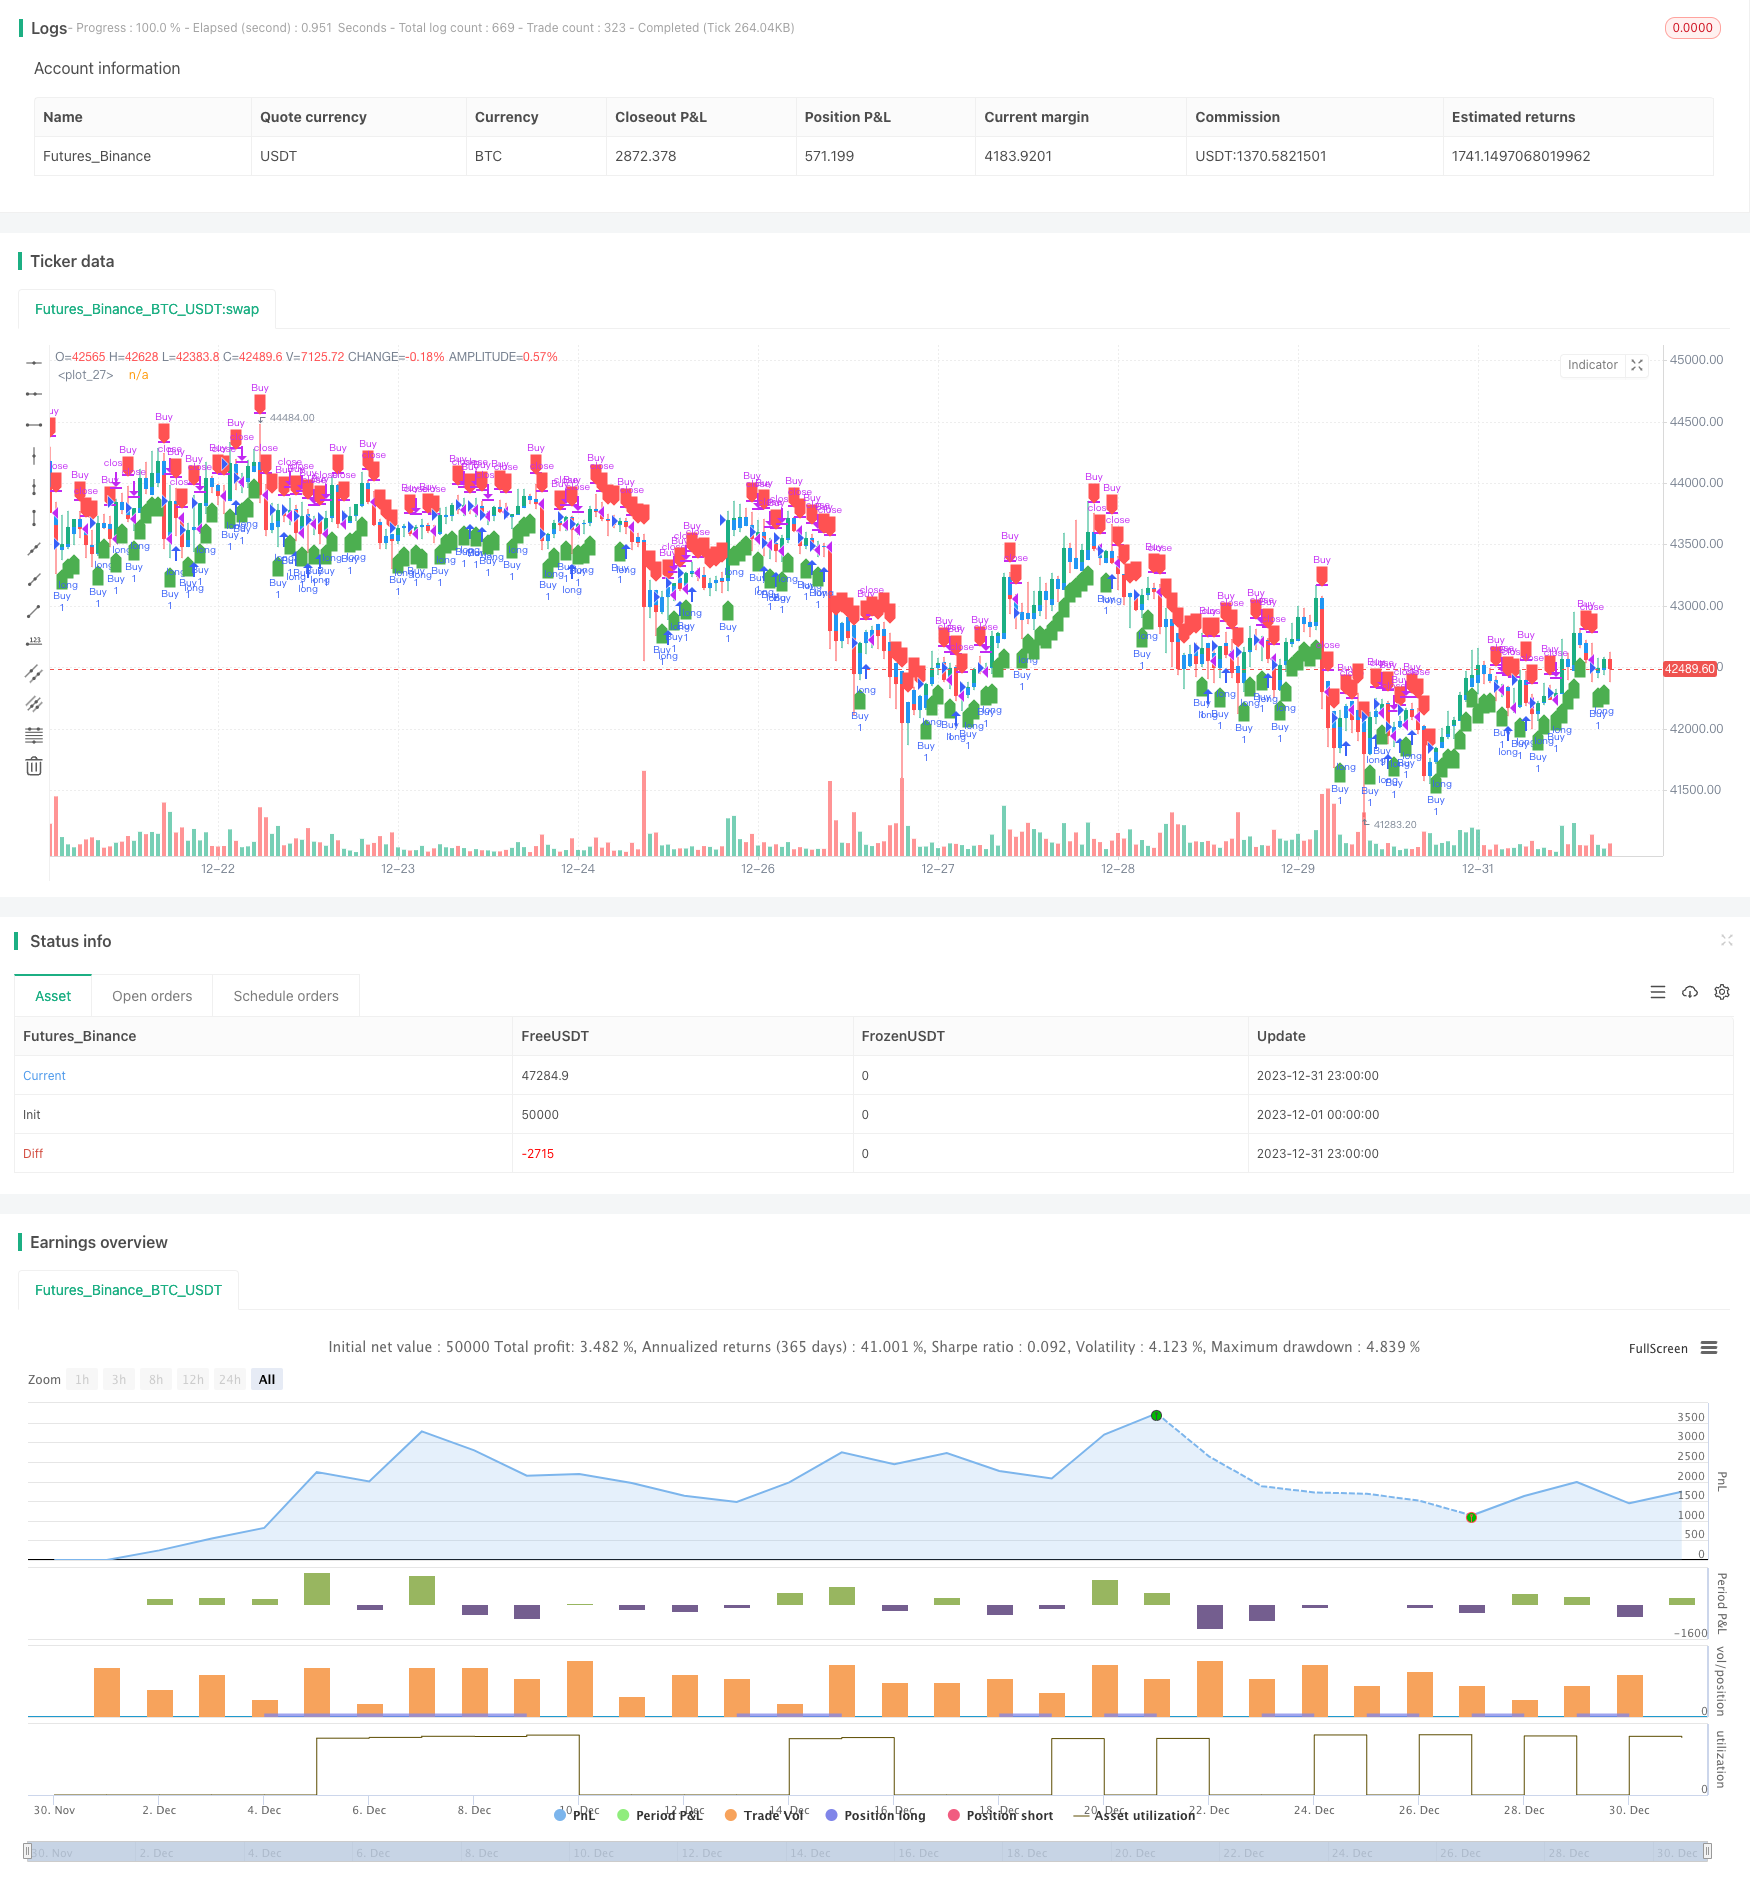
Overview
The main idea of this strategy is to use the smoothed moving average to calculate the smoothed Heiken Ashi to identify price trends, and go long when the price has a golden cross with the smoothed Heiken Ashi, and go short when there is a death cross.
Strategy Logic
The strategy first defines a function smoothedMovingAvg to calculate the smoothed moving average, which uses the previous period's moving average value and the latest price to calculate the current period's smoothed moving average based on certain weights.
Then it defines a function getHAClose to calculate the Heiken Ashi closing price based on the open, high, low and close prices.
In the main strategy logic, it first gets the original prices of different periods, then uses the smoothedMovingAvg function to calculate the smoothed moving average, and then calculates the smoothed Heiken Ashi closing price through the getHAClose function.
Finally, it goes long when the price crosses above the smoothed Heiken Ashi closing price, and closes the position when the price crosses below it. It goes short when the price crosses below the smoothed Heiken Ashi closing price, and closes the position when the price crosses above it.
Advantage Analysis
The biggest advantage of this strategy is that by using the smoothed moving average to calculate the smoothed Heiken Ashi, it can more accurately determine price trends and filter out some noise to avoid generating wrong signals during choppy periods. In addition, the Heiken Ashi itself has the advantage of highlighting trends, which can further improve the accuracy of judgment when combined with prices.
Risk Analysis
The main risks this strategy faces are:
Improper parameter settings of the smoothing may cause the strategy to miss price reversal opportunities or generate wrong signals. The optimal parameters need to be found through repeated backtesting and optimization.
When prices fluctuate sharply, the smoothed moving average may lag behind price changes, resulting in stop loss triggering or missing reversal opportunities. At this time, reducing position size to mitigate risks is necessary.
To address the above risks, methods such as adjusting smoothing parameters, introducing stop loss mechanisms, reducing per trade position sizes can be used to reduce risks and improve strategy stability.
Optimization Directions
The strategy can also be optimized in the following aspects:
Introduce adaptive smoothing parameters to automatically adjust parameters when market volatility increases.
Combine with other indicators as filters to avoid issuing wrong signals during price consolidations. Examples are MACD, KD etc.
Add stop loss mechanisms to control per trade loss. Percentage stop loss or volatility stop loss can be set.
Optimize trading products, trading sessions etc. to focus on products and sessions with the most advantages.
Through the above optimizations, the curve fitting risks of the strategy can be further reduced and the adaptability and stability of the strategy can be improved.
Conclusion
The overall logic of this strategy is clear and easy to understand. By calculating the smoothed Heiken Ashi to determine price trends and making long and short positions accordingly. Its biggest advantage is being able to filter out some noise and improve the accuracy of signal judgment. But there are also certain difficulties in parameter optimization and risks of missing swift reversals. Further optimizations can be done through introducing adaptive mechanisms, expanding indicator combinations etc. to make it worth in-depth research.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_timeframe_1 | (?Display & Timeframe Settings)Timeframe for HA candle calculation | |
| v_input_int_1 | 10 | (?Smoothed HA Settings)HA Price Input Smoothing Length |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

 //@version=5
strategy("Smoothed Heiken Ashi Strategy", overlay=true)

// Inputs
g_TimeframeSettings = 'Display & Timeframe Settings'
time_frame = input.timeframe(title='Timeframe for HA candle calculation', defval='', group=g_TimeframeSettings)

g_SmoothedHASettings = 'Smoothed HA Settings'
smoothedHALength = input.int(title='HA Price Input Smoothing Length', minval=1, maxval=500, step=1, defval=10, group=g_SmoothedHASettings)

// Define a function for calculating the smoothed moving average
smoothedMovingAvg(src, len) =>
    smma = 0.0
    smma := na(smma[1]) ? ta.sma(src, len) : (smma[1] * (len - 1) + src) / len
    smma

// Function to get Heiken Ashi close
getHAClose(o, h, l, c) =>
    ((o + h + l + c) / 4)

// Calculate smoothed HA candles
smoothedHAOpen = request.security(syminfo.tickerid, time_frame, open)
smoothedMA1close = smoothedMovingAvg(request.security(syminfo.tickerid, time_frame, close), smoothedHALength)
smoothedHAClose = getHAClose(smoothedHAOpen, smoothedHAOpen, smoothedHAOpen, smoothedMA1close)

// Plot Smoothed Heiken Ashi candles
plotcandle(open=smoothedHAOpen, high=smoothedHAOpen, low=smoothedHAOpen, close=smoothedHAClose, color=color.new(color.blue, 0), wickcolor=color.new(color.blue, 0))

// Strategy logic
longCondition = close > smoothedHAClose
shortCondition = close < smoothedHAClose

strategy.entry("Buy", strategy.long, when=longCondition)
strategy.close("Buy", when=shortCondition)

plotshape(series=longCondition, title="Buy Signal", color=color.green, style=shape.labelup, location=location.belowbar)
plotshape(series=shortCondition, title="Sell Signal", color=color.red, style=shape.labeldown, location=location.abovebar)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Origix-Ashi-Strategy-Based-on-Smoothed-Moving-Average.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Market Cypher Wave B Automated Trading StrategyPine Script · Mean reversion · 1h
- Multi Indicator Trend Reversal Trading StrategyPine Script · Mean reversion · 1h
- Reversal Fluctuation CAT StrategyPine Script · Mean reversion · 2h
- VAWSI and Trend Persistence Reversal Strategy with Dynamic Length Calculation Multi Indicator Analysis SystemPine Script · Mean reversion · 1h
- Kuberan Strategy The Confluence Approach for Market MasteryPine Script · Mean reversion · 5m
- Oscillating Long Short RSI Crypto Switching StrategyPine Script · Mean reversion · 3m