Strategy vault / Mean reversion
Oscillating Long Short RSI Crypto Switching Strategy
The Oscillating Long-Short RSI Crypto Switching Strategy is a quantitative trading strategy designed for cryptocurrencies. It combines the technical indicator RSI with the ICHIMOKU indicator to identify long and…
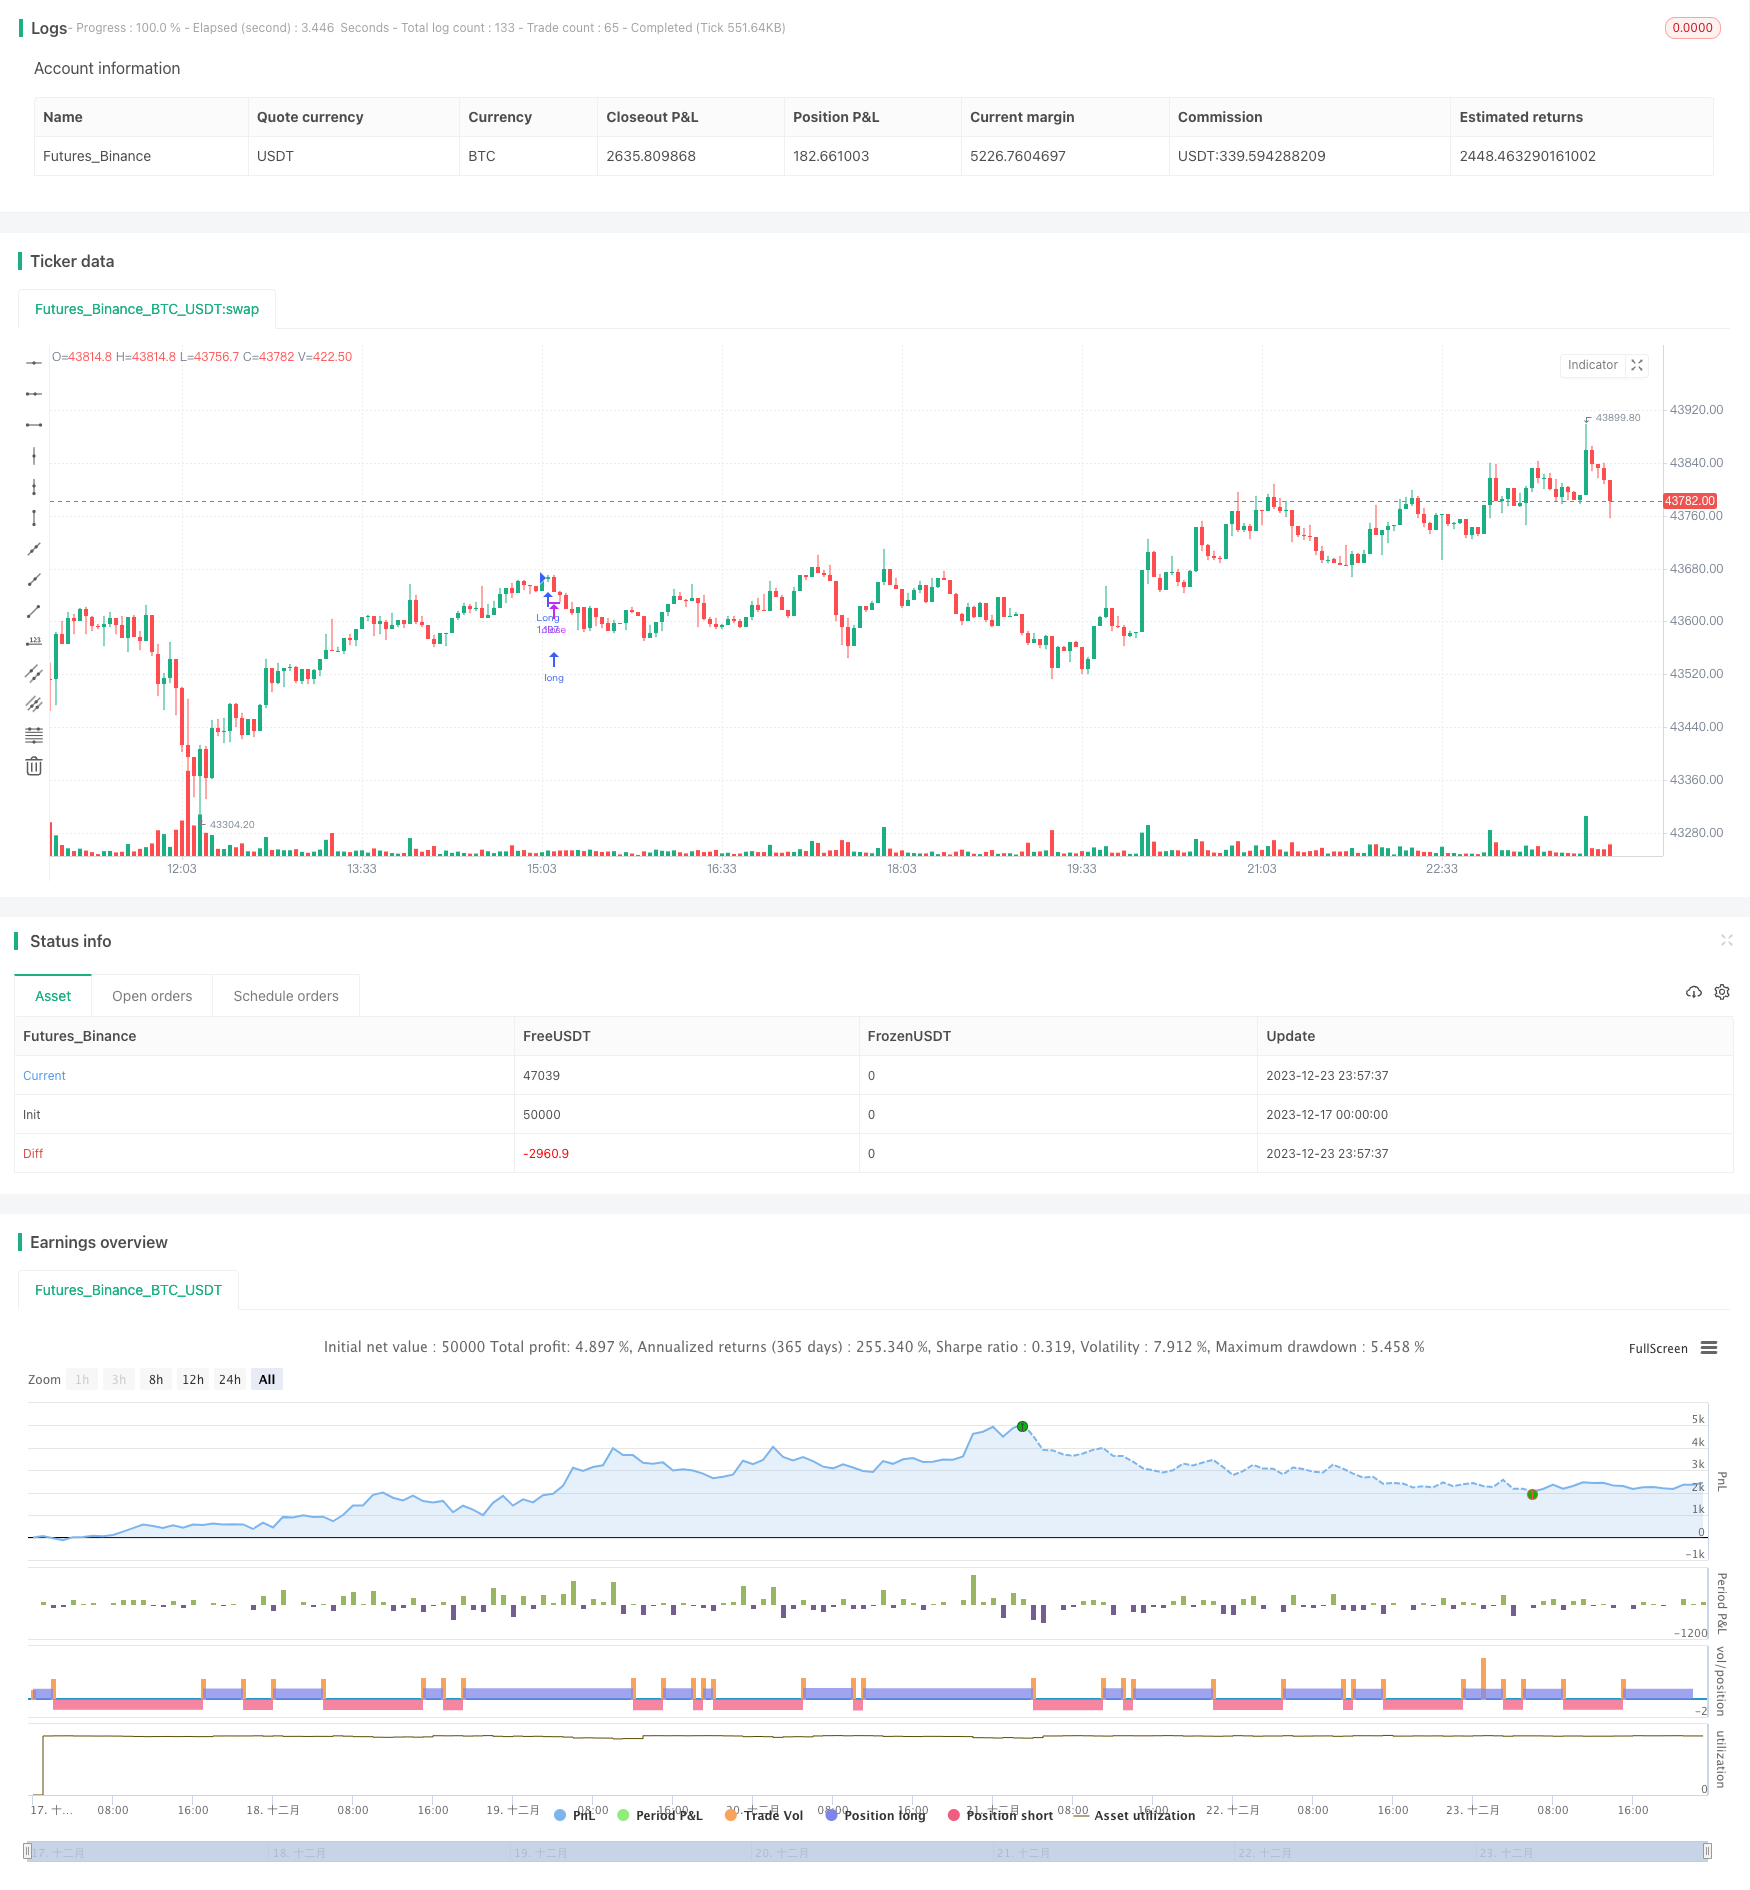
Overview
The Oscillating Long-Short RSI Crypto Switching Strategy is a quantitative trading strategy designed for cryptocurrencies. It combines the technical indicator RSI with the ICHIMOKU indicator to identify long and short signals during price oscillations and achieve buying low and selling high. It is suitable for medium to long term timeframes such as 3-4 hours or longer.
Strategy Logic
The strategy is mainly based on the following indicators and rules:
ICHIMOKU Indicator
- Tenkan Line: Midpoint of highest and lowest price of last 20 bars
- Kijun Line: Midpoint of highest and lowest price of last 50 bars
- Senkou A Line: Midpoint of Tenkan and Kijun Line
- Senkou B Line: Midpoint of highest and lowest price of last 120 bars
- Chikou Line: Closing price of 30 bars ago
RSI Indicator
- Range from 0 to 100
- Above 50 indicates bullish signal, below 50 indicates bearish signal
Entry Rules
Long entry: Tenkan cross above Kijun (golden cross) and price breaks through Senkou A&B Lines, with RSI above 50 at the same time
Short entry: Tenkan cross below Kijun (death cross) and price breaks down Senkou A&B Lines, with RSI below 50 at the same time
Exit Rules
Exit with opposite signal
The strategy takes into account the medium to long term trend, short term capital flow and overbought/oversold conditions to capture reversal opportunities during oscillation. It also sets stop loss rules to avoid huge losses.
Advantage Analysis
1. Judgment based on multiple indicators ensures high certainty
The strategy considers ICHIMOKU's trend and support/resistance judgment, RSI's overbought/oversold conditions, as well as capital flow based on the direction of candle body. This ensures reliable signals.
2. Suitable for oscillation, frequent profit-taking
Cryptocurrency market has large fluctuations. This strategy can fully capture reversal opportunities during oscillations and achieve frequent buying low and selling high.
3. Prevent chasing rises and beating retreats, controllable risk
The strategy comprehensively considers medium and long term trends and short term situations to avoid the risk of chasing rises and beating retreats. Meanwhile, stop loss prevents risk.
Risk Analysis
1. May miss some trending opportunities
The strategy focuses mainly on reversal, which may lead to frequent whipsaws during prolonged trending phases.
2. Single symbol, unable to diversify risk
The strategy trades only a single symbol and cannot diversify against systematic market risk.
3. Stop loss triggered during extreme moves
During extreme market conditions like gap or spikes, stop loss may be triggered forcing exit.
Optimization Directions
1. Add stop loss for lower single loss
Moving stop loss or percentage stop loss can be used to lock in profits and prevent full retracement.
2. Correlate with indexes to diversify market risk
Look for trading opportunities among highly correlated symbols to diversify systematic market risk.
3. Additional filters to reduce invalid trades
Filters like price volatility or volume changes can be added to avoid invalid reversal signals and improve profitability rate.
Conclusion
The Oscillating Long-Short RSI Crypto Switching Strategy combines ICHIMOKU and RSI indicators to identify reversal points for cryptocurrencies, suitable for buying low and selling high profit-taking during oscillations. It also sets stop loss rules to control risk. The strategy can be further enhanced by optimizing stop loss mechanism, diversifying risks through correlation and adding conditional filters, worth live testing.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Use Heikin Ashi Candles in Algo Calculations |
| v_input_2 | 20 | Tenkan-Sen Bars |
| v_input_3 | 50 | Kijun-Sen Bars |
| v_input_4 | 120 | Senkou-Span B Bars |
| v_input_5 | 30 | Chikou-Span Offset |
| v_input_6 | 30 | Senkou-Span Offset |
| v_input_7 | true | Long Entry |
| v_input_8 | true | Short Entry |
| v_input_9 | true | From Day |
| v_input_10 | true | From Month |
| v_input_11 | 2019 | From Year |
| v_input_12 | 31 | To Day |
| v_input_13 | 12 | To Month |
| v_input_14 | 2021 | To Year |
Source Pine Script
/*backtest
start: 2023-12-17 00:00:00
end: 2023-12-24 00:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © exlux99

//@version=4

strategy(title="Ichimoku + RSI Crypto trending strategy", overlay=true, initial_capital = 1000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.1, pyramiding=1  )

UseHAcandles    = input(true, title="Use Heikin Ashi Candles in Algo Calculations")
//
// === /INPUTS ===

// === BASE FUNCTIONS ===

haClose = UseHAcandles ? security(heikinashi(syminfo.tickerid), timeframe.period, close) : close
haOpen  = UseHAcandles ? security(heikinashi(syminfo.tickerid), timeframe.period, open) : open
haHigh  = UseHAcandles ? security(heikinashi(syminfo.tickerid), timeframe.period, high) : high
haLow   = UseHAcandles ? security(heikinashi(syminfo.tickerid), timeframe.period, low) : low


//Inputs
ts_bars = input(20, minval=1, title="Tenkan-Sen Bars")
ks_bars = input(50, minval=1, title="Kijun-Sen Bars")
ssb_bars = input(120, minval=1, title="Senkou-Span B Bars")
cs_offset = input(30, minval=1, title="Chikou-Span Offset")
ss_offset = input(30, minval=1, title="Senkou-Span Offset")
long_entry = input(true, title="Long Entry")
short_entry = input(true, title="Short Entry")

//Volatility
//vollength = input(defval=1, title="VolLength")
//voltarget = input(defval=0., type=input.float, step=0.1, title="Volatility Target")
//Difference = abs((haClose - haOpen)/((haClose + haOpen)/2) * 100)
//MovingAverage = sma(Difference, vollength)
//highvolatility = MovingAverage > voltarget

////////////////////////////////////////////////////////////////////////////////
// BACKTESTING RANGE

// From Date Inputs
fromDay = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
fromMonth = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
fromYear = input(defval = 2019, title = "From Year", minval = 1970)

// To Date Inputs
toDay = input(defval = 31, title = "To Day", minval = 1, maxval = 31)
toMonth = input(defval = 12, title = "To Month", minval = 1, maxval = 12)
toYear = input(defval = 2021, title = "To Year", minval = 1970)

// Calculate start/end date and time condition
startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)
time_cond = true

////////////////////////////////////////////////////////////////////////////////

middle(len) => avg(lowest(len), highest(len))

// Ichimoku Components
tenkan = middle(ts_bars)
kijun = middle(ks_bars)
senkouA = avg(tenkan, kijun)
senkouB = middle(ssb_bars)

//RSI
change = change(haClose)
gain = change >= 0 ? change : 0.0
loss = change < 0 ? (-1) * change : 0.0
avgGain = rma(gain, 14)
avgLoss = rma(loss, 14)
rs = avgGain / avgLoss
rsi = 100 - (100 / (1 + rs))

ss_high = max(senkouA[ss_offset-1], senkouB[ss_offset-1])
ss_low = min(senkouA[ss_offset-1], senkouB[ss_offset-1])

// Entry/Exit Signals
tk_cross_bull = tenkan > kijun
tk_cross_bear = tenkan < kijun
cs_cross_bull = mom(haClose, cs_offset-1) > 0
cs_cross_bear = mom(haClose, cs_offset-1) < 0
price_above_kumo = haClose > ss_high
price_below_kumo = haClose < ss_low
rsi_bullish = rsi > 50
rsi_bearish = rs < 50
bullish = tk_cross_bull and cs_cross_bull and price_above_kumo and rsi_bullish //and highvolatility
bearish = tk_cross_bear and cs_cross_bear and price_below_kumo and rsi_bearish //and highvolatility

strategy.entry("Long", strategy.long, when=bullish and long_entry and time_cond)
strategy.entry("Short", strategy.short, when=bearish and short_entry and time_cond)

strategy.close("Long", when=bearish and not short_entry and time_cond)
strategy.close("Short", when=bullish and not long_entry and time_cond)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Oscillating-Long-Short-RSI-Crypto-Switching-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Ichimoku Kinko Hyo Based BTC Trading StrategyPine Script · Mean reversion · 1d
- Quantitative Support and Resistance Oscillation StrategyPine Script · Mean reversion · 1h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d