Parabola Oscillator Seeking Highs and Lows Strategy
This strategy identifies price highs and lows by calculating moving averages and variances over different time periods to determine trend and volatility.
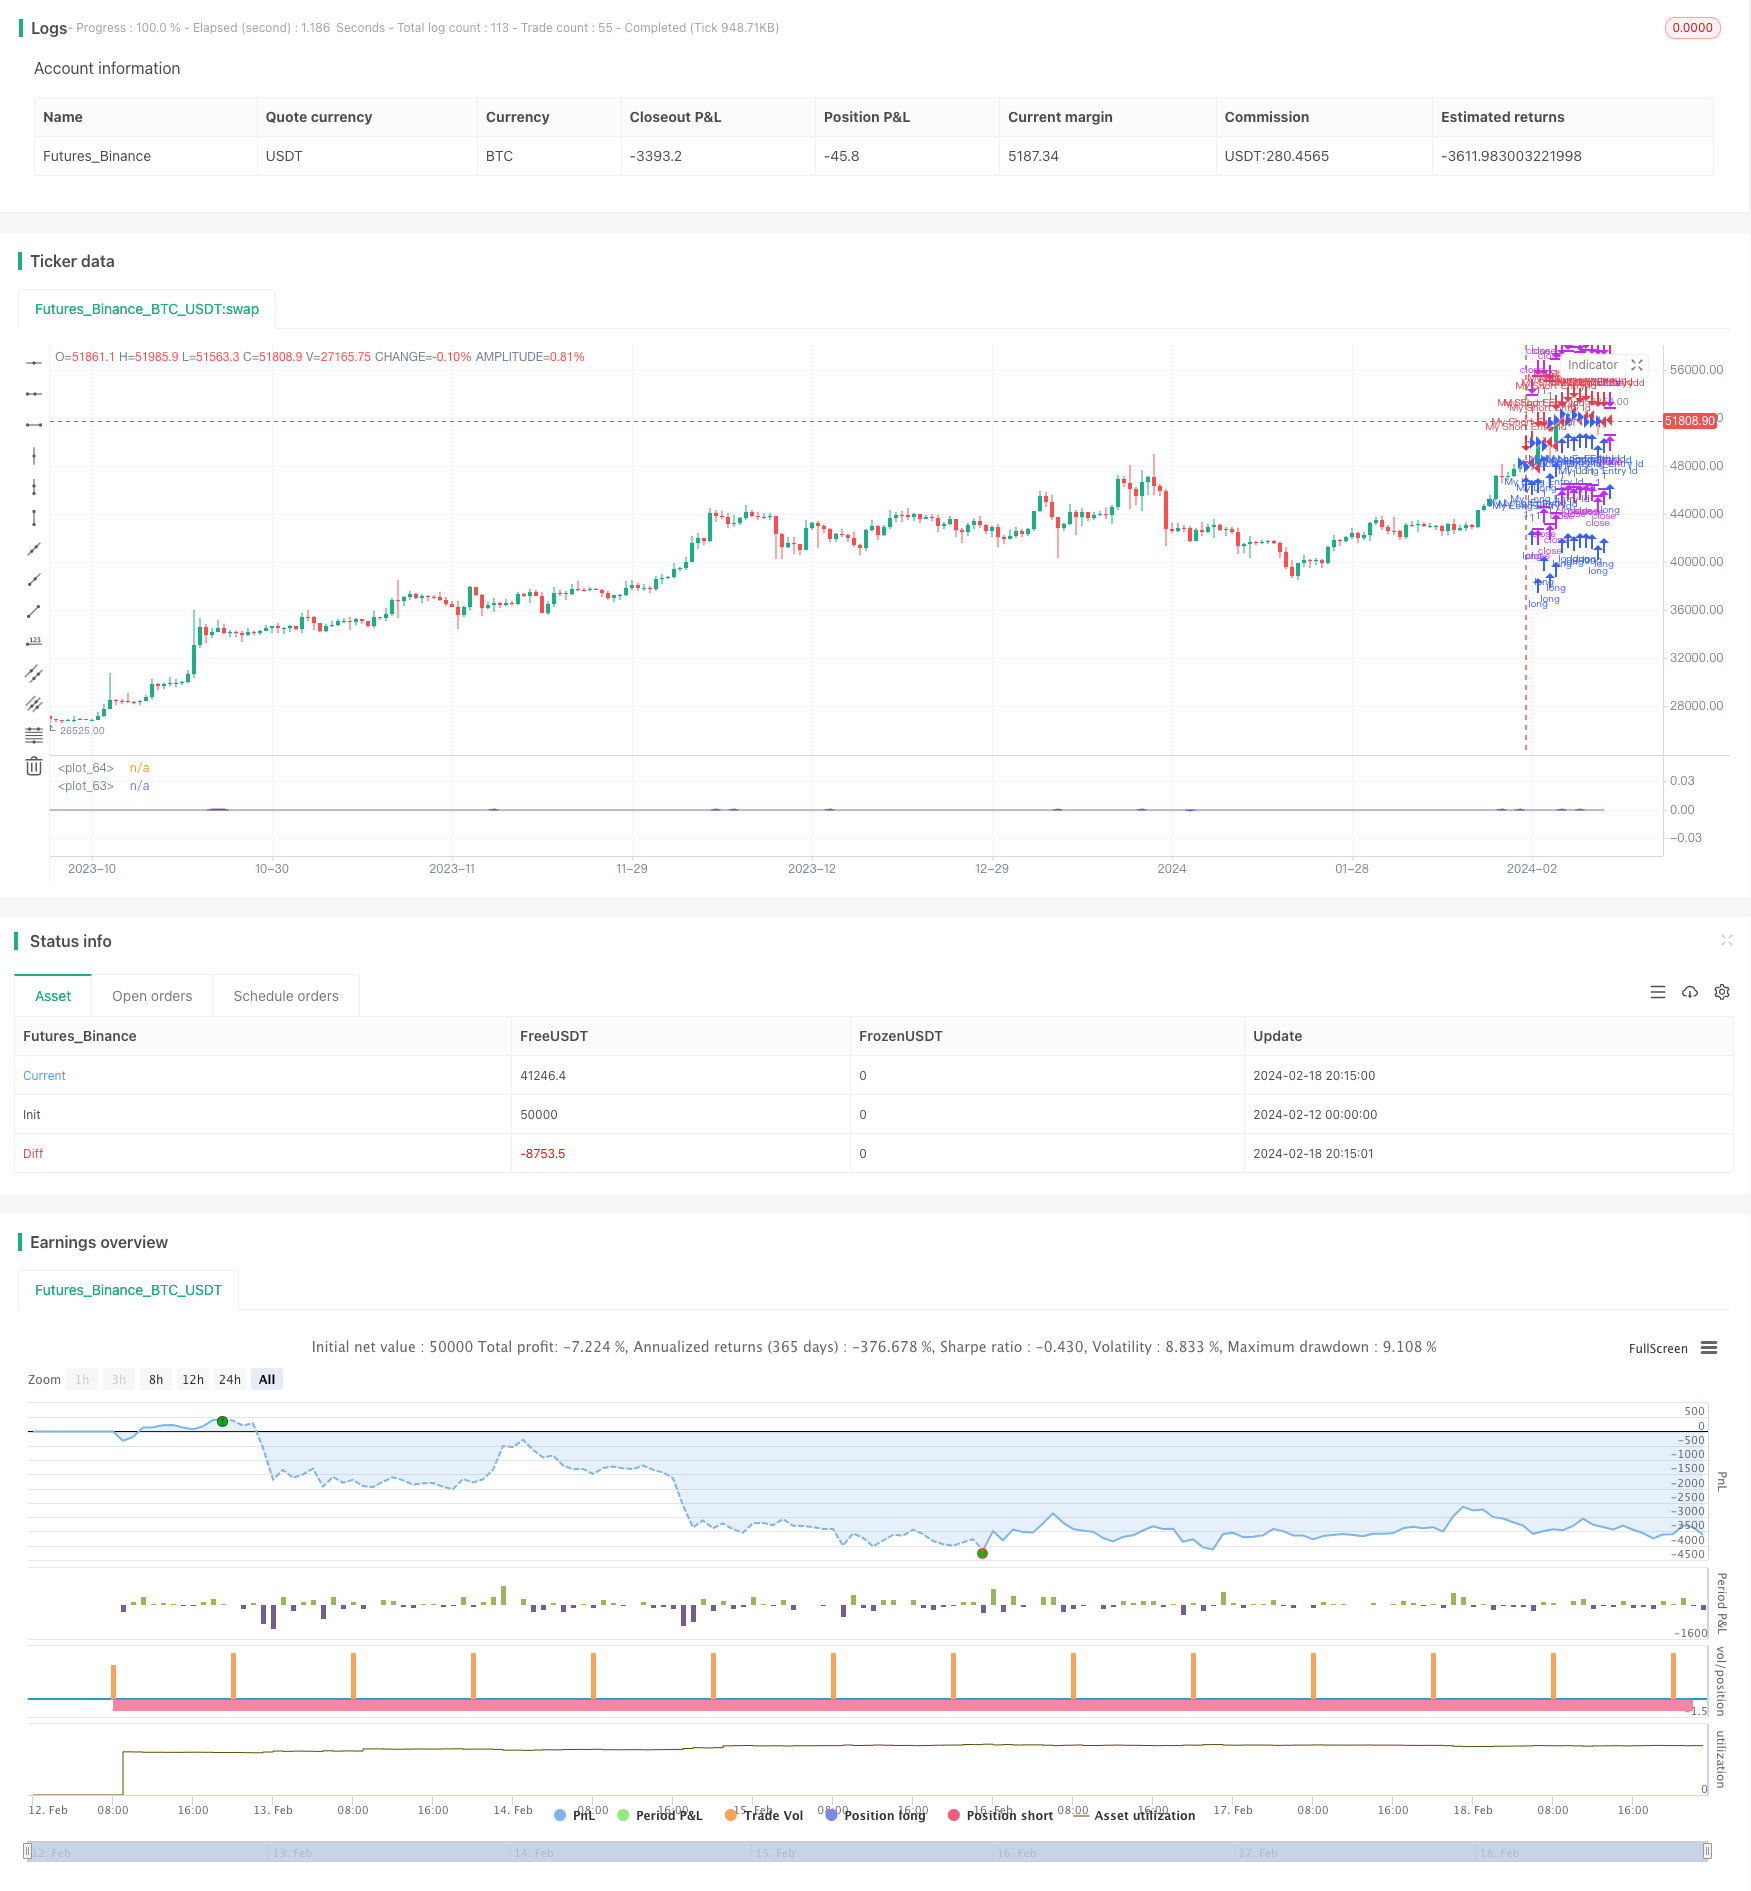
Overview
This strategy identifies price highs and lows by calculating moving averages and variances over different time periods to determine trend and volatility.
Strategy Logic
The core logic of this strategy is to compute moving averages and variances over recent different time periods. Specifically, it calculates 5-day, 4-day and 3-day moving averages (ma, mb, mc) and variances (da, db, dc). It then compares the sizes and selects the period with the highest variance to represent the current trend. Finally, it multiplies the squared variance of the representative period by its moving average to output the final curve wg.
Thus, when price breaks out upward or downward, the representative period and its variance will change significantly, causing wg to change markedly as well, achieving identification of highs and lows.
Advantage Analysis
This idea of judging trend changes based on different periods is effective and can clearly identify price inflection points. Compared to single period judgment, combining multiple periods can improve accuracy and timeliness.
Calculating moving average and variance is also simple and efficient. With small code size, it is highly sensitive to sudden price changes and can detect breakouts quickly.
Risk Analysis
The periods used in this strategy are short. For mid- to long-term purposes, the judgment may not be accurate and comprehensive enough. Short-term price fluctuations may cause misjudgments.
Also, the weighting of moving averages and variances affects the judgment results. If set improperly, the signals could be biased.
Optimization Directions
More time periods of different lengths could be added to form a combination to make the judgment more comprehensive, e.g. 10-day, 20-day for mid- to long-term purposes.
Different schemes of weights could also be tested to make the weighting setting more flexible. Parameter optimization could be introduced to auto-adjust the weights based on market conditions to reduce misjudgment probability.
In addition, other indicators could be incorporated, like abnormal trading volume, to avoid being misled by arbitrage trading.
Conclusion
The overall logic of this strategy is clear and easy to understand, using moving averages and variances to judge price trend and volatility, and then combining them to output a curve that can clearly identify highs and lows. Such multi-period combined judgment can effectively capture both short- and long-term market characteristics, improving the accuracy of inflection point detection. There is also large room for optimization, from aspects like periods, weights and indicators etc, to make the strategy more robust and comprehensive.
Source Pine Script
/*backtest
start: 2024-02-12 00:00:00
end: 2024-02-19 00:00:00
period: 12h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("x²", overlay=false)


a1=(close[2]-close[3])/1
a2=(close[1]-close[3])/4
a3=(close[0]-close[3])/9

b1=(close[3]-close[4])/1
b2=(close[2]-close[4])/4
b3=(close[1]-close[4])/9
b4=(close[0]-close[4])/16

c1=(close[4]-close[5])/1
c2=(close[3]-close[5])/4
c3=(close[2]-close[5])/9
c4=(close[1]-close[5])/16
c5=(close[0]-close[5])/25

ma=(a1+a2+a3)/3
da=(a1-ma)*(a1-ma)
da:=da+(a2-ma)*(a2-ma)
da:=da+(a3-ma)*(a3-ma)
da:=sqrt(da)
da:=min(2, da)
da:=1-da/2
da:=max(0.001, da)


mb=(b1+b2+b3+b4)/4
db=(b1-mb)*(b1-mb)
db:=db+(b2-mb)*(b2-mb)
db:=db+(b3-mb)*(b3-mb)
db:=db+(b4-mb)*(b4-mb)
db:=sqrt(db)
db:=min(2, db)
db:=1-db/2
db:=max(0.001, db)

mc=(c1+c2+c3+c4+c5)/5
dc=(c1-mc)*(c1-mc)
dc:=dc+(c2-mc)*(c2-mc)
dc:=dc+(c3-mc)*(c3-mc)
dc:=dc+(c4-mc)*(c4-mc)
dc:=dc+(c5-mc)*(c5-mc)
dc:=sqrt(dc)
dc:=min(2, dc)
dc:=1-dc/2
dc:=max(0.001, dc)


g=close
if(da>db and da>dc)
    g:=da*da*ma
else
    if(db > da and db > dc)
        g:=db*db*mb
    else
        g:=dc*dc*mc

wg=wma(g, 2)
plot(wg)
plot(0, color=black)


longCondition = true //crossover(sma(close, 14), sma(close, 28))
if (longCondition)
    strategy.entry("My Long Entry Id", strategy.long)

shortCondition = true //crossunder(sma(close, 14), sma(close, 28))
if (shortCondition)
strategy.entry("My Short Entry Id", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a spread arbitrage engine with WebSocket order routing and leg-risk controls from strategies/Parabola-Oscillator-Seeking-Highs-and-Lows-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- multiple auxiliary RSI indicator strategyPine Script · Arbitrage · 1d
- Dual Reversal Arbitrage StrategyPine Script · Arbitrage · 1h
- Oscillating Market Long StrategyPine Script · Arbitrage · 1d
- Comparative Relative Strength StrategyPine Script · Arbitrage · 1d
- Cross Cycle Arbitrage Strategy Based on Multiple IndicatorsPine Script · Arbitrage · 1h
- Dual Moving Average Arbitrage StrategyPine Script · Arbitrage · 1h