Strategy vault / Trend following
Percentage Trailing Stop Loss Strategy
The percentage trailing stop loss strategy is a strategy that sets and adjusts stop loss orders based on percentage of the instrument price. It can adjust the stop loss to the entry price after the price reaches a…
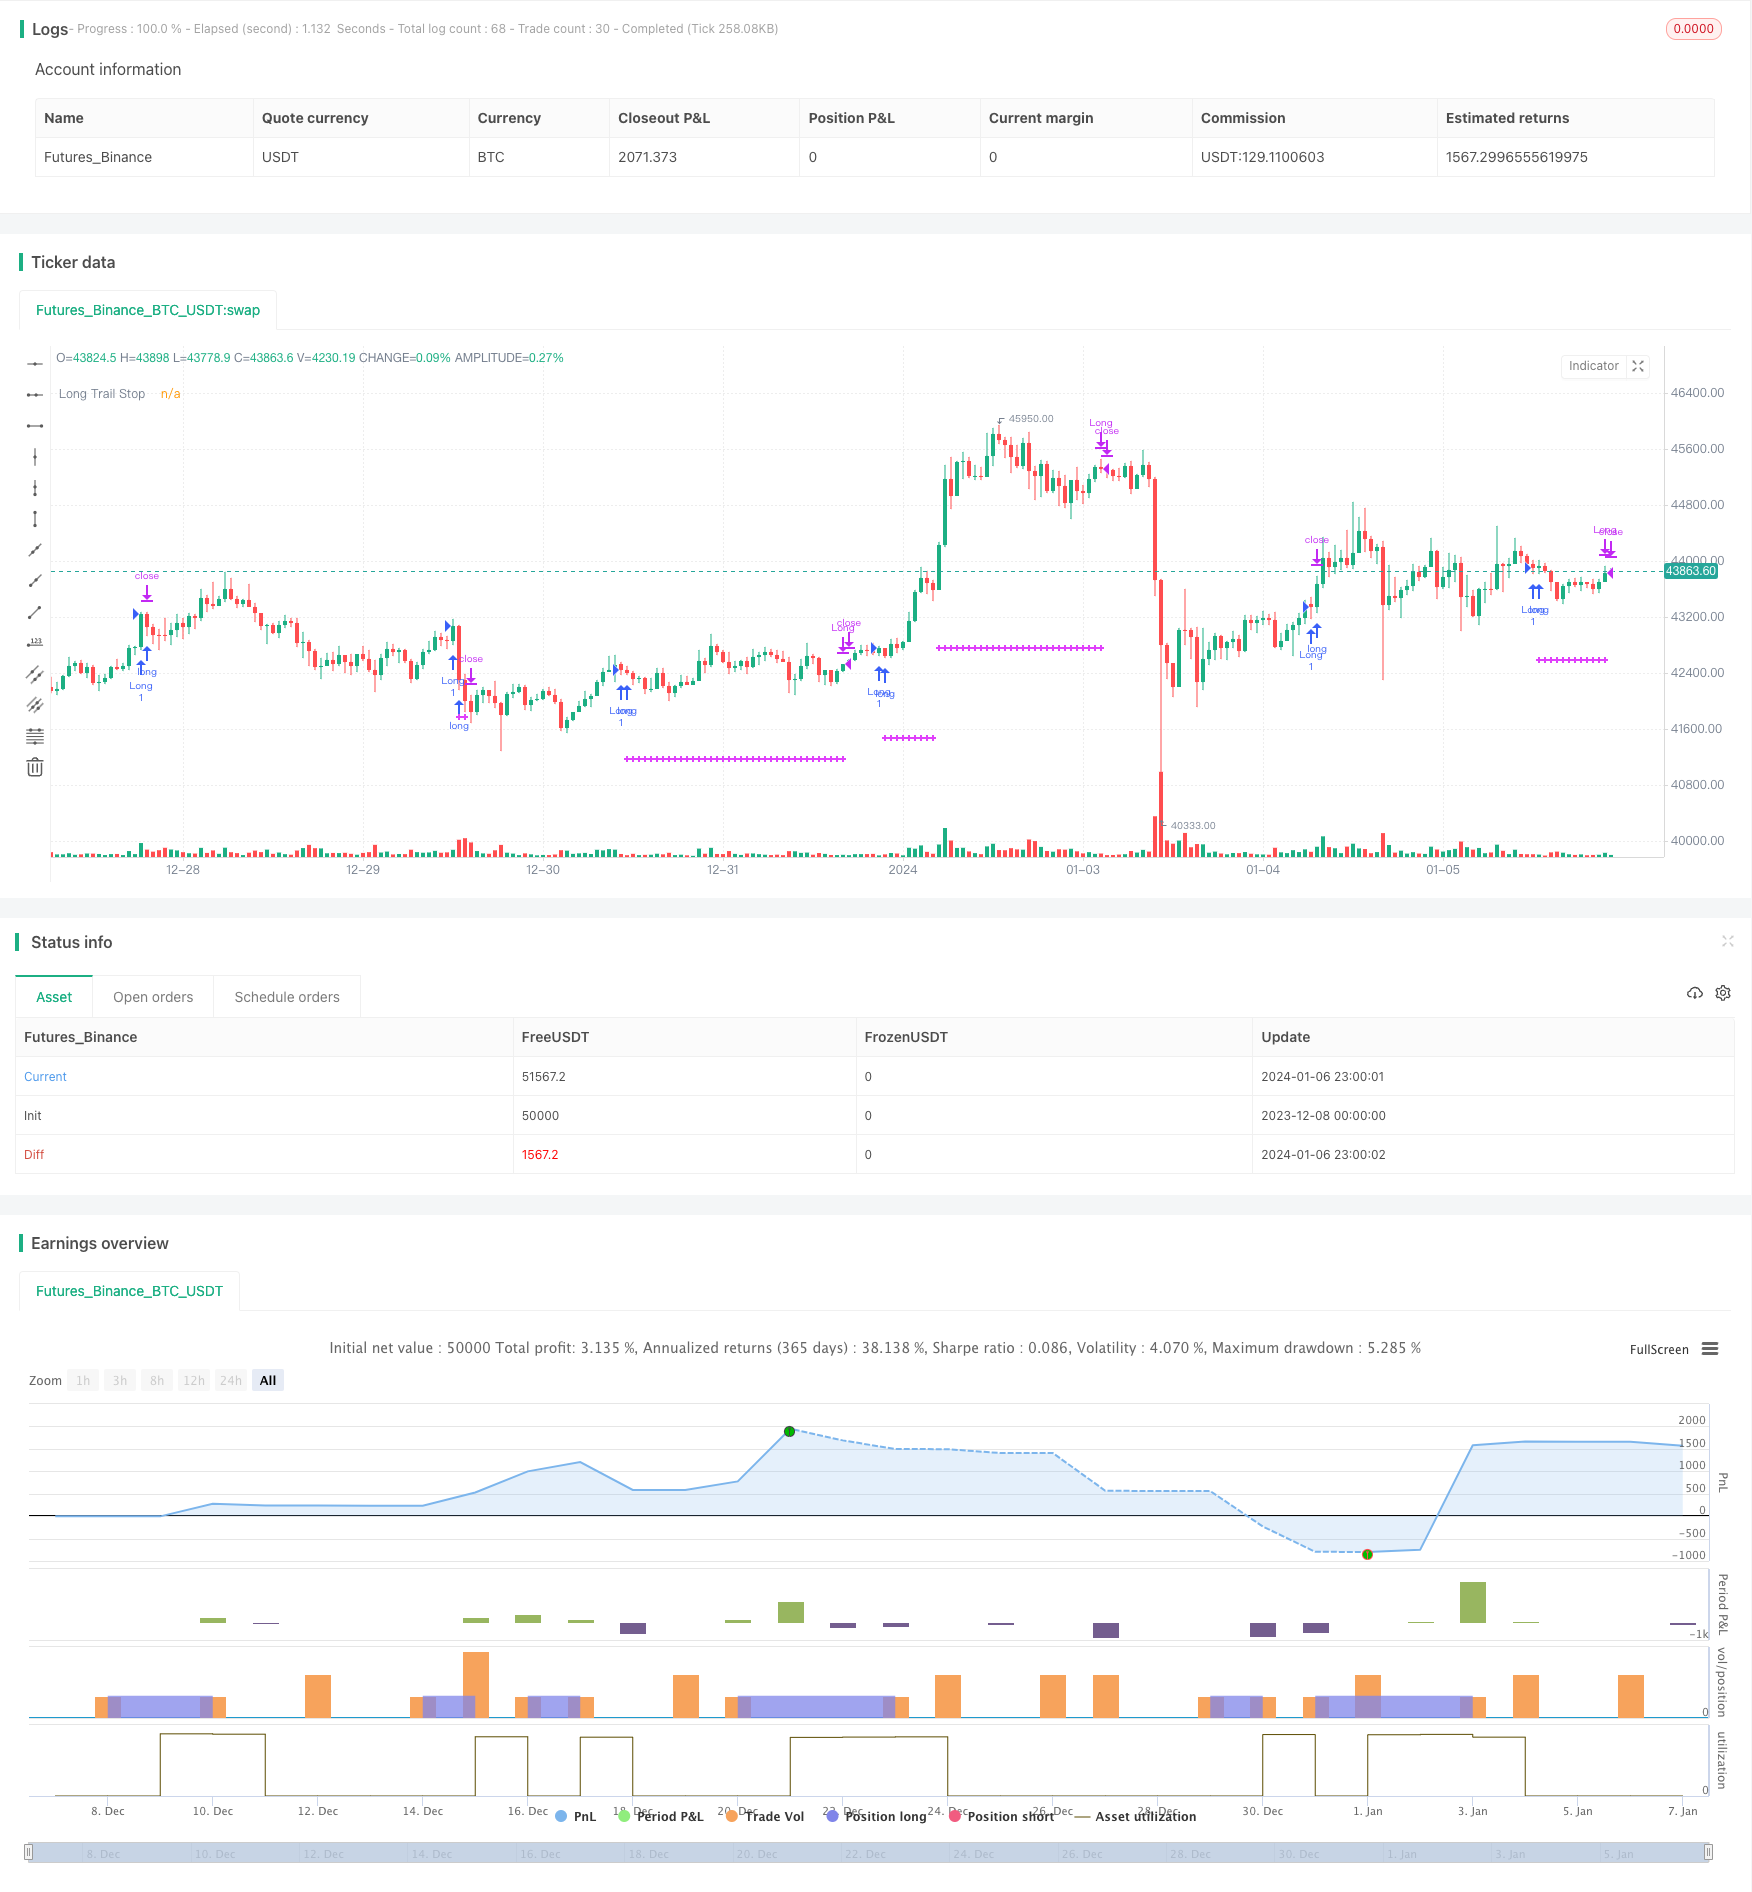
Overview
The percentage trailing stop loss strategy is a strategy that sets and adjusts stop loss orders based on percentage of the instrument price. It can adjust the stop loss to the entry price after the price reaches a certain profitable level to realize breakeven stop loss.
Strategy Logic
This strategy sets the percentage for long position trailing stop loss via input parameters, such as 3%. After opening a position, it calculates the trailing stop loss price in real time. The calculation method is:
When the price exceeds entry price*(1+trailing stop loss percentage), the stop loss price is adjusted to entry price to realize breakeven.
When the price is below the above level, the stop loss price is entry price*(1-trailing stop loss percentage).
This can realize breakeven stop loss when the price reaches a certain profit level, avoiding losing all profits by losses, while preventing too aggressive stop loss from being knocked out by normal price fluctuations.
The strategy also plots the trailing stop loss price for confirmation, and sets to only go long. It goes long on golden cross and closes position on death cross. After going long, it sets trailing stop loss orders to realize the stop loss logic.
Advantage Analysis
The biggest advantage of this strategy is that it can realize breakeven stop loss after making profits through trailing stop loss, no matter how the later market goes, at least the principal can be kept to avoid losses. This is important for many investors.
In addition, the stop loss of this strategy is relatively mild. The trailing stop loss range is not too large, which can prevent being stopped out by normal price fluctuations compared to fixed stop loss. It is more flexible and intelligent.
Risk Analysis
The main risk of this strategy is that if the stop loss percentage is set improperly. If set too small, it would be hard to realize breakeven stop loss. If set too large, it would be easy to be stopped out by normal price fluctuations. So the proper stop loss percentage needs careful testing and evaluation.
Another risk is that in abnormal markets, prices may suddenly gap largely. In this case, stop loss price may not be able to update in time, resulting in invalid stop loss. But the probability is relatively small.
Optimization Directions
This strategy can be optimized in the following aspects:
Add exit rules such as death cross, price breaking through SMA etc. to make the strategy more comprehensive.
Add dynamic adjustment mechanism of stop loss percentage, to automatically optimize stop loss range in different market environments.
Add exit strategies to exit positions after prices running certain range to lock in profits.
Research the differences of stop loss percentage parameters on different instruments, establish parameter self-adaptive optimization mechanism.
Conclusion
The percentage trailing stop loss strategy is very practical overall, which can effectively realize breakeven stop loss after making profits to avoid losses. This strategy has large room for optimization and is worth further researching to improve efficiency. In general, this strategy suits investors pursuing steady investment returns.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | 3 | Trail Long Loss (%) |
Source Pine Script
/*backtest
start: 2023-12-08 00:00:00
end: 2024-01-07 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © osmaras
// based on https://kodify.net/tradingview/orders/percentage-trail/

//@version=5
strategy("Break even stop loss (% of instrument price)", overlay=true)

// Configure trail stop level with input options (optional)
longTrailPerc = input.float(defval=3.0,step=0.1,title="Trail Long Loss (%)")* 0.01
longCondition = ta.crossover(ta.sma(close, 14), ta.sma(close, 28))

// Determine trail stop loss prices
longStopPrice = 0.0
lastEntryPrice = strategy.opentrades.entry_price(strategy.opentrades - 1)
longStopPrice := if (strategy.position_size > 0 and close > (lastEntryPrice * (1 + longTrailPerc)))
    stopValue = lastEntryPrice
    math.max(stopValue, longStopPrice[1])
else
    longStopPrice := if (strategy.position_size > 0)
        stopValue = lastEntryPrice * (1 - longTrailPerc)
        math.max(stopValue, longStopPrice[1])
    else
        0

// Plot stop loss values for confirmation
plot(series=(strategy.position_size > 0) ? longStopPrice : na,
     color=color.fuchsia, style=plot.style_cross,
     linewidth=2, title="Long Trail Stop")

// set strategy only long
strategy.risk.allow_entry_in(strategy.direction.long)

// Submit entry orders
if (longCondition)
    strategy.entry("Long", strategy.long)

shortCondition = ta.crossunder(ta.sma(close, 14), ta.sma(close, 28))
if (shortCondition)
    strategy.close("Long")


// Submit exit orders for trail stop loss price
if (strategy.position_size > 0)
    strategy.exit(id="Stop Loss", stop=longStopPrice)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Percentage-Trailing-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m