Strategy vault / Mean reversion
PercentR Reversa Channe Strategy
This is a reversal trading strategy based on the Laruent Channel indicator. It calculates the highest and lowest prices over a certain period of time in the past to determine if the current price is in the overbought…
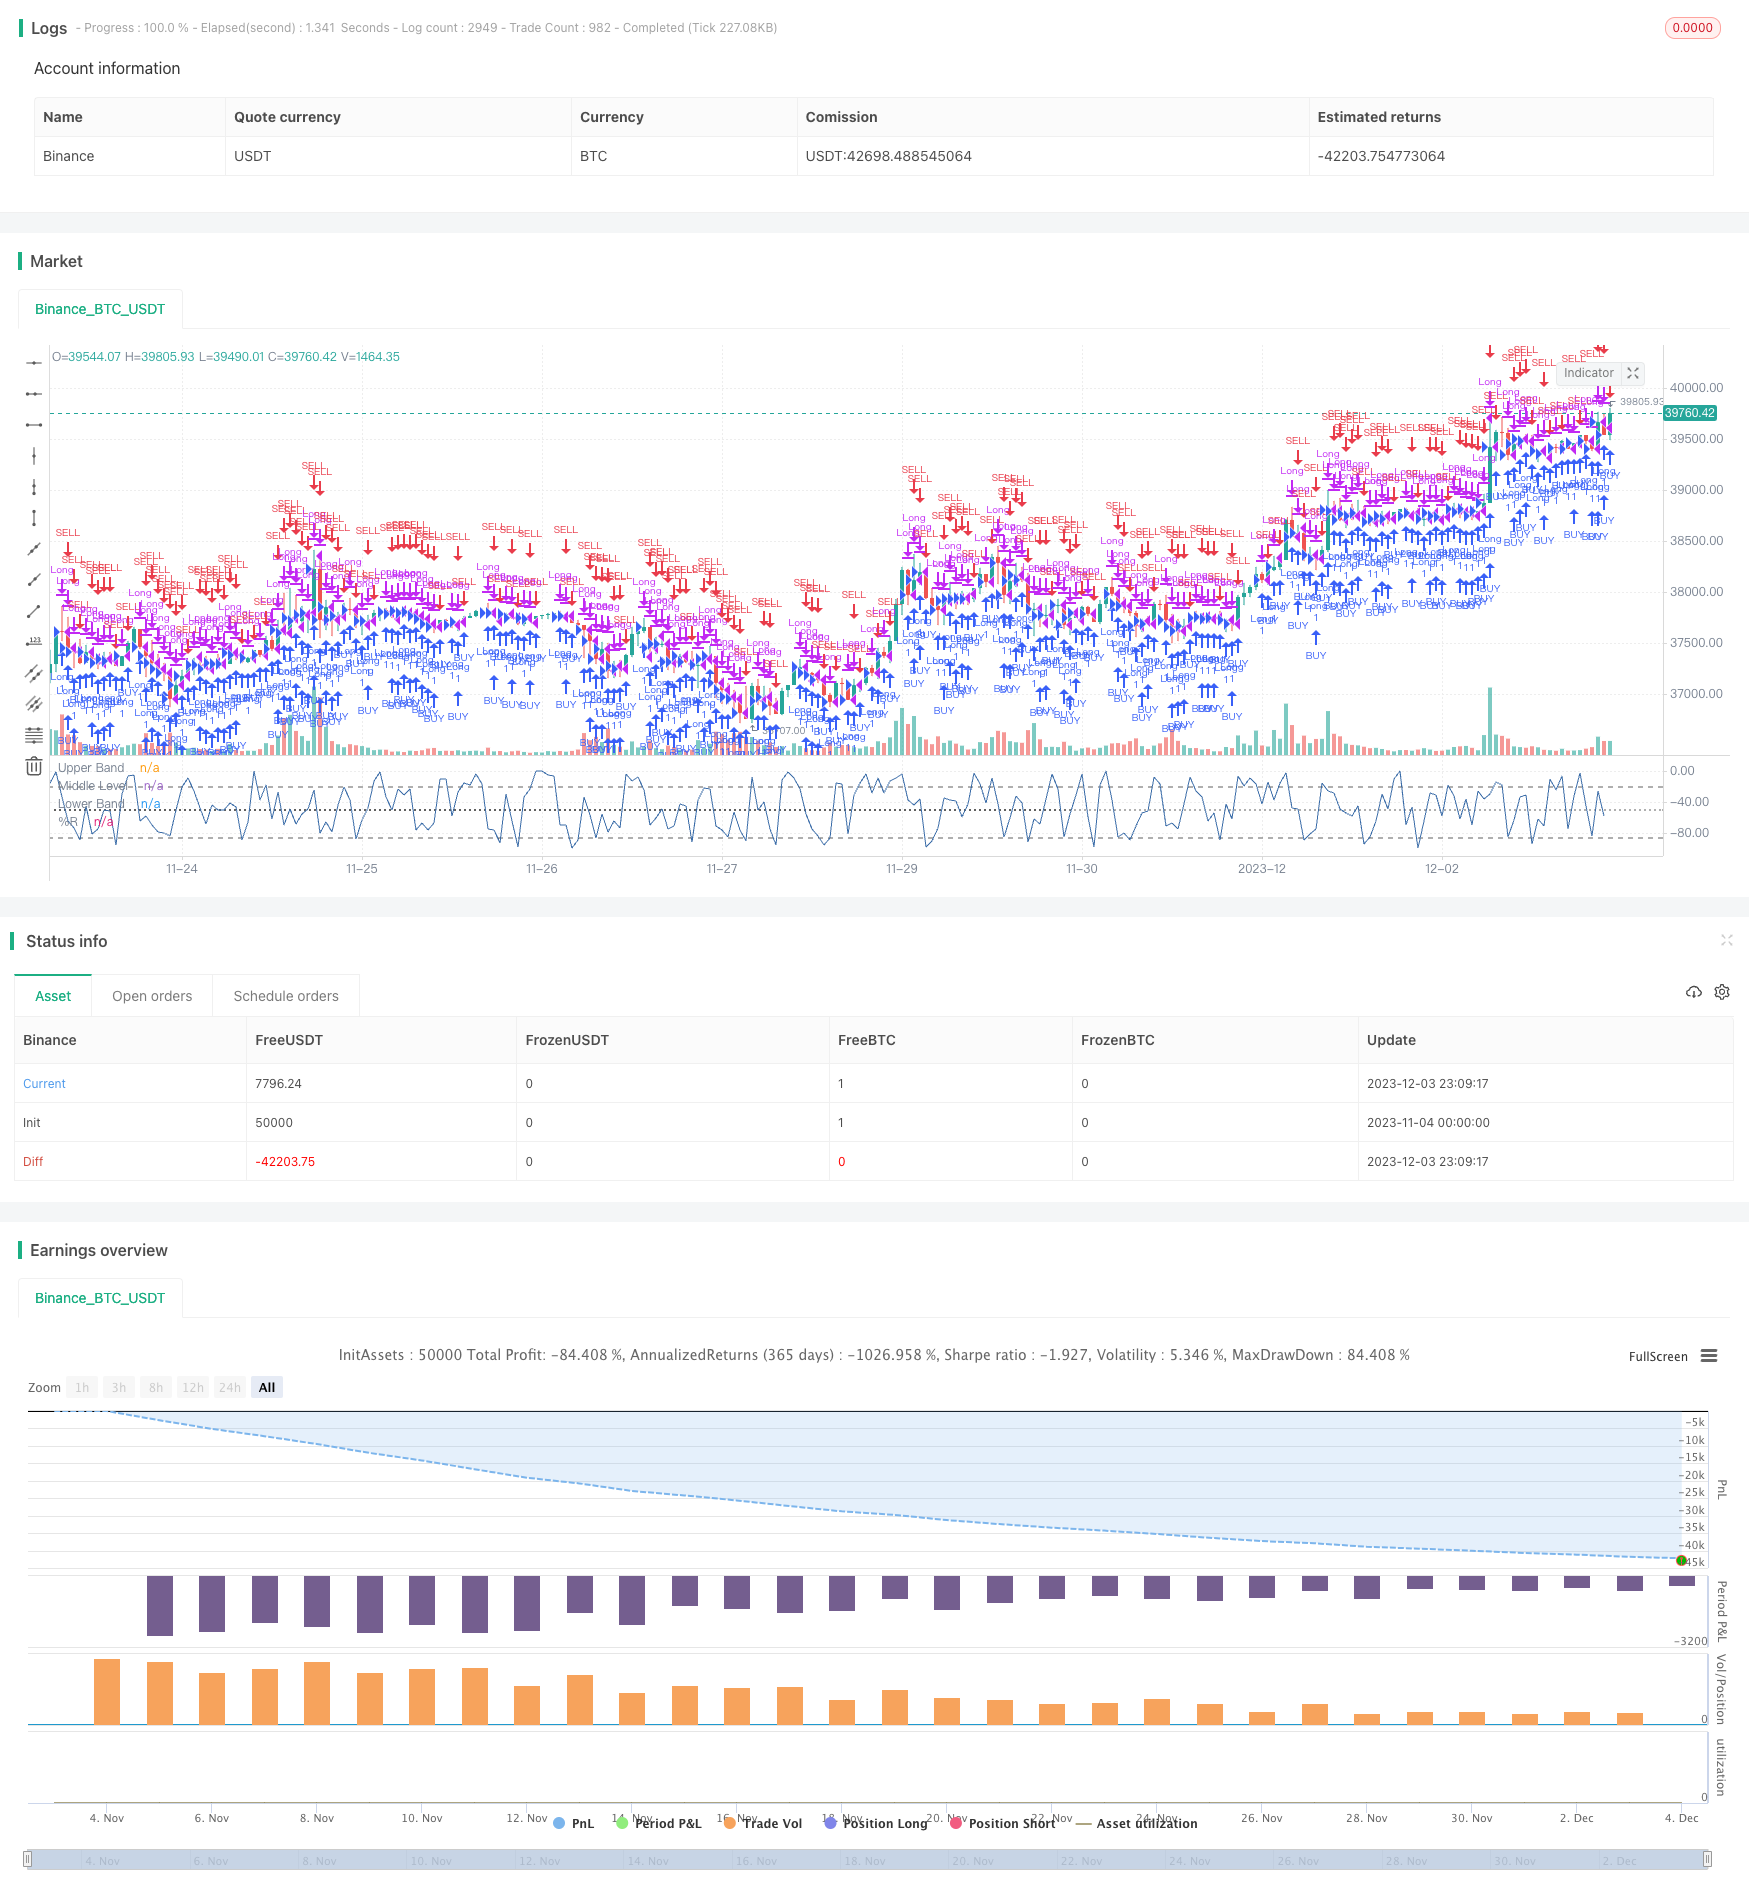
Strategy Overview
This is a reversal trading strategy based on the Laruent Channel indicator. It calculates the highest and lowest prices over a certain period of time in the past to determine if the current price is in the overbought or oversold area. If the price is close to the upper or lower rail, it will open a position in the opposite direction and wait for the price to return to the middle line.
Strategy Principle
The strategy is mainly based on two indicators: PercentR indicator (%R) and Laruent Channel rails.
The PercentR indicator shows the distance between the current closing price and the highest and lowest prices over the most recent period. The value range is from 0 to -100. A value close to 0 means the current closing price is near the highest point recently. And a value close to -100 means the current closing price is near the lowest price recently.
The Laruent Channel consists of upper rail, middle line and lower rail. The upper rail equals the highest price over the most recent period. The lower rail equals the lowest price over that period. The middle line is the mean of the upper and lower rails. If the price exceeds the upper rail, it is considered overbought. If the price is below the lower rail, it is considered oversold.
The strategy first calculates the PercentR indicator and Laruent Channel rails, then uses the two indicators to determine if the current status is overbought or oversold:
- When PercentR is below -87, the status is considered oversold.
- When PercentR is above -20, the status is considered overbought.
If the current status is neither overbought nor oversold, it will long at market open. And close the position before market close on the same day.
By capturing the price reversal, it can make profits in short term.
Advantages
- The strategy is simple and clear, easy to understand and implement.
- Using PercentR indicator to judge overbought/oversold status is reliable.
- Making orders at market open and closing positions before market close avoids overnight risk.
- As a reversal trading strategy, it is suitable for short term profit making.
Risks
- Failed reversal, cannot exit with profit.
- Improper parameter settings, cannot judge overbought/oversold status correctly.
- Too short intraday trading time, fewer trading signals.
Risks can be reduced by optimizing parameters, adjusting order placement time, or combining with other indicators.
Optimization
- A stop loss mechanism can be introduced to set a stop loss line to avoid loss expansion.
- The parameters of PercentR can be optimized to make overbought/oversold judgment more accurate.
- The strategy can be used on multiple timeframes simultaneously to implement multi-timeframe trading.
- It can be combined with other indicators like KDJ, MACD to make trading signals more reliable.
Summary
In general, this strategy is quite simple and practical. It is designed based on the reversal trading idea and suitable for short term frequent trading. There is large room for optimization. More technical indicators can be introduced for combination. And automatic stop loss mechanisms can also be established to control risks.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | -87 | Low Marker |
| v_input_2 | -20 | High Marker |
| v_input_3 | 3 | Length |
| v_input_4_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
Source Pine Script
/*backtest
start: 2023-11-04 00:00:00
end: 2023-12-04 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Binance","currency":"BTC_USDT"}]
*/

//@version=4
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © zweiprozent original strategy by larry williams

strategy("Daily PercentR Strategy", overlay=false)
D_High = security(syminfo.tickerid, 'D', high[1])
D_Low = security(syminfo.tickerid, 'D', low[1])
D_Close = security(syminfo.tickerid, 'D', close[1])
D_Open = security(syminfo.tickerid, 'D', open[1])

LowMarker = input(-87,"Low Marker",input.integer)

HighMarker =  input(-20,"High Marker",input.integer)

length = input(title="Length", type=input.integer, defval=3)
src = input(close, "Source", type = input.source)
_pr(length) =>
	max = highest(length)
	min = lowest(length)
	100 * (src - max) / (max - min)
percentR = _pr(length)
obPlot = hline(LowMarker, title="Upper Band", color=#606060)
hline(-50, title="Middle Level", linestyle=hline.style_dotted, color=#606060)
osPlot = hline(HighMarker, title="Lower Band", color=#606060)
fill(obPlot, osPlot, title="Background", color=color.new(#9915ff, 90))
plot(percentR, title="%R", color=#3A6CA8, transp=0)

// Go Long - if percentR is not overbought/sold

ordersize=floor(strategy.equity/close)

if percentR<HighMarker and percentR>LowMarker
    strategy.entry("Long", strategy.long,comment="Long")

//exit at end of session
if low[0]<high[0]
    strategy.close("Long", comment="exit")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/PercentR-Reversa-Channe-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 1 2 3 Pattern Quantitative Trading Strategy with EMAs MACD and 4th Candle ExtensionPine Script · Mean reversion · 1h
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Moving Average Tracking StrategyPine Script · Mean reversion · 1d