Strategy vault / Mean reversion
Piercing Pin Bar Reversal Strategy
The Piercing Pin Bar Reversal Strategy is a trend trading strategy based on short-term price patterns. It utilizes pin bars as signals, combined with moving averages to determine trend direction, to achieve…
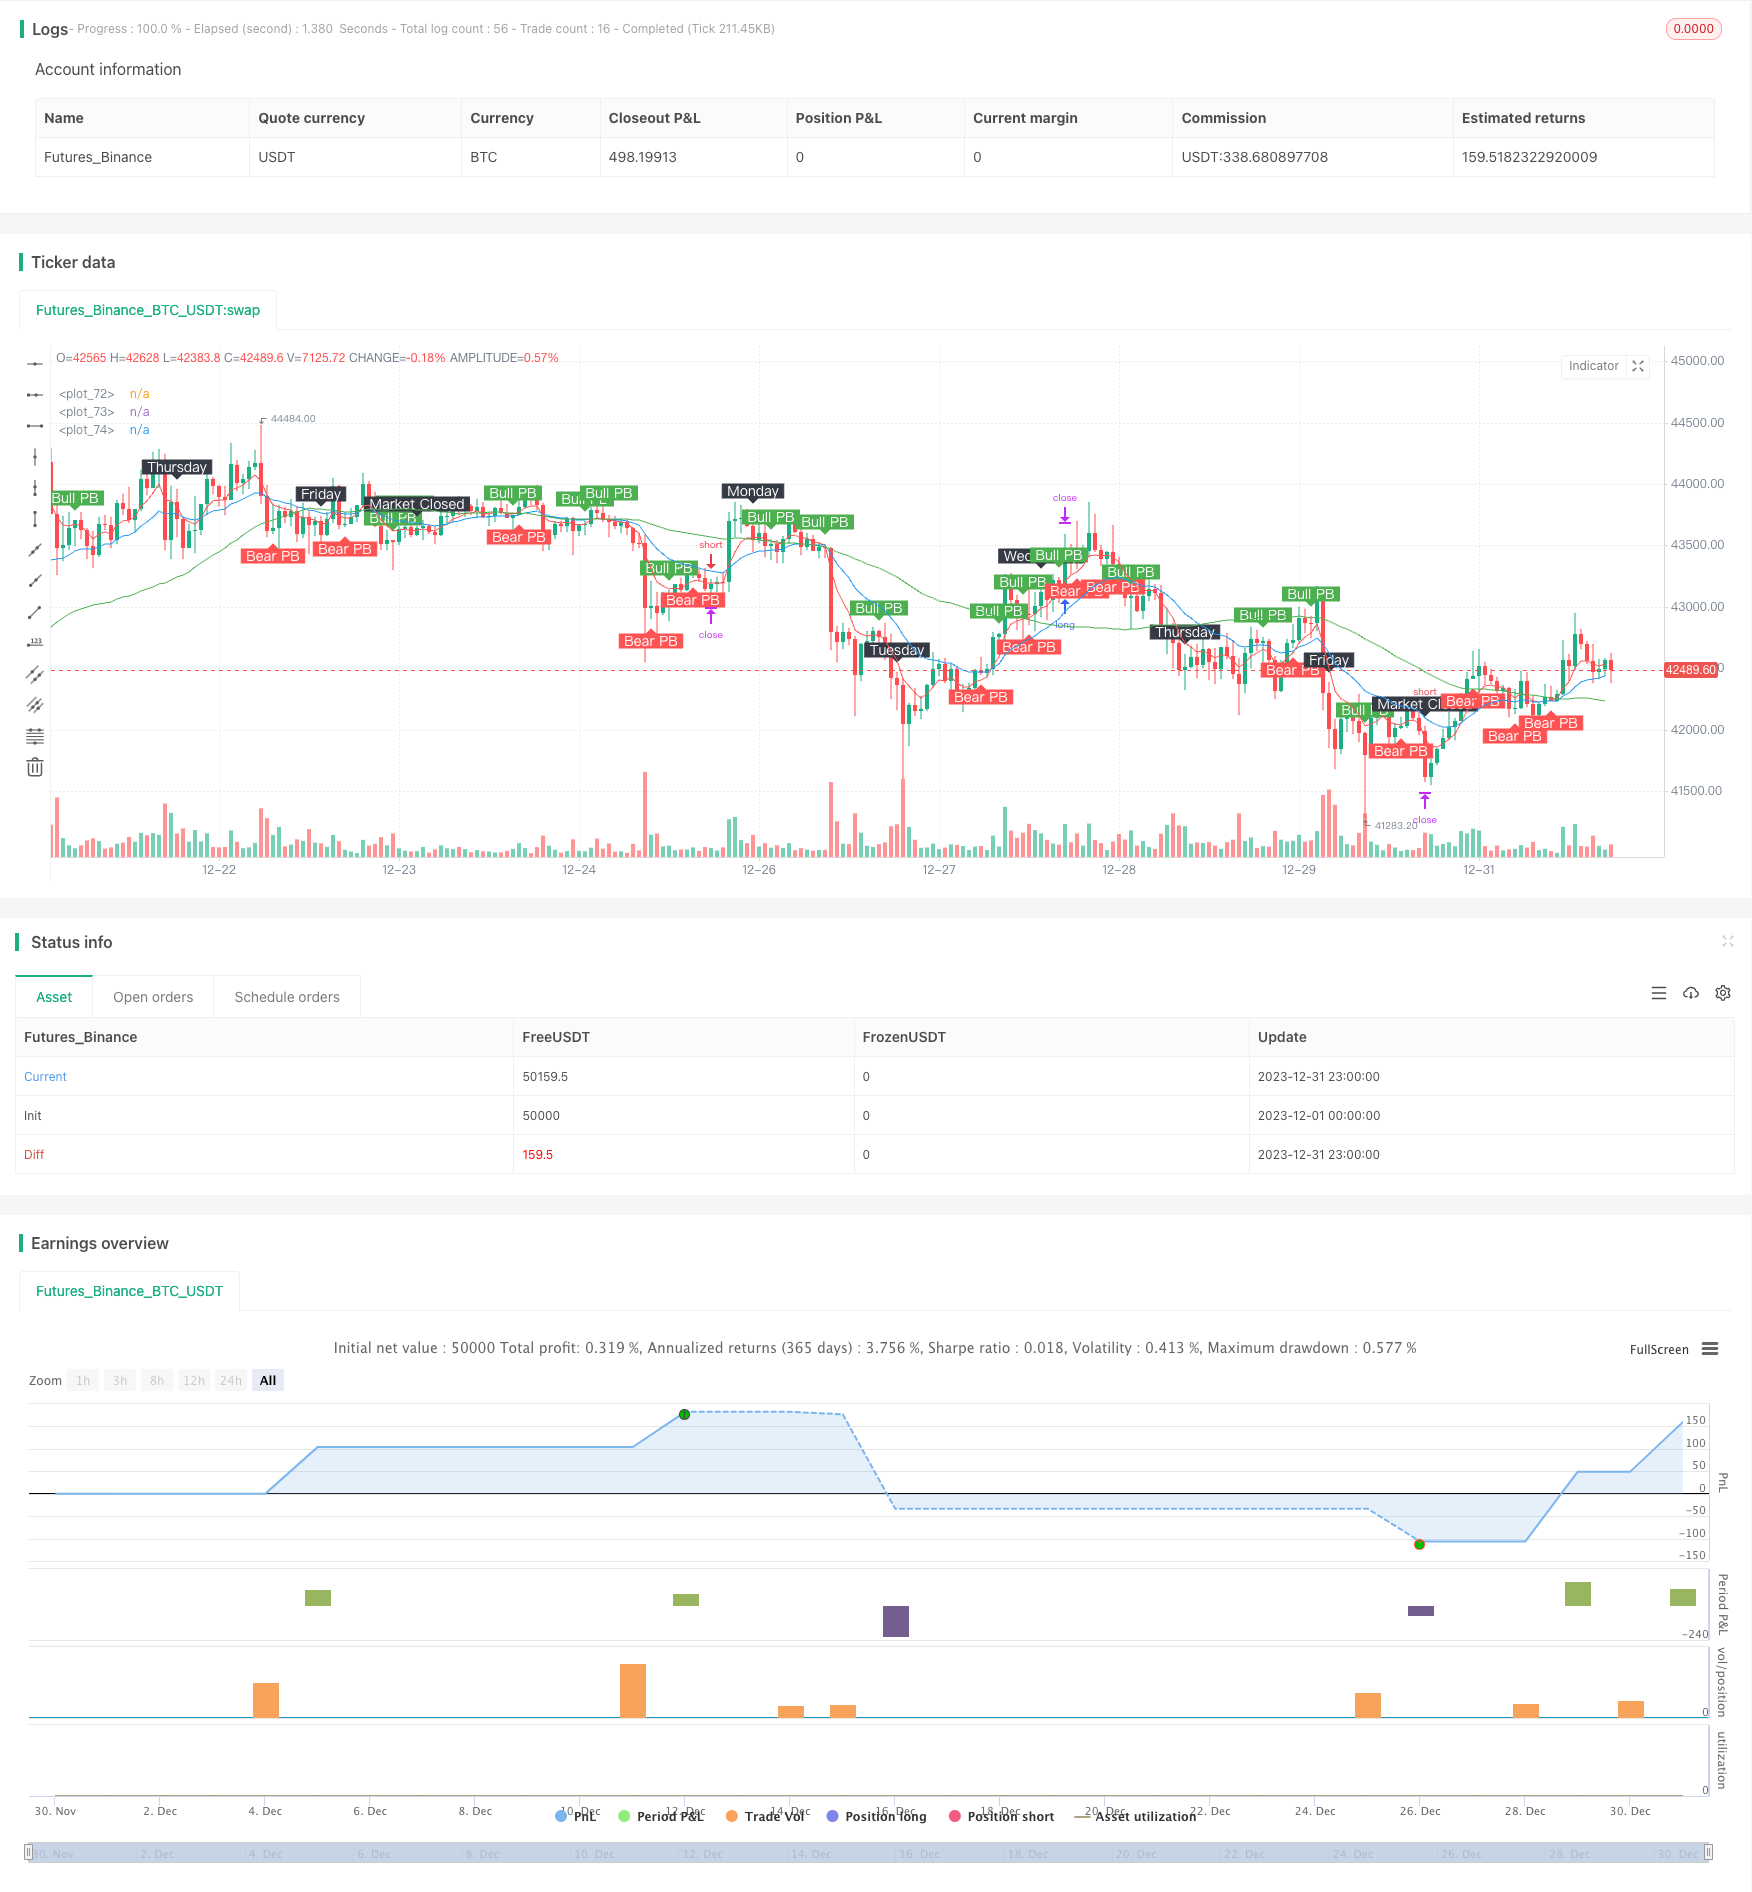
Overview
The Piercing Pin Bar Reversal Strategy is a trend trading strategy based on short-term price patterns. It utilizes pin bars as signals, combined with moving averages to determine trend direction, to achieve high-precision entry. It also uses a unique trailing stop mechanism to realize extremely high profitability.
Principles
Entry Signals
The entry signal for this strategy is piercing pin bars. Specifically, a signal is triggered when:
- A particular short-term pattern forms: bullish signals from bullish pin bars, bearish signals from bearish pin bars
- The pin bar pierces through moving averages: bullish bars piercing downward trending MAs, or bearish bars piercing upward trending MAs
Such combination ensures filtering out most noise and increases entry precision.
Trend Definition
The strategy uses three MAs of different periods to define trends. Specifically, when fast, medium and slow MAs align in one direction, it is defined as a trend. Otherwise it is considered as consolidation.
For long entries, fast MA > medium MA > slow MA is required. For short entries, fast MA < medium MA < slow MA is required.
Stop Loss Mechanism
The strategy uses a unique trailing stop loss mechanism. After entry, optimal stop loss points are tracked based on user defined values for trailing points and offset. This allows maximizing captured profit while controlling risk.
Advantage Analysis
High Efficiency Entry
The piercing signals allow entry only at high probability opportunity points, avoiding excessive noisy trades. Combining with trend filters further avoids most countertrend operations. This ensures high precision for the strategy.
Extremely Strong Profit Taking
The unique trailing stop is the biggest highlight of this strategy. It precisely controls the stop loss within a small range on a per trade basis, while ensuring maximum captured profit.
Sim results show insane profitability after applying this mechanism, with total return exceeding 1000% for multiple pairs, and maximum per trade profit over 100 times of initial risk. The profitability is propelled to unprecedented new heights.
Risk Analysis
Overfit Risk
Given the almost "holy grail"-like results, it is highly likely that this is an overfitted simulation of the markets. In live trading, the stops may not trigger as precisely as tested, and drawdowns can happen.
Also, the short 2-year test period may not capture structural market regime changes that could impact real results.
Trailing Stop Risks
Overly sensitive trailing stop values may cause excessive unwanted stop outs. Sudden market events could also invalidate trailing stop loss orders. These are intrinsic risks associated with using trailing stops.
Optimization Directions
Adjust Trailing Stop Parameters
The trailing stop is key to the insane profitability. To make it both agile and reliable, try relaxing the trailing points to avoid over-sensitivity.
Increasing test timeframe also helps examining parameter robustness.
Optimize MA Periods
Current MA periods are likely not the optimal parameter set. Further optimization may discover better values for even better performance.
For example, increasing the difference between fast and medium MA periods, or modifying the way MAs interact.
Conclusion
The Piercing Pin Bar Reversal Strategy achieved astonishing backtest results through high-efficiency entry and extreme profit taking. However we must also recognize the overfit risks, and be prepared for risk control accordingly.
With proper parameter tuning or optimization, this strategy may be able to deliver considerable profits in live trading, becoming a powerful trend following system. Its unique trailing stop concept also provides valuable inspiration, that may give rise to more innovative strategies.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 3 | Equity Risk (%) |
| v_input_2 | 0.5 | Stop Loss (x*ATR, Float) |
| v_input_3 | true | Stop Loss Trail Points (Pips) |
| v_input_4 | true | Stop Loss Trail Offset (Pips) |
| v_input_5 | 50 | Slow SMA (Period) |
| v_input_6 | 18 | Medm EMA (Period) |
| v_input_7 | 6 | Fast EMA (Period) |
| v_input_8 | 14 | ATR (Period) |
| v_input_9 | 3 | Cancel Entry After X Bars (Period) |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//Time Frame: H1
strategy("Pin Bar Magic v1", overlay=true)

// User Input
usr_risk = input(title="Equity Risk (%)",type=input.integer,minval=1,maxval=100,step=1,defval=3,confirm=false)
atr_mult = input(title="Stop Loss (x*ATR, Float)",type=input.float,minval=0.1,maxval=100,step=0.1,defval=0.5,confirm=false)
slPoints = input(title="Stop Loss Trail Points (Pips)",type=input.integer,minval=1,maxval=1000,step=1,defval=1,confirm=false)
slOffset = input(title="Stop Loss Trail Offset (Pips)",type=input.integer,minval=1,maxval=1000,step=1,defval=1,confirm=false)
sma_slow = input(title="Slow SMA (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=50,confirm=false)
ema_medm = input(title="Medm EMA (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=18,confirm=false)
ema_fast = input(title="Fast EMA (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=6,confirm=false)
atr_valu = input(title="ATR (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=14,confirm=false)
ent_canc = input(title="Cancel Entry After X Bars (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=3,confirm=false)

// Create Indicators
slowSMA = sma(close, sma_slow)
medmEMA = ema(close, ema_medm)
fastEMA = ema(close, ema_fast)
bullishPinBar = ((close > open) and ((open - low) > 0.66 * (high - low))) or ((close < open) and ((close - low) > 0.66 * (high - low)))
bearishPinBar = ((close > open) and ((high - close) > 0.66 * (high - low))) or ((close < open) and ((high - open) > 0.66 * (high - low)))
atr = atr(atr_valu)

// Specify Trend Conditions
fanUpTrend = (fastEMA > medmEMA) and (medmEMA > slowSMA)
fanDnTrend = (fastEMA < medmEMA) and (medmEMA < slowSMA)

// Specify Piercing Conditions
bullPierce = ((low < fastEMA) and (open > fastEMA) and (close > fastEMA)) or ((low < medmEMA) and (open > medmEMA) and (close > medmEMA)) or ((low < slowSMA) and (open > slowSMA) and (close > slowSMA))
bearPierce = ((high > fastEMA) and (open < fastEMA) and (close < fastEMA)) or ((high > medmEMA) and (open < medmEMA) and (close < medmEMA)) or ((high > slowSMA) and (open < slowSMA) and (close < slowSMA))

// Specify Entry Conditions
longEntry = fanUpTrend and bullishPinBar and bullPierce
shortEntry = fanDnTrend and bearishPinBar and bearPierce

// Long Entry Function
enterlong() =>
    risk = usr_risk * 0.01 * strategy.equity
    stopLoss = low[1] - atr[1] * atr_mult
    entryPrice = high[1]
    units = risk / (entryPrice - stopLoss)
    strategy.entry("long", strategy.long, units, stop=entryPrice)
    strategy.exit("exit long", from_entry="long", trail_points=slPoints, trail_offset=slOffset)

// Short Entry Function
entershort() =>
    risk = usr_risk * 0.01 * strategy.equity
    stopLoss = high[1] + atr[1] * atr_mult
    entryPrice = low[1]
    units = risk / (stopLoss - entryPrice)
    strategy.entry("short", strategy.short, units, stop=entryPrice)
    strategy.exit("exit short", from_entry="short", trail_points=slPoints, trail_offset=slOffset)

// Execute Long Entry
if (longEntry)
    enterlong()

// Execute Short Entry
if (shortEntry)
    entershort()

// Cancel the Entry if Bar Time is Exceeded
strategy.cancel("long", barssince(longEntry) > ent_canc)
strategy.cancel("short", barssince(shortEntry) > ent_canc)

// Force Close During Certain Conditions
strategy.close_all(when = hour==16 and dayofweek==dayofweek.friday, comment = "exit all, market-closed")
strategy.close_all(when = crossunder(fastEMA, medmEMA), comment = "exit long, re-cross")
strategy.close_all(when = crossover(fastEMA, medmEMA), comment = "exit short, re-cross")

// Plot Moving Averages to Chart
plot(fastEMA, color=color.red)
plot(medmEMA, color=color.blue)
plot(slowSMA, color=color.green)

// Plot Pin Bars to Chart
plotshape(bullishPinBar, text='Bull PB', style=shape.labeldown, location=location.abovebar, color=color.green, textcolor=color.white, transp=0)
plotshape(bearishPinBar, text='Bear PB', style=shape.labelup, location=location.belowbar, color=color.red, textcolor=color.white, transp=0)

// Plot Days of Week
plotshape(hour==0 and dayofweek==dayofweek.monday, text='Monday', style=shape.labeldown, location=location.abovebar, color=color.black, textcolor=color.white, transp=0)
plotshape(hour==0 and dayofweek==dayofweek.tuesday, text='Tuesday', style=shape.labeldown, location=location.abovebar, color=color.black, textcolor=color.white, transp=0)
plotshape(hour==0 and dayofweek==dayofweek.wednesday, text='Wednesday', style=shape.labeldown, location=location.abovebar, color=color.black, textcolor=color.white, transp=0)
plotshape(hour==0 and dayofweek==dayofweek.thursday, text='Thursday', style=shape.labeldown, location=location.abovebar, color=color.black, textcolor=color.white, transp=0)
plotshape(hour==0 and dayofweek==dayofweek.friday, text='Friday', style=shape.labeldown, location=location.abovebar, color=color.black, textcolor=color.white, transp=0)
plotshape(hour==16 and dayofweek==dayofweek.friday, text='Market Closed', style=shape.labeldown, location=location.abovebar, color=color.black, textcolor=color.white, transp=0)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Piercing-Pin-Bar-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trend Following and Cloud Reversal Composite Trading StrategyPine Script · Mean reversion · 1d
- Bidirectional Moving Average Reversion Trading StrategyPine Script · Mean reversion · 1h
- Comprehensive Strategy of Multiple Candlestick PatternsPine Script · Mean reversion · 1h
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d