Strategy vault / Mean reversion
Pivot Reversal Quantitative Strategy Based on Pivot Points
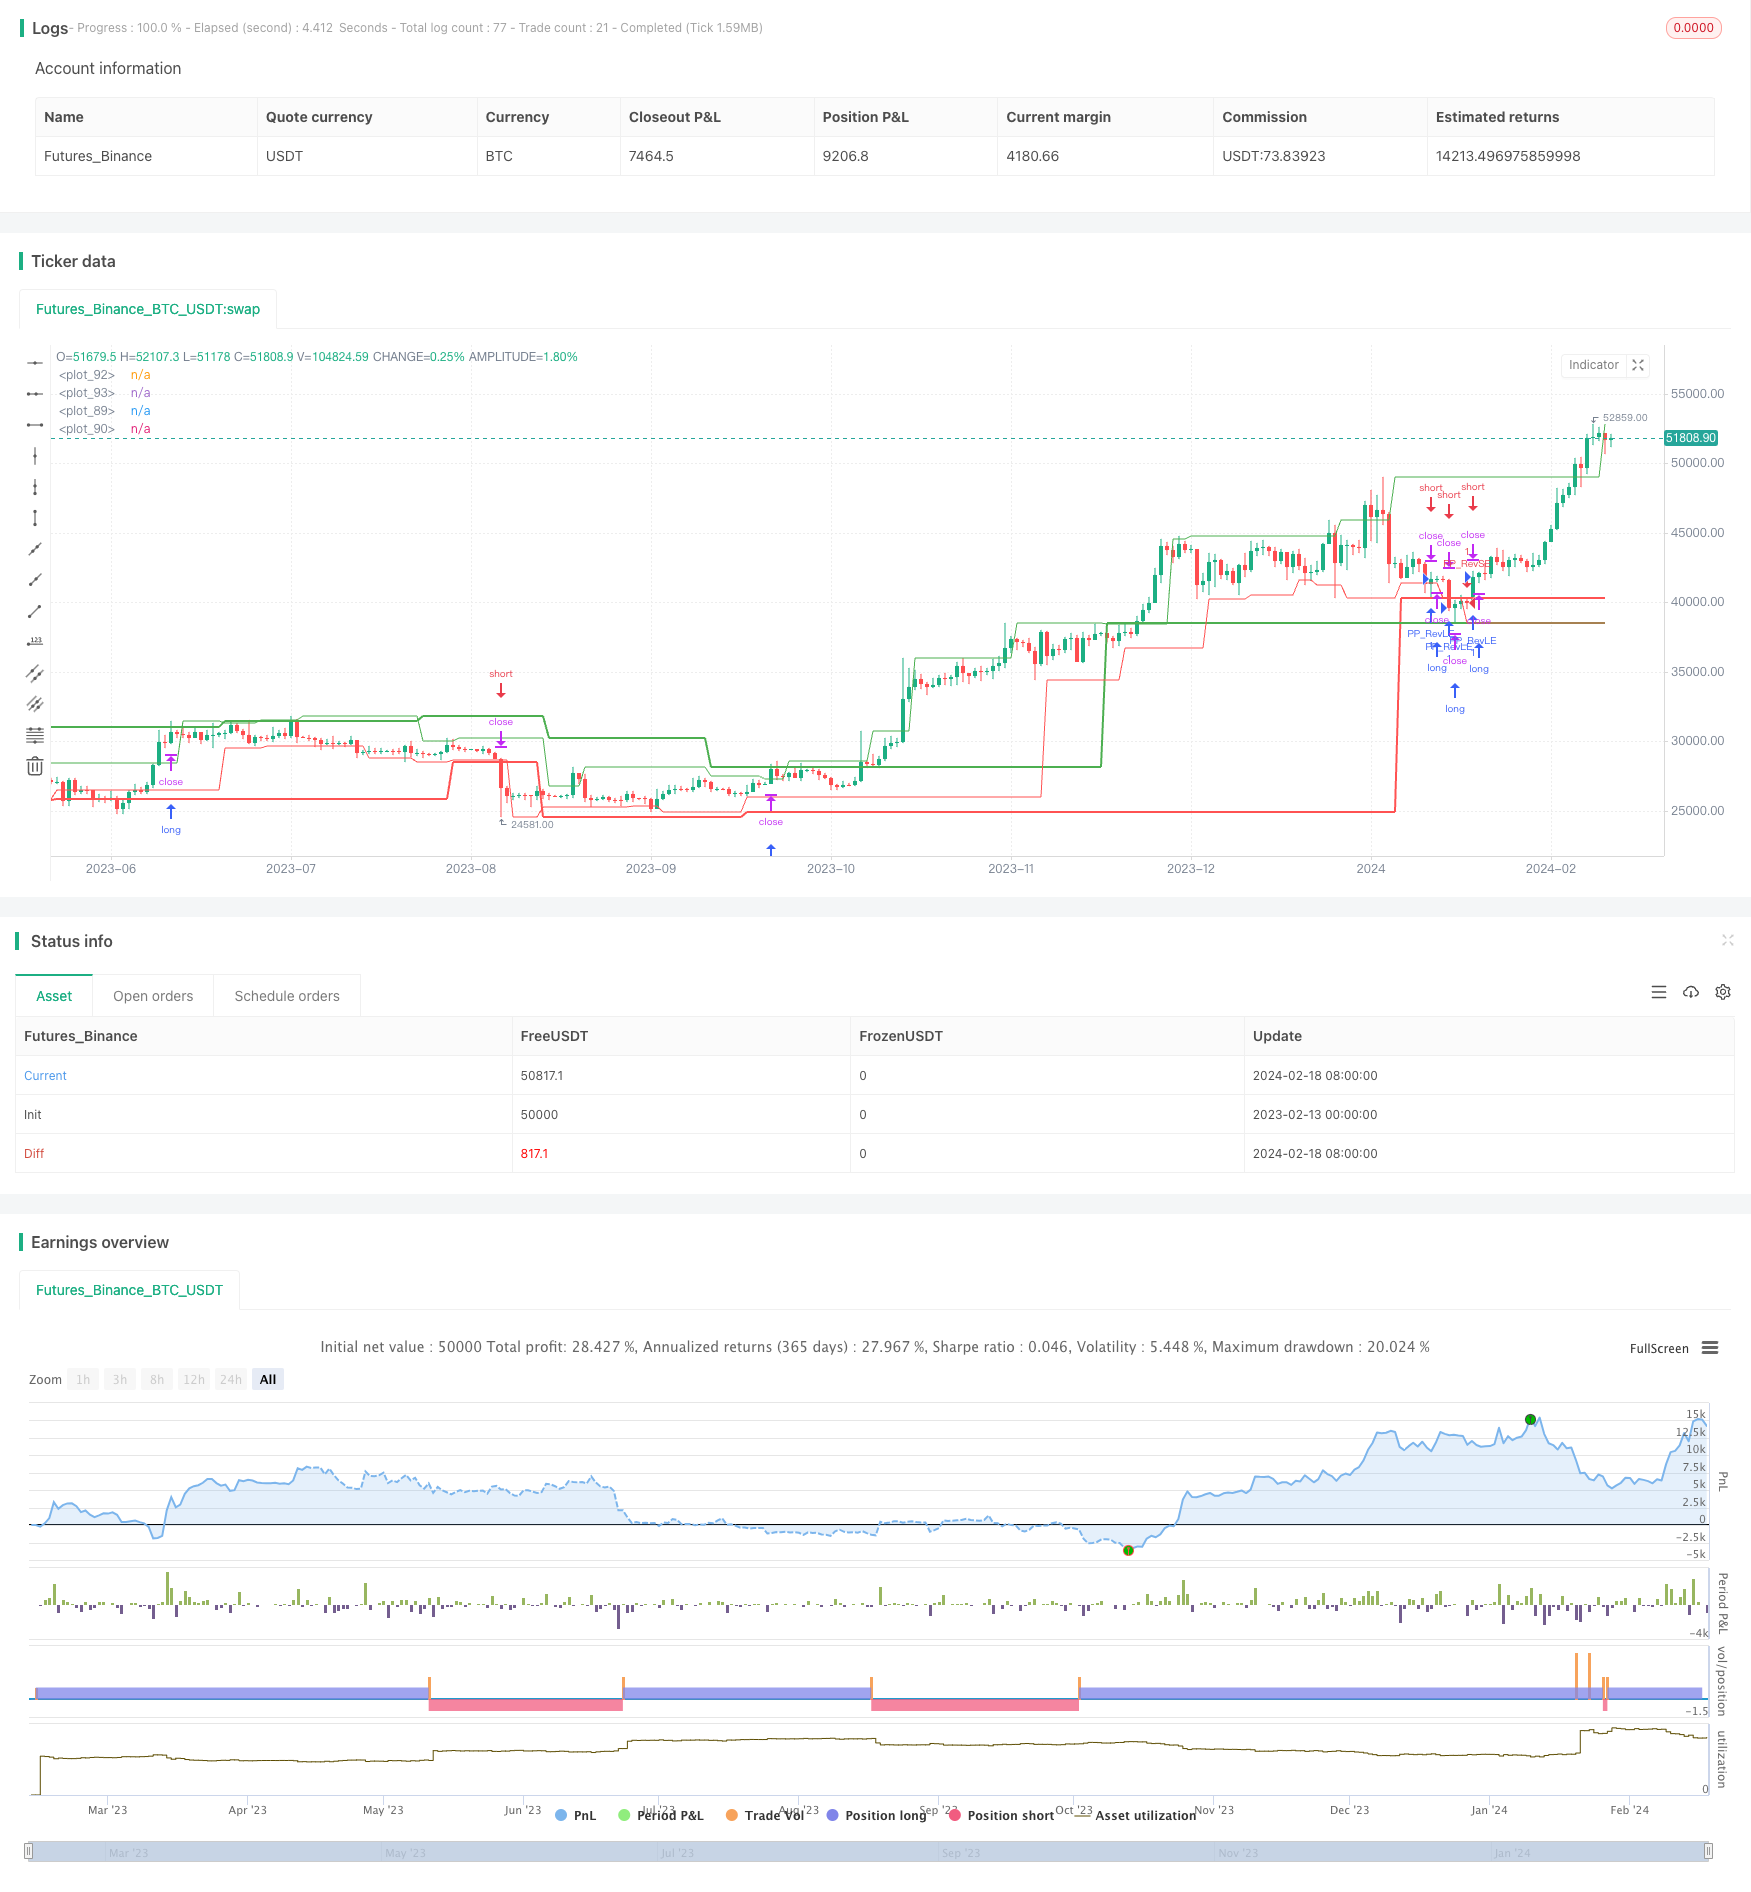
The core idea of this strategy is to use pivot points for quantitative trading. It looks for important swing highs and lows and makes reversal trades when prices break through these key levels.
Overview
The core idea of this strategy is to use pivot points for quantitative trading. It looks for important swing highs and lows and makes reversal trades when prices break through these key levels.
Strategy Logic
The strategy first defines functions pivotHighSig() and pivotLowSig() to locate swing highs and low points. These two functions search for qualified pivot points on the left and right sides.
Specifically, for swing highs, it looks for multiple higher highs on the left and multiple lower highs on the right. Thus the pivot high sits at a relatively higher level. The criteria for swing lows are opposite - it looks for higher lows and lower lows on both sides.
After locating the swing highs and lows, the strategy further selects pivot points from those pivot points, i.e. important points from the pivots. This is achieved by defining multiple historical variables for the swing highs and lows, e.g. ph1, ph2 etc.
Finally, reversal trades are taken when prices break through the pivot points of pivots.
Advantages
This pivot point based quantitative strategy has the following advantages:
- It takes advantage of support and resistance levels in the market where turnarounds often happen
- It identifies both important high and low points for dual-side trading
- Pivot points are outstanding extremum points and breaking through them gives strong signals
- Using pivot points of pivots makes the signal even more reliable
Risks and Solutions
There are also some risks with this strategy:
- Misjudging pivot points leads to wrong signals. The solution is to tune the left/right range parameters to identify pivot points more precisely.
- Breakout false signals. The solution is to filter out signals combining other factors like volume, momentum etc.
Enhancement Areas
This strategy can be improved in the following areas:
- Add stop loss mechanisms to make the strategy more stable
- Incorporate more technical indicators for signal filtering
- Develop PRED reversal models using machine learning to further boost pivot point prediction
- Build in adaptive parameters
Conclusion
Overall this strategy performs well. The core idea is to detect important pivot points and trade their breakouts. Further enhancements can generate more solid and reliable signals for higher and more consistent profits.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 4 | PP Left Bars |
| v_input_2 | 2 | PP Right Bars |
| v_input_3 | 14 | ATR Length |
| v_input_4 | 0.1 | ATR Mult |
Source Pine Script
/*backtest
start: 2023-02-13 00:00:00
end: 2024-02-19 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Pivot of Pivot Reversal Strategy [QuantNomad]", shorttitle = "PoP Reversal Strategy [QN]", overlay=true)

// Inputs
leftBars   = input(4,   title = 'PP Left Bars')
rightBars  = input(2,   title = 'PP Right Bars')
atr_length = input(14,  title = 'ATR Length')
atr_mult   = input(0.1, title = 'ATR Mult')

// Pivot High Significant Function
pivotHighSig(left, right) =>
    pp_ok = true
    atr   = atr(atr_length)

    for i = 1 to left
        if (high[right] < high[right+i] + atr * atr_mult)
            pp_ok := false
    for i = 0 to right-1
        if (high[right] < high[i] + atr * atr_mult)
            pp_ok := false

    pp_ok ? high[right] : na

// Pivot Low Significant Function
pivotLowSig(left, right) =>
    pp_ok = true
    atr   = atr(atr_length)

    for i = 1 to left
        if (low[right] > low[right+i] - atr * atr_mult)
            pp_ok := false
    for i = 0 to right-1
        if (low[right] > low[i] - atr * atr_mult)
            pp_ok := false

    pp_ok ? low[right] : na


swh = pivotHighSig(leftBars, rightBars)
swl = pivotLowSig (leftBars, rightBars)

swh_cond = not na(swh)

hprice = 0.0
hprice := swh_cond ? swh : hprice[1]

le = false
le := swh_cond ? true : (le[1] and high > hprice ? false : le[1])

swl_cond = not na(swl)

lprice = 0.0
lprice := swl_cond ? swl : lprice[1]

se = false
se := swl_cond ? true : (se[1] and low < lprice ? false : se[1])

// Pivots of pivots
ph1 = 0.0
ph2 = 0.0
ph3 = 0.0

pl1 = 0.0
pl2 = 0.0
pl3 = 0.0

pphprice = 0.0
pplprice = 0.0

ph3 := swh_cond ? nz(ph2[1]) : nz(ph3[1])
ph2 := swh_cond ? nz(ph1[1]) : nz(ph2[1])
ph1 := swh_cond ? hprice     : nz(ph1[1])

pl3 := swl_cond ? nz(pl2[1]) : nz(pl3[1])
pl2 := swl_cond ? nz(pl1[1]) : nz(pl2[1])
pl1 := swl_cond ? lprice     : nz(pl1[1])

pphprice := swh_cond and ph2 > ph1 and ph2 > ph3 ? ph2 : nz(pphprice[1])
pplprice := swl_cond and pl2 < pl1 and pl2 < pl3 ? pl2 : nz(pplprice[1])


if (le)
    strategy.entry("PP_RevLE", strategy.long, comment="PP_RevLE", stop=pphprice + syminfo.mintick)

if (se)
    strategy.entry("PP_RevSE", strategy.short, comment="PP_RevSE", stop=pplprice - syminfo.mintick)

// Plotting
plot(lprice, color = color.red,   transp = 55)
plot(hprice, color = color.green, transp = 55)

plot(pplprice, color = color.red,   transp = 0, linewidth = 2)
plot(pphprice, color = color.green, transp = 0, linewidth = 2)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Pivot-Reversal-Quantitative-Strategy-Based-on-Pivot-Points.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced Fibonacci Retracement Trend Following and Reversal Trading StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Dynamic MACD and Ichimoku Cloud Trading StrategyPine Script · Mean reversion · 1h
- Multi Level Support Resistance Weekly Mean Reversion Trading StrategyPine Script · Mean reversion · 1d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m