Strategy vault / Trend following
Positive Channel EMA Trailing Stop Strategy
This strategy is a channel-based stop loss strategy that utilizes the EMA indicator. It integrates trend judgment, channel tracking, and dynamic stop loss and other mainstream technical indicators. It determines bull…
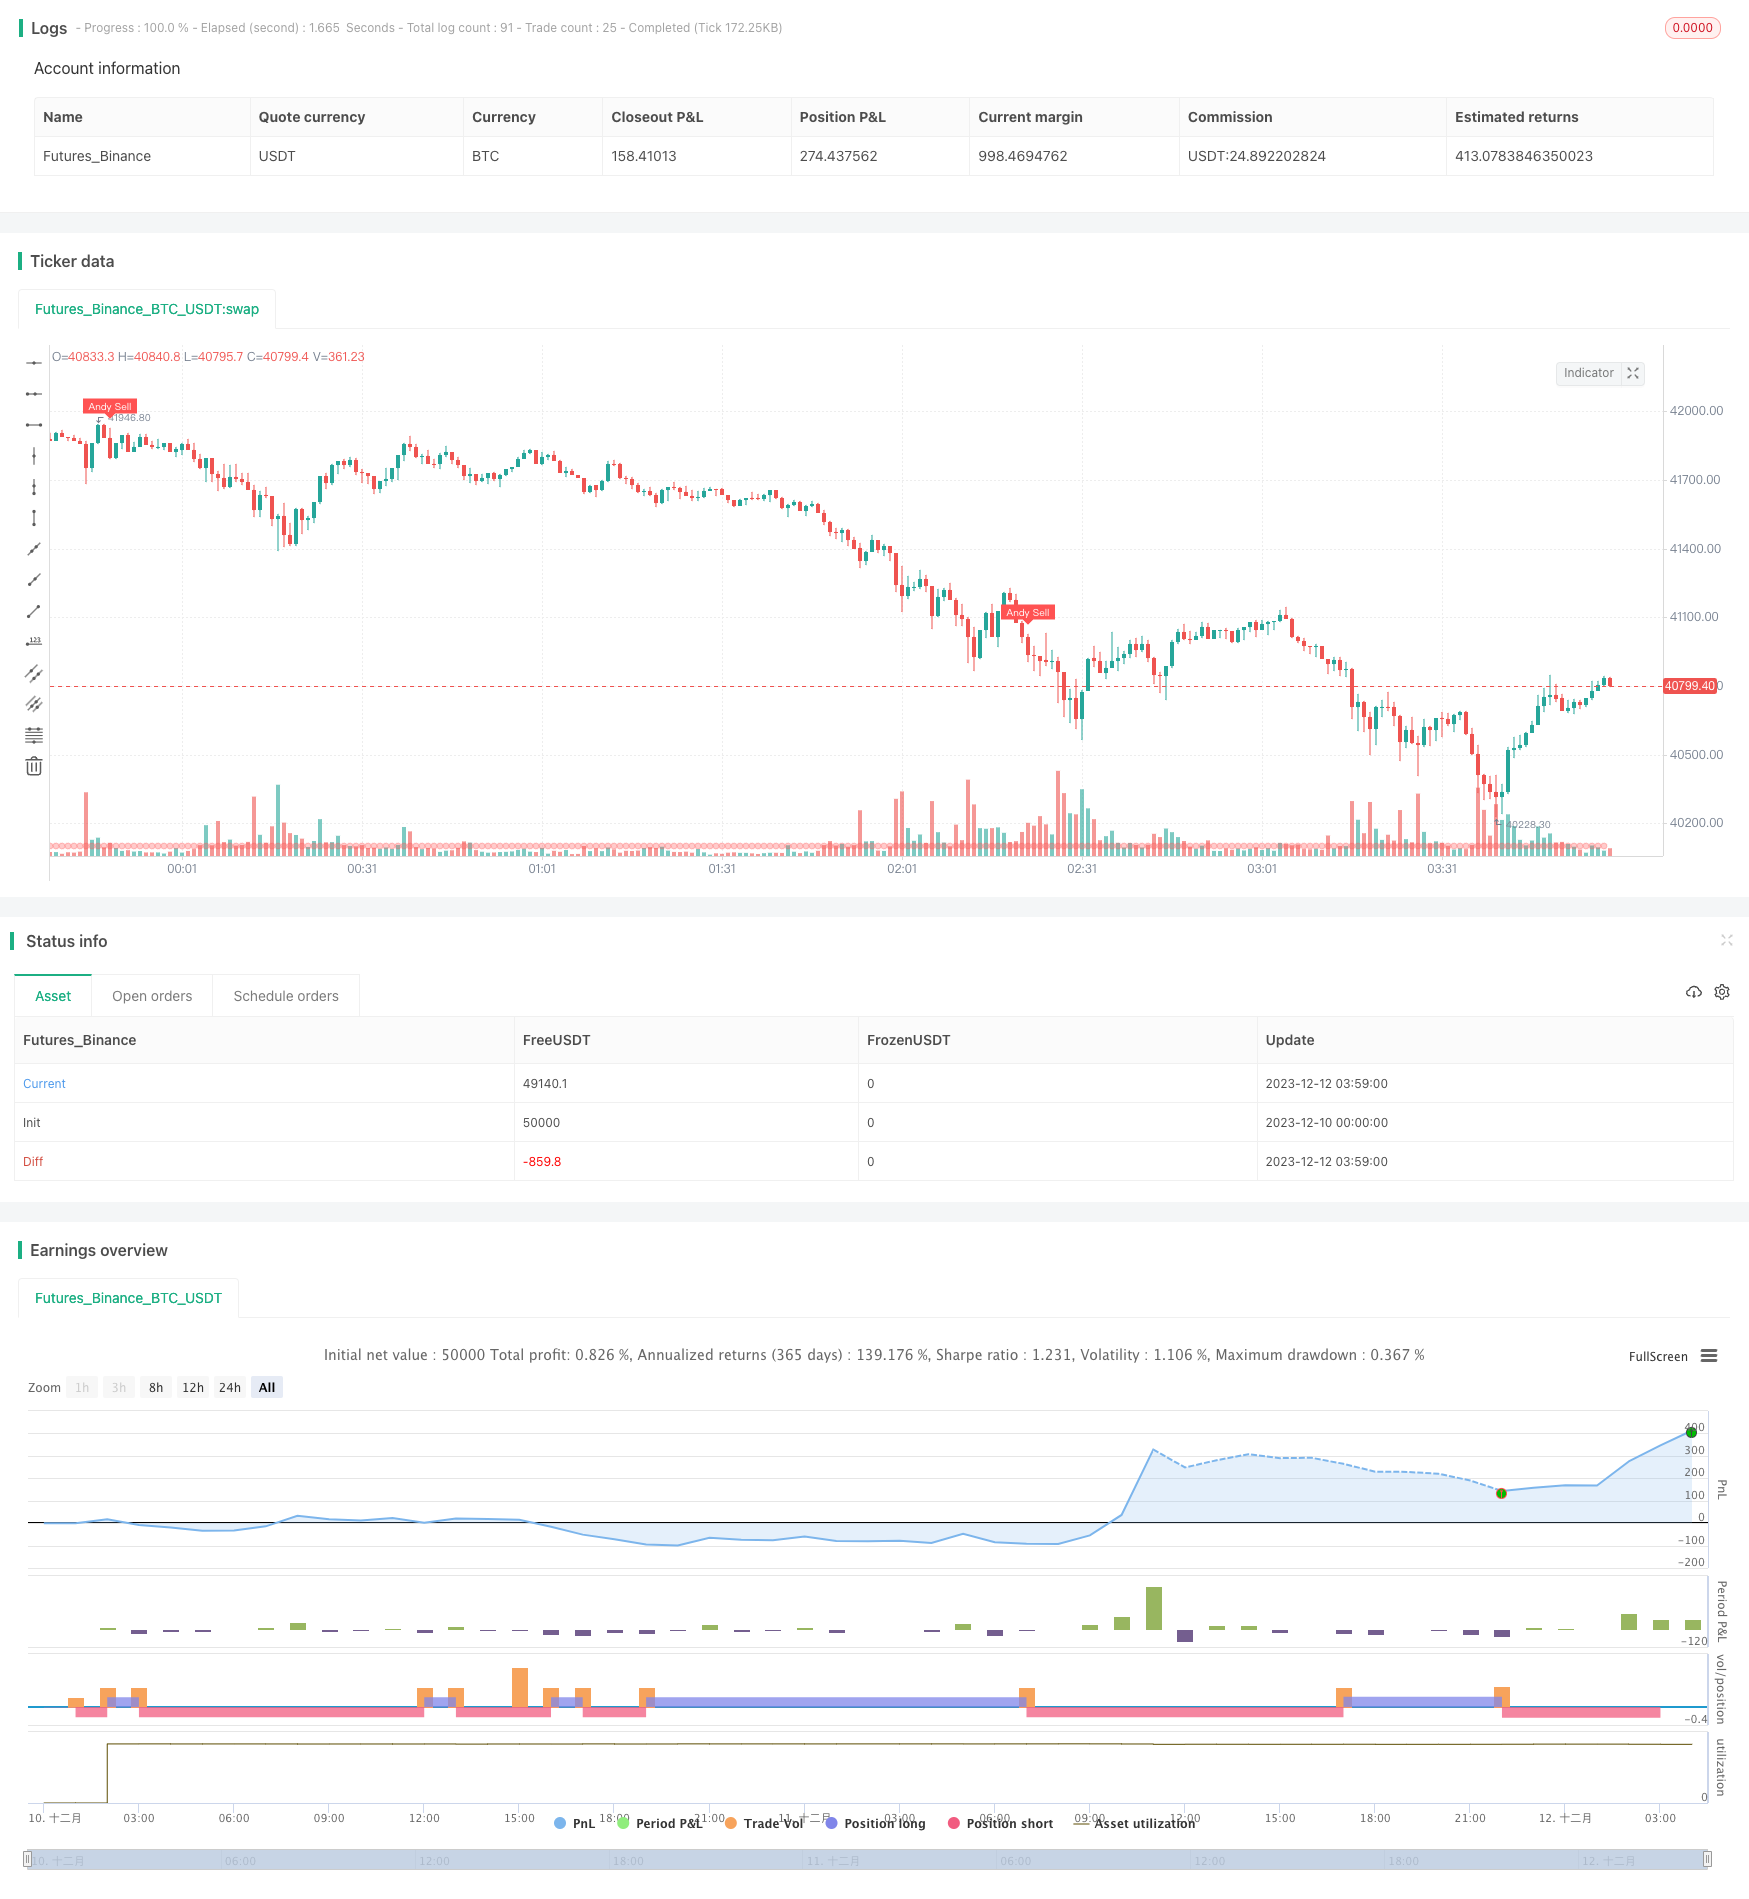
Overview
This strategy is a channel-based stop loss strategy that utilizes the EMA indicator. It integrates trend judgment, channel tracking, and dynamic stop loss and other mainstream technical indicators. It determines bull and bear cycles by judging the order of EMAs and combines ATR channel tracking to implement stop loss so that the stop loss point can continue to track price movements. This kind of stop loss idea is more active and effectively avoids the probability of too aggressive stop loss being broken through.
Strategy Logic
The strategy mainly uses three EMA curves with different cycles to determine bull and bear state. The specific judging rules are:
- EMA5>EMA20>EMA40 is a bull cycle
- EMA20>EMA5>EMA40 is a bull cycle
- EMA20>EMA40>EMA5 is a bull cycle
- EMA40>EMA20>EMA5 is a bear cycle
- EMA40>EMA5>EMA20 is a bear cycle
- EMA5>EMA40>EMA20 is a bear cycle
After determining the bull and bear cycle, the strategy uses SMMA sampled K-line price and ATR indicator multiples as the channel range. Trading signals are only issued when the price breaks through this channel. In addition, after the trading signal is issued, the ATR dynamic tracking stop loss mechanism will be activated to adjust the stop loss position in real time to ensure that the stop loss point can follow the price movement to improve the effectiveness of stop loss.
Advantages
The main advantages of this strategy are:
- Using EMA to judge bull and bear cycles can effectively capture turning points in market trends
- Building entry points based on ATR channels avoids wrongly entering during market consolidations
- ATR dynamic tracking stop loss can maximize profit locking and effectively control risks
Risks and Optimization
The main risks of this strategy are concentrated in the problems caused by improper parameter settings, such as overtrading and stop loss being broken through. Optimization can be done from the following aspects:
- Optimize the combination of EMA cycle parameters to find the best parameter match
- Optimize the ATR multiple size to prevent the stop loss from being too close or too far
- Add other filtering indicators to avoid wrong entries during choppy markets
Conclusion
This strategy integrates multiple mainstream technical indicators and methods such as trend judgment, channel trading, and dynamic stop loss to form a relatively complete stop loss trading system. There is still great room for optimization in parameter tuning and risk control. It is suitable for investors who have high requirements for stop loss.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2 | Key Vaule. 'This changes the sensitivity' |
| v_input_2 | 7 | ATR Period |
| v_input_int_1 | 25 | atr_length |
Source Pine Script
/*backtest
start: 2023-12-10 00:00:00
end: 2023-12-12 04:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © kgynofomo

//@version=5
strategy(title="[Salavi] | Andy Advance Pro Strategy [ETH|M15]",overlay = true, pyramiding = 1,initial_capital = 10000, default_qty_type = strategy.cash,default_qty_value = 10000)

ema_short = ta.ema(close,5)
ema_middle = ta.ema(close,20)
ema_long = ta.ema(close,40)

cycle_1 = ema_short>ema_middle and ema_middle>ema_long
cycle_2 = ema_middle>ema_short and ema_short>ema_long
cycle_3 = ema_middle>ema_long and ema_long>ema_short
cycle_4 = ema_long>ema_middle and ema_middle>ema_short
cycle_5 = ema_long>ema_short and ema_short>ema_middle
cycle_6 = ema_short>ema_long and ema_long>ema_middle

bull_cycle = cycle_1 or cycle_2 or cycle_3
bear_cycle = cycle_4 or cycle_5 or cycle_6
// label.new("cycle_1")
// bgcolor(color=cycle_1?color.rgb(82, 255, 148, 60):na)
// bgcolor(color=cycle_2?color.rgb(82, 255, 148, 70):na)
// bgcolor(color=cycle_3?color.rgb(82, 255, 148, 80):na)
// bgcolor(color=cycle_4?color.rgb(255, 82, 82, 80):na)
// bgcolor(color=cycle_5?color.rgb(255, 82, 82, 70):na)
// bgcolor(color=cycle_6?color.rgb(255, 82, 82, 60):na)

// Inputs
a = input(2, title='Key Vaule. \'This changes the sensitivity\'')
c = input(7, title='ATR Period')
h = false

xATR = ta.atr(c)
nLoss = a * xATR

src = h ? request.security(ticker.heikinashi(syminfo.tickerid), timeframe.period, close, lookahead=barmerge.lookahead_off) : close

xATRTrailingStop = 0.0
iff_1 = src > nz(xATRTrailingStop[1], 0) ? src - nLoss : src + nLoss
iff_2 = src < nz(xATRTrailingStop[1], 0) and src[1] < nz(xATRTrailingStop[1], 0) ? math.min(nz(xATRTrailingStop[1]), src + nLoss) : iff_1
xATRTrailingStop := src > nz(xATRTrailingStop[1], 0) and src[1] > nz(xATRTrailingStop[1], 0) ? math.max(nz(xATRTrailingStop[1]), src - nLoss) : iff_2

pos = 0
iff_3 = src[1] > nz(xATRTrailingStop[1], 0) and src < nz(xATRTrailingStop[1], 0) ? -1 : nz(pos[1], 0)
pos := src[1] < nz(xATRTrailingStop[1], 0) and src > nz(xATRTrailingStop[1], 0) ? 1 : iff_3

xcolor = pos == -1 ? color.red : pos == 1 ? color.green : color.blue

ema = ta.ema(src, 1)
above = ta.crossover(ema, xATRTrailingStop)
below = ta.crossover(xATRTrailingStop, ema)

buy = src > xATRTrailingStop and above
sell = src < xATRTrailingStop and below

barbuy = src > xATRTrailingStop
barsell = src < xATRTrailingStop


atr = ta.atr(14)
atr_length = input.int(25)
atr_rsi = ta.rsi(atr,atr_length)
atr_valid = atr_rsi>50

long_condition =  buy and bull_cycle and atr_valid
short_condition =  sell and bear_cycle and atr_valid

Exit_long_condition = short_condition
Exit_short_condition = long_condition

if long_condition
    strategy.entry("Andy Buy",strategy.long, limit=close,comment="Andy Buy Here")

if Exit_long_condition
    strategy.close("Andy Buy",comment="Andy Buy Out")
    // strategy.entry("Andy fandan Short",strategy.short, limit=close,comment="Andy Reorder short Here")
    // strategy.close("Andy fandan Buy",comment="Andy short Out")


if short_condition
    strategy.entry("Andy Short",strategy.short, limit=close,comment="Andy short Here")


// strategy.exit("STR","Long",stop=longstoploss)
if Exit_short_condition
    strategy.close("Andy Short",comment="Andy short Out")
    // strategy.entry("Andy fandan Buy",strategy.long, limit=close,comment="Andy Reorder Buy Here")
    // strategy.close("Andy fandan Short",comment="Andy Buy Out")


inLongTrade = strategy.position_size > 0
inLongTradecolor = #58D68D
notInTrade = strategy.position_size == 0
inShortTrade = strategy.position_size < 0

// bgcolor(color = inLongTrade?color.rgb(76, 175, 79, 70):inShortTrade?color.rgb(255, 82, 82, 70):na)
plotshape(close!=0,location = location.bottom,color = inLongTrade?color.rgb(76, 175, 79, 70):inShortTrade?color.rgb(255, 82, 82, 70):na)


plotshape(long_condition, title='Buy', text='Andy Buy', style=shape.labelup, location=location.belowbar, color=color.new(color.green, 0), textcolor=color.new(color.white, 0), size=size.tiny)
plotshape(short_condition, title='Sell', text='Andy Sell', style=shape.labeldown, location=location.abovebar, color=color.new(color.red, 0), textcolor=color.new(color.white, 0), size=size.tiny)


// //atr > close *0.01* parameter

// // MONTHLY TABLE PERFORMANCE - Developed by @QuantNomad
// // *************************************************************************************************************************************************************************************************************************************************************************
// show_performance = input.bool(true, 'Show Monthly Performance ?', group='Performance - credits: @QuantNomad')
// prec = input(2, 'Return Precision', group='Performance - credits: @QuantNomad')

// if show_performance
//     new_month = month(time) != month(time[1])
//     new_year  = year(time)  != year(time[1])

//     eq = strategy.equity

//     bar_pnl = eq / eq[1] - 1

//     cur_month_pnl = 0.0
//     cur_year_pnl  = 0.0

//     // Current Monthly P&L
//     cur_month_pnl := new_month ? 0.0 :
//                      (1 + cur_month_pnl[1]) * (1 + bar_pnl) - 1

//     // Current Yearly P&L
//     cur_year_pnl := new_year ? 0.0 :
//                      (1 + cur_year_pnl[1]) * (1 + bar_pnl) - 1

//     // Arrays to store Yearly and Monthly P&Ls
//     var month_pnl  = array.new_float(0)
//     var month_time = array.new_int(0)

//     var year_pnl  = array.new_float(0)
//     var year_time = array.new_int(0)

//     last_computed = false

//     if (not na(cur_month_pnl[1]) and (new_month or barstate.islastconfirmedhistory))
//         if (last_computed[1])
//             array.pop(month_pnl)
//             array.pop(month_time)

//         array.push(month_pnl , cur_month_pnl[1])
//         array.push(month_time, time[1])

//     if (not na(cur_year_pnl[1]) and (new_year or barstate.islastconfirmedhistory))
//         if (last_computed[1])
//             array.pop(year_pnl)
//             array.pop(year_time)

//         array.push(year_pnl , cur_year_pnl[1])
//         array.push(year_time, time[1])

//     last_computed := barstate.islastconfirmedhistory ? true : nz(last_computed[1])

//     // Monthly P&L Table
//     var monthly_table = table(na)

//     if (barstate.islastconfirmedhistory)
//         monthly_table := table.new(position.bottom_center, columns = 14, rows = array.size(year_pnl) + 1, border_width = 1)

//         table.cell(monthly_table, 0,  0, "",     bgcolor = #cccccc)
//         table.cell(monthly_table, 1,  0, "Jan",  bgcolor = #cccccc)
//         table.cell(monthly_table, 2,  0, "Feb",  bgcolor = #cccccc)
//         table.cell(monthly_table, 3,  0, "Mar",  bgcolor = #cccccc)
//         table.cell(monthly_table, 4,  0, "Apr",  bgcolor = #cccccc)
//         table.cell(monthly_table, 5,  0, "May",  bgcolor = #cccccc)
//         table.cell(monthly_table, 6,  0, "Jun",  bgcolor = #cccccc)
//         table.cell(monthly_table, 7,  0, "Jul",  bgcolor = #cccccc)
//         table.cell(monthly_table, 8,  0, "Aug",  bgcolor = #cccccc)
//         table.cell(monthly_table, 9,  0, "Sep",  bgcolor = #cccccc)
//         table.cell(monthly_table, 10, 0, "Oct",  bgcolor = #cccccc)
//         table.cell(monthly_table, 11, 0, "Nov",  bgcolor = #cccccc)
//         table.cell(monthly_table, 12, 0, "Dec",  bgcolor = #cccccc)
//         table.cell(monthly_table, 13, 0, "Year", bgcolor = #999999)


//         for yi = 0 to array.size(year_pnl) - 1
//             table.cell(monthly_table, 0,  yi + 1, str.tostring(year(array.get(year_time, yi))), bgcolor = #cccccc)

//             y_color = array.get(year_pnl, yi) > 0 ? color.new(color.teal, transp = 40) : color.new(color.gray, transp = 40)
//             table.cell(monthly_table, 13, yi + 1, str.tostring(math.round(array.get(year_pnl, yi) * 100, prec)), bgcolor = y_color, text_color=color.new(color.white, 0))

//         for mi = 0 to array.size(month_time) - 1
//             m_row   = year(array.get(month_time, mi))  - year(array.get(year_time, 0)) + 1
//             m_col   = month(array.get(month_time, mi))
//             m_color = array.get(month_pnl, mi) > 0 ? color.new(color.teal, transp = 40) : color.new(color.gray, transp = 40)

//             table.cell(monthly_table, m_col, m_row, str.tostring(math.round(array.get(month_pnl, mi) * 100, prec)), bgcolor = m_color, text_color=color.new(color.white, 0))
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Positive-Channel-EMA-Trailing-Stop-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR RSI Enhanced Trend Following Trading SystemPine Script · Trend following
- Dynamic ATR Trailing Stop with EMA Cross Combination StrategyPine Script · Trend following · 2h
- SuperTrend Trailing Stop Strategy Based on Heikin AshiPine Script · Trend following · 4h
- Dynamic Trend Following ATR Multi Period Trading StrategyPine Script · Trend following · 1d
- Triple Confirmation Trend Tracking StrategyPine Script · Trend following · 1h
- Multi Indicator Adaptive Trend Following StrategyPine Script · Trend following · 1d