Strategy vault / Mean reversion
Precise Trend Reversal Moving Average Crossover Strategy
This strategy is named "Golden Cross Death Cross Strategy". Its core idea is to capitalize on the powerful signals generated by the golden cross and death cross of two moving averages of different timeframes to catch…
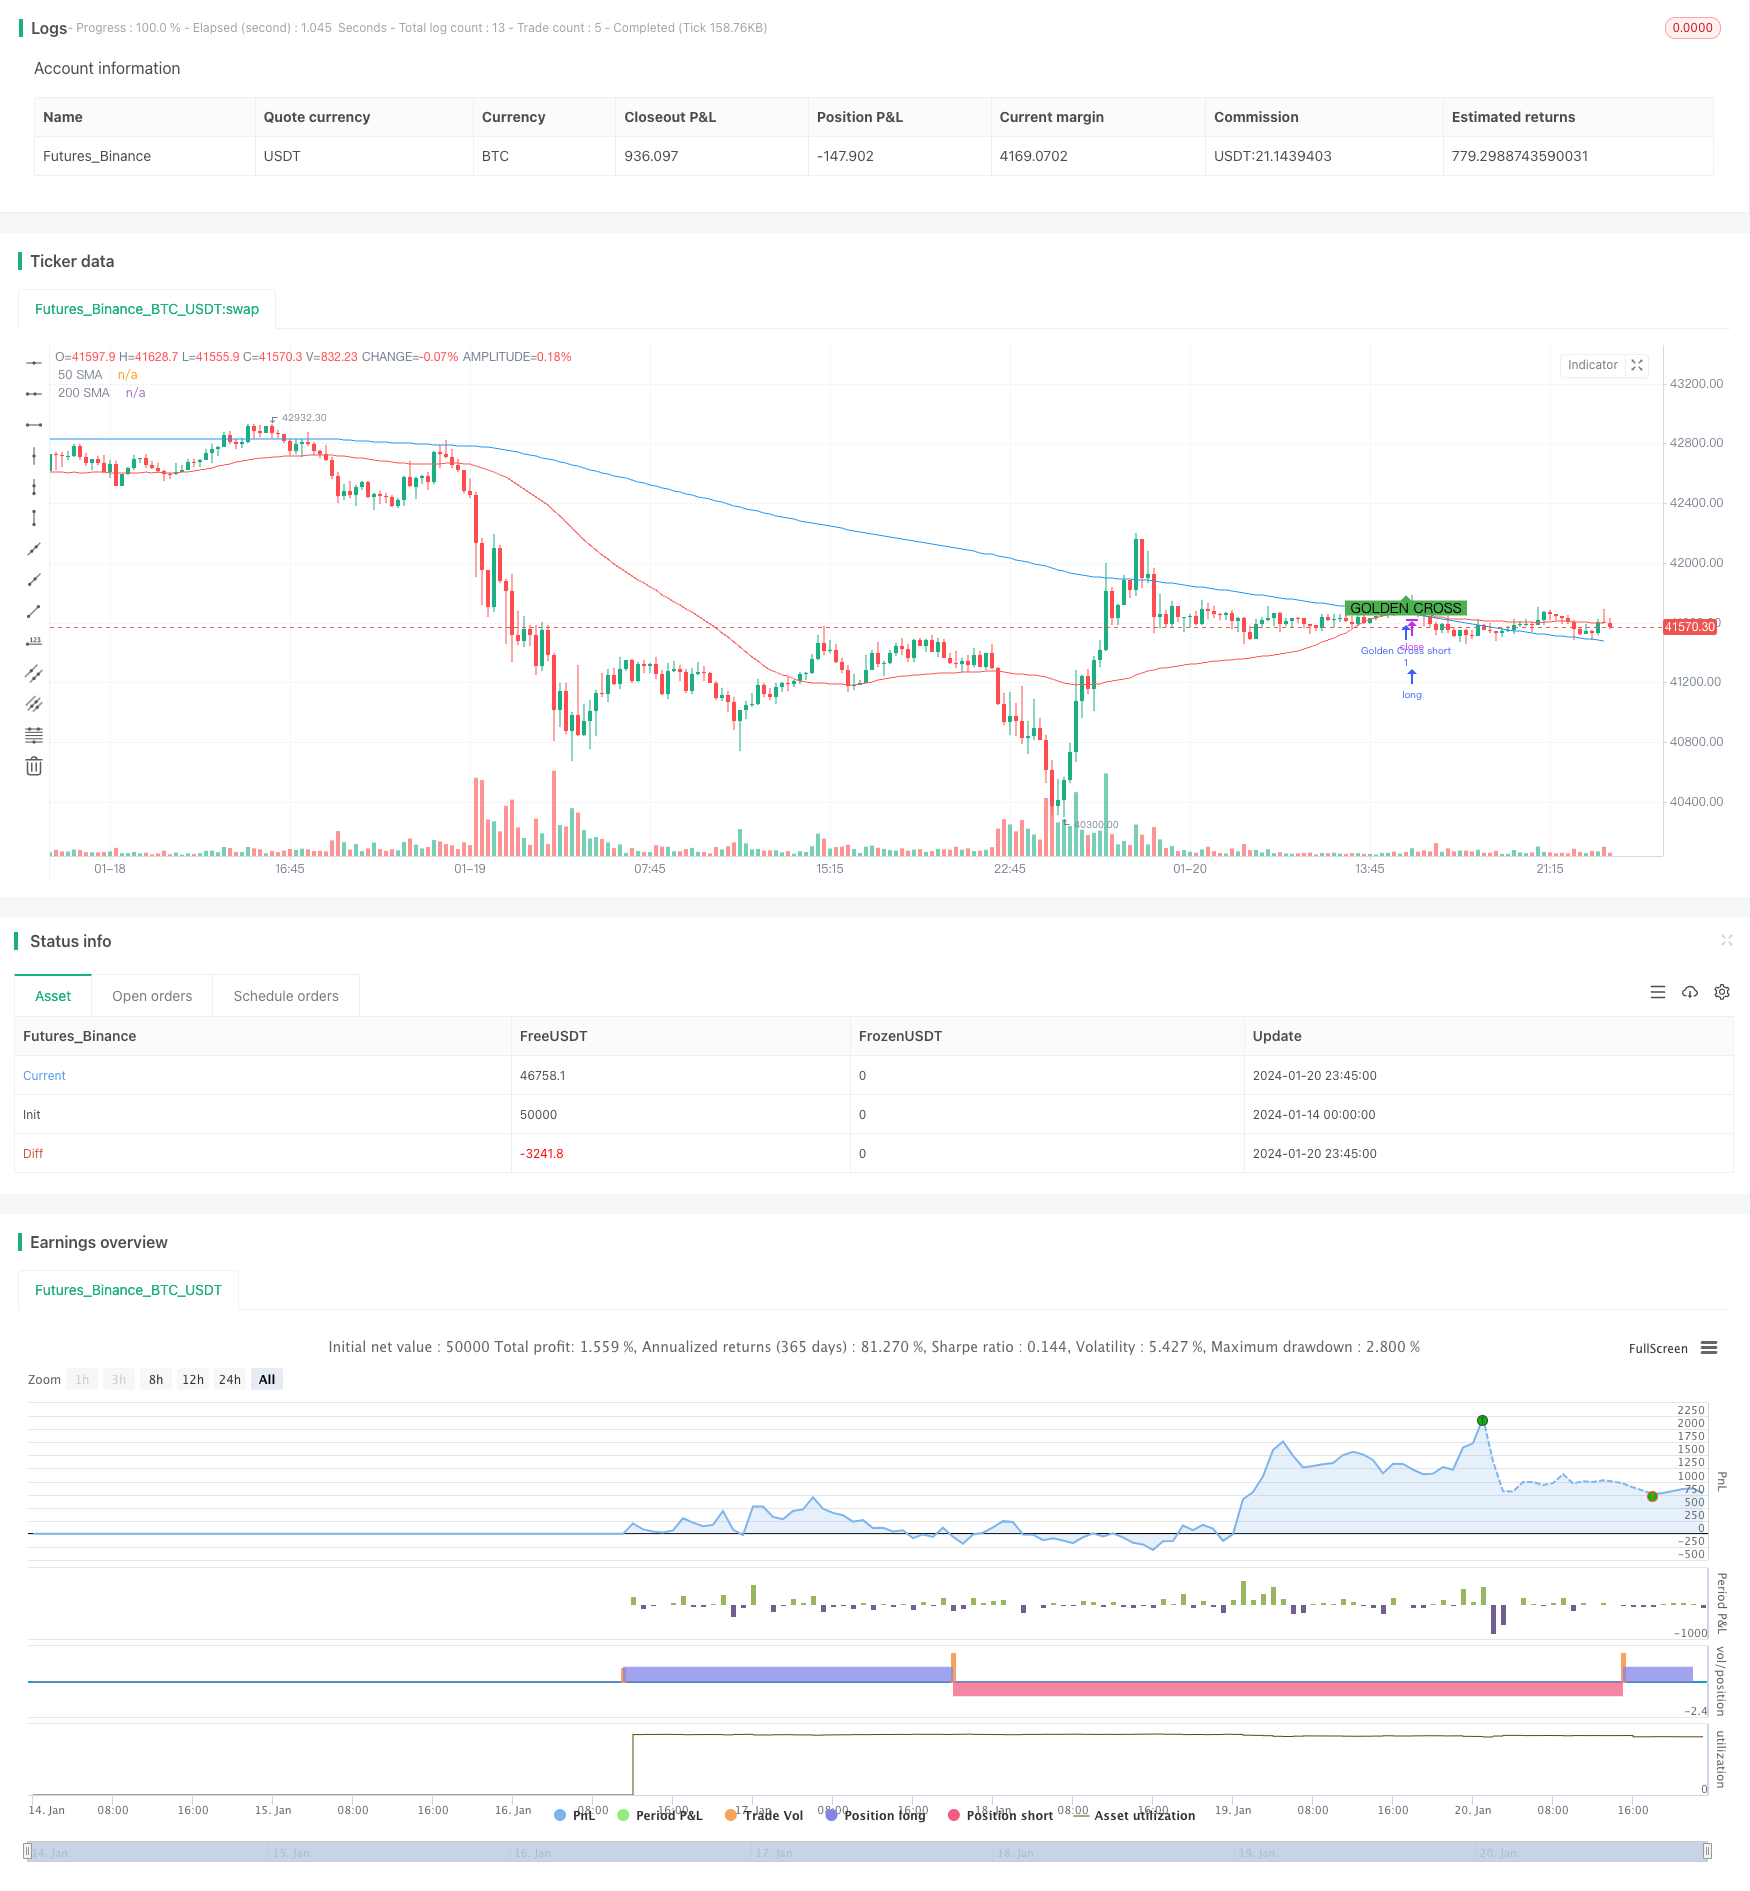
Overview
This strategy is named "Golden Cross Death Cross Strategy". Its core idea is to capitalize on the powerful signals generated by the golden cross and death cross of two moving averages of different timeframes to catch trend reversals in the market and profit from low-buying/high-selling.
Strategy Logic
In this strategy, we calculate the 50-period and 200-period Simple Moving Average (SMA) lines. Traditionally, when the 50-day SMA crosses below the 200-day SMA, it is called a "death cross" which signals a bearish outlook. And when 50-day SMA crosses above 200-day SMA, it is a "golden cross" indicating bullishness.
The trading logic is simply to take positions based on these signals - shorting at death cross and going long at golden cross. This allows us to profit around inflection points when market trend reverses.
In addition, the strategy provides customizable date ranges for backtests. So we can examine the actual effectiveness of these crossover signals over different periods.
Advantages
- Effectively catches trend reversal points to open positions near key areas
- Combination of two SMAs of different periods filters out false signals
- Backtesting feature examines actual performance across market regimes
- Clean plots visually display crossover signals and position changes
Risks
- SMA crosses lag extreme reversals and cannot predict them
- Backtest data may differ from live performance due to costs and slippage
- Parameter selections like SMA periods greatly affect results
- Need to incorporate fundamentals and technicals, not just mechanical trading
To address the risks, we can optimize parameters, add filters, manage risk, paper trade the strategy etc. to minimize risks.
Enhancement Opportunities
The main ways to optimize this strategy include:
- Testing SMAs of different period combinations
- Adding filters like volume, volatility to avoid whipsaws
- Incorporating economic data or news for filter
- Implement stop loss mechanisms like moving/time stops
- Evaluating performance over different holding periods
By examining the parameter impacts, we can discover better moving average crossover systems.
Conclusion
This strategy leverages the classic technical indicator of moving average crosses to capture key inflection points in markets. With simple logic and convenient backtest features, it can aid in tracking trends as part of a broader system. But real-world trading still requires considering various external factors, not just relying on signals blindly.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | true | (?DATE CONFIG)Start Date |
| v_input_int_2 | true | Start Month |
| v_input_int_3 | 2023 | Start Year |
| v_input_int_4 | 31 | End Date |
| v_input_int_5 | 12 | End Month |
| v_input_int_6 | 2023 | End Year |
| v_input_bool_1 | false | USE SPECIFIC DATE ? |
Source Pine Script
/*backtest
start: 2024-01-14 00:00:00
end: 2024-01-21 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("[S_R__9] - Death and Golden Cross", overlay=true)

// Specific Time Date Range For Backtest
startDate = input.int(title='Start Date', defval=1, minval=1, maxval=31, group='DATE CONFIG')
startMonth = input.int(title='Start Month', defval=1, minval=1, maxval=12, group='DATE CONFIG')
startYear = input.int(title='Start Year', defval=2023, minval=1800, maxval=2100, group='DATE CONFIG')

endDate = input.int(title='End Date', defval=31, minval=1, maxval=31, group='DATE CONFIG')
endMonth = input.int(title='End Month', defval=12, minval=1, maxval=12, group='DATE CONFIG')
endYear = input.int(title='End Year', defval=2023, minval=1800, maxval=2100, group='DATE CONFIG')

SPECIFIC_DATE = input.bool(title='USE SPECIFIC DATE ?', defval=false, group='DATE CONFIG')

inDateRange = SPECIFIC_DATE ? time >= timestamp(syminfo.timezone, startYear, startMonth, startDate, 0, 0) and time < timestamp(syminfo.timezone, endYear, endMonth, endDate, 0, 0) : true

// Calculate 50 SMA and 200 SMA
sma50 = ta.sma(close, 50)
sma200 = ta.sma(close, 200)

// Detect a Death Cross (50 SMA crossing below 200 SMA)
deathCross = ta.crossunder(sma50, sma200)
// Detect a Golden Cross (50 SMA crossing above 200 SMA)
goldenCross = ta.crossover(sma50, sma200)

// Strategy Execution
if (inDateRange)
    if (deathCross)
        strategy.entry("Death Cross long", strategy.short)

    if (goldenCross)
        strategy.entry("Golden Cross short", strategy.long)

// Plot SMAs
plot(sma50, color=color.red, title="50 SMA")
plot(sma200, color=color.blue, title="200 SMA")

// Plotting Death Cross signal
plotshape(series=deathCross and inDateRange, title="Death Cross Signal", location=location.belowbar, color=color.red, style=shape.labeldown, text="DEATH CROSS")

// Plotting Golden Cross signal
plotshape(series=goldenCross and inDateRange, title="Golden Cross Signal", location=location.abovebar, color=color.green, style=shape.labelup, text="GOLDEN CROSS")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Precise-Trend-Reversal-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d