Strategy vault / Mean reversion
Price Channel Robot White Box Strategy
The Price Channel Robot White Box Strategy is a simple mechanical trading strategy based on the price channel indicator. It uses the upper and lower limits of the price channel to determine entry and exit points. The…
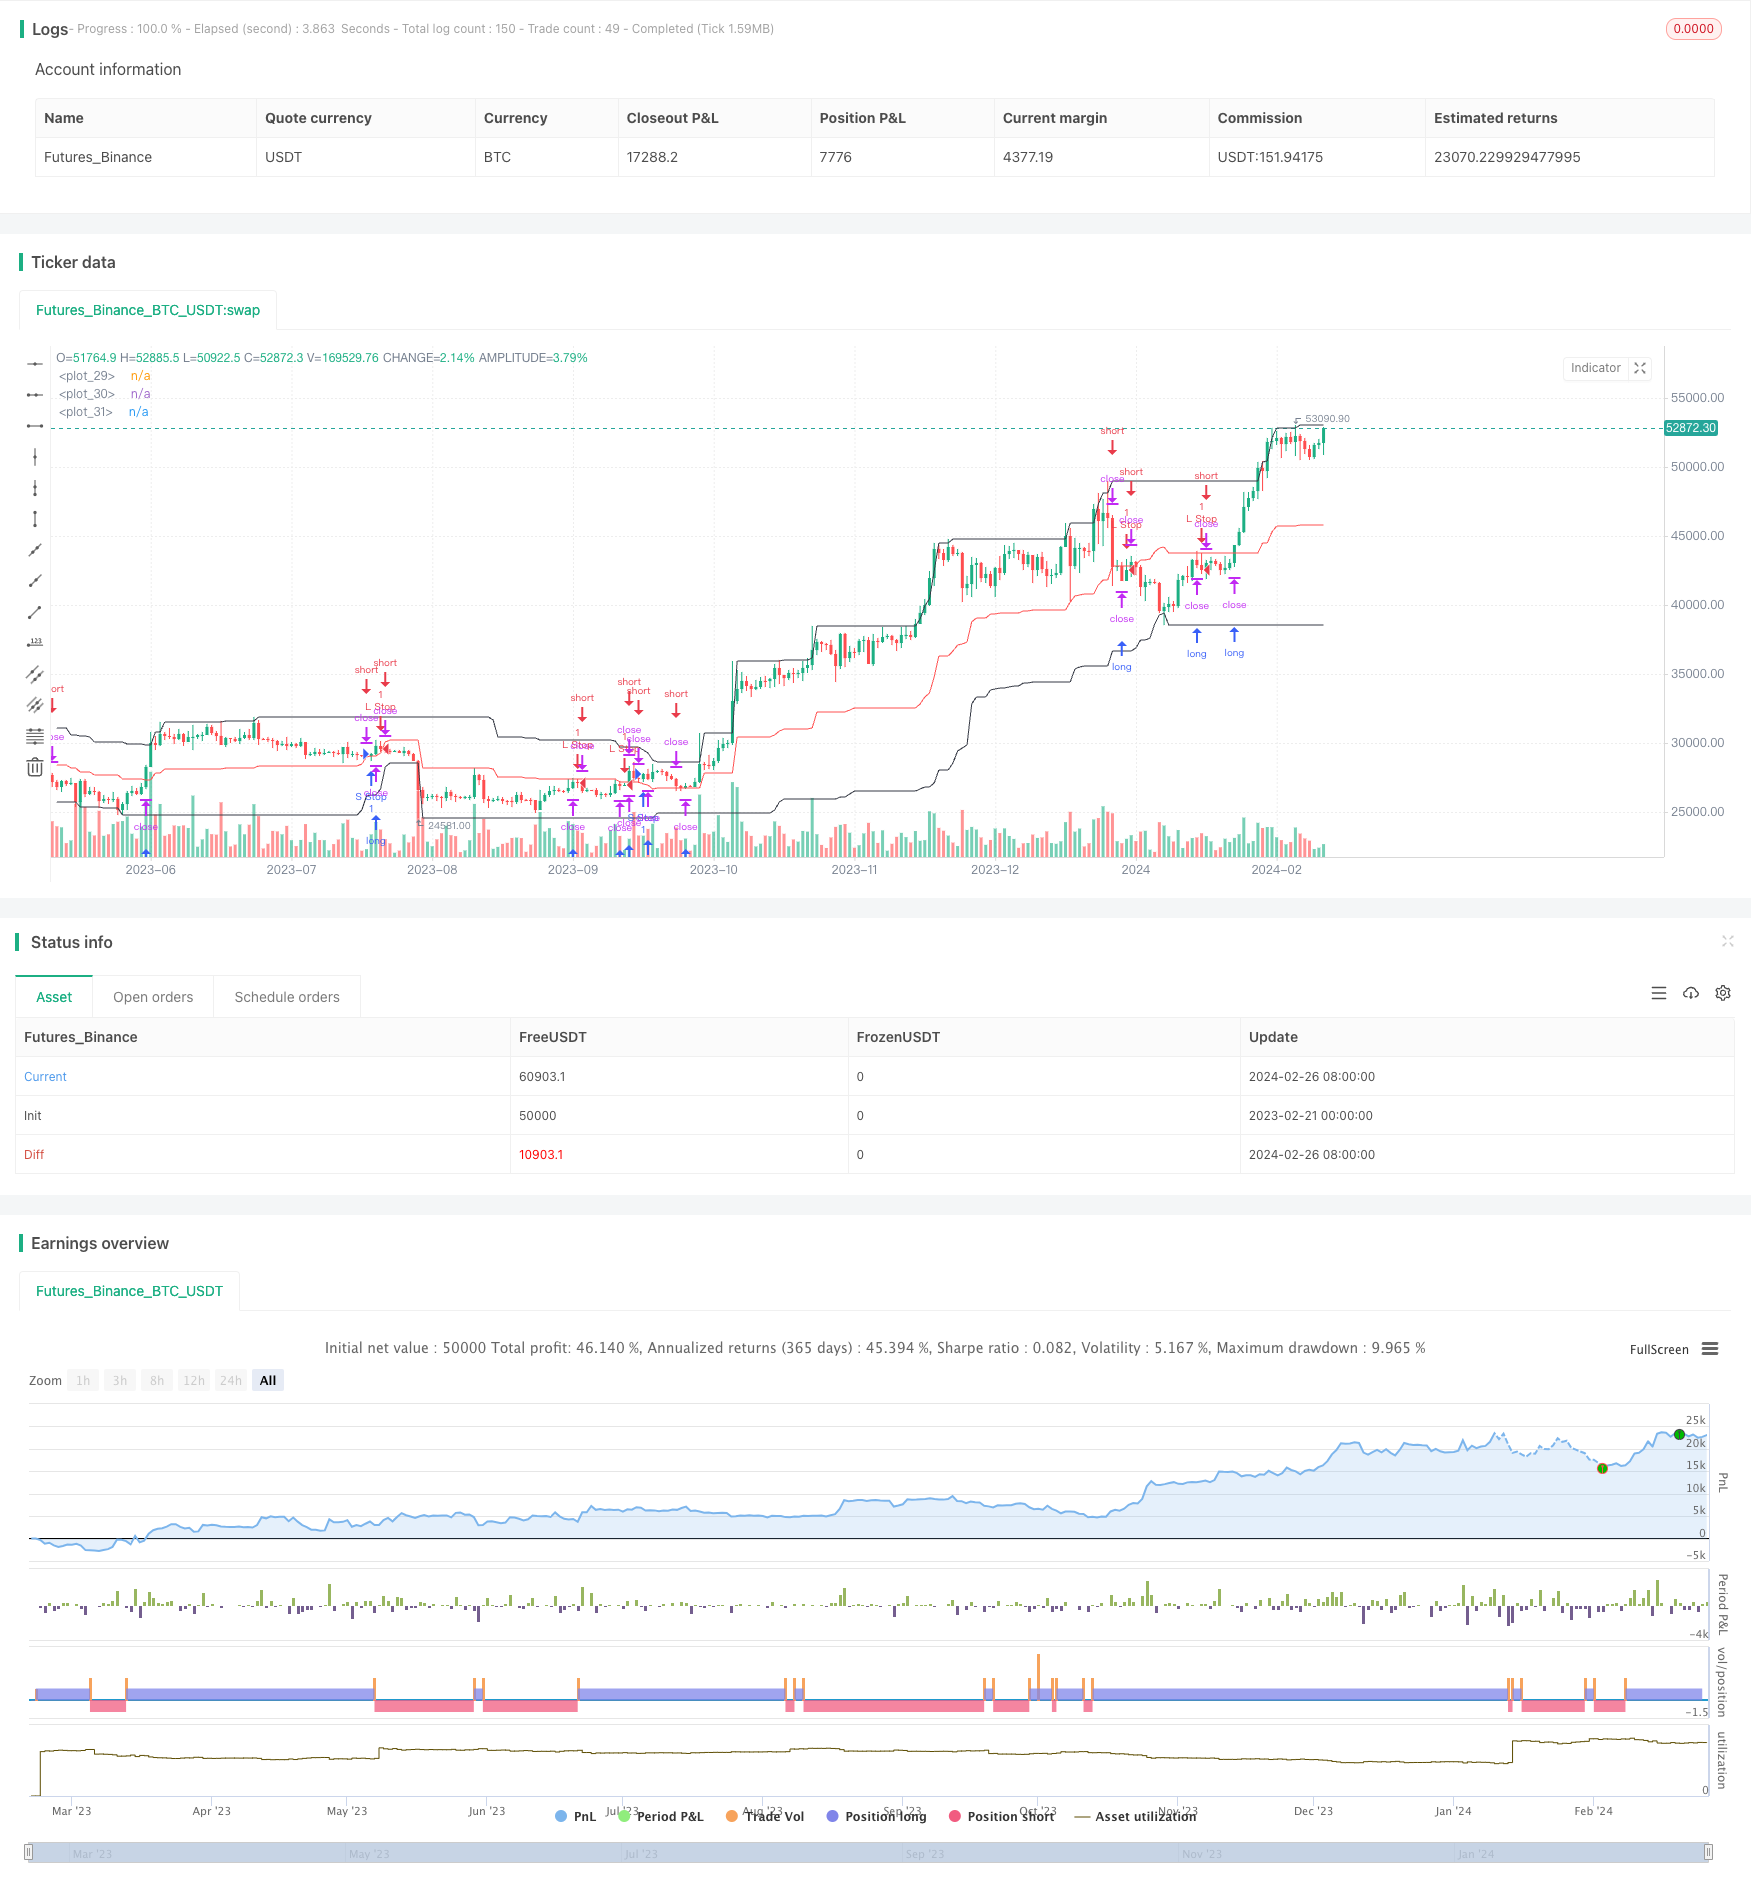
Overview
The Price Channel Robot White Box Strategy is a simple mechanical trading strategy based on the price channel indicator. It uses the upper and lower limits of the price channel to determine entry and exit points. The strategy goes long on uptrend and goes short on downtrend.
Strategy Logic
The core logic of the Price Channel Robot White Box Strategy is:
- Use highest and lowest functions to calculate the highest high and lowest low of recent len bars, defined as upper and lower limits of the price channel
- Calculate middle price of price channel: (highest high + lowest low) / 2
- Go long when price breaks above the upper limit of price channel
- Go short when price breaks below the lower limit of price channel
- Close position when price pulls back to the middle price of price channel
The strategy also has some configurable parameters:
- Price channel length len: default 50 bars
- Trade direction: long, short can be configured separately
- Trade size: default 100% of account equity
- Stop loss: option to use middle price as stop loss
- Trading hours: only trade within configured date range
By adjusting these parameters, the strategy can be better adapted to different products and market environments.
Advantage Analysis
The Price Channel Robot White Box Strategy has the following advantages:
- Simple logic, easy to understand and implement
- Make full use of price channel indicator to determine trend and reversal
- Highly configurable parameters for better adaptability
- Built-in stop loss mechanism to limit losses
- Support time filter to avoid impacts of major events
In summary, it is a simple yet practical trend following strategy, which can achieve decent results after parameter tuning.
Risk Analysis
The Price Channel Robot White Box Strategy also has some risks:
- Price channel indicator is sensitive to parameter len, independent testing and optimization needed for different timeframes and products
- Tracking stop loss has risk of being stopped out prematurely, stop loss distance needs adjustment based on market volatility
- Excessive meaningless trades during range-bound and sideways markets, increasing transaction costs and slippage
To reduce these risks, optimization needs to be done in the following aspects:
- Use Walk Forward Analysis to auto optimize parameters
- Add buffer zone to stop loss price to avoid being stopped out
- Add trend filter to avoid trading in sideways market
Optimization Directions
There is room for further optimization of the Price Channel Robot White Box Strategy:
- Add judgement of higher timeframe trend to avoid counter trend trading
- Use price spread between correlated products to set parameters and utilize arbitrage opportunities
- Add random buffer to stop loss price to reduce chance of stopped out
- Dynamically adjust price channel parameter len based on market volatility
- Train agent with deep learning methods to optimize strategy for specific products
These optimization techniques could help further improve the stability and profitability of the strategy.
Summary
The Price Channel Robot White Box Strategy is a simple yet practical trend following strategy. It identifies trend direction and reversal points using the price channel indicator to make trading decisions. The strategy is easy to understand and implement, and can achieve decent returns after parameter tuning. There are also certain risks that need to be mitigated through optimizing parameters and stop loss. Overall, the strategy has broad application prospects and optimization potential, worth exploring and practicing.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | true | Stop-loss |
| v_input_4 | 100 | Lot, % |
| v_input_5 | 50 | Price Channel Length |
| v_input_6 | true | Show lines |
| v_input_7 | false | Show Background |
| v_input_8 | 1900 | From Year |
| v_input_9 | 2100 | To Year |
| v_input_10 | true | From Month |
| v_input_11 | 12 | To Month |
| v_input_12 | true | From day |
| v_input_13 | 31 | To day |
Source Pine Script
/*backtest
start: 2023-02-21 00:00:00
end: 2024-02-27 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro

//@version=4
strategy(title = "Robot WhiteBox Channel", shorttitle = "Robot WhiteBox Channel", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 0, commission_value = 0.1)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
needstop = input(true, defval = true, title = "Stop-loss")
lotsize = input(100, defval = 100, minval = 1, maxval = 10000, title = "Lot, %")
len = input(50, minval = 1, title = "Price Channel Length")
showll = input(true, defval = true, title = "Show lines")
showbg = input(false, defval = false, title = "Show Background")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Price Channel
h = highest(high, len)
l = lowest(low, len)
center = (h + l) / 2

//Lines
pccol = showll ? color.black : na
slcol = showll ? color.red : na
plot(h, offset = 1, color = pccol)
plot(center, offset = 1, color = slcol)
plot(l, offset = 1, color = pccol)

//Background
size = strategy.position_size
bgcol = showbg == false ? na : size > 0 ? color.lime : size < 0 ? color.red : na
bgcolor(bgcol, transp = 70)

//Trading
truetime = time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)
lot = 0.0
lot := size != size[1] ? strategy.equity / close * lotsize / 100 : lot[1]
if h > 0
    strategy.entry("Long", strategy.long, needlong == false ? 0 : lot, stop = h, when = strategy.position_size <= 0 and truetime)
    strategy.entry("Short", strategy.short, needshort == false ? 0 : lot, stop = l, when = strategy.position_size >= 0 and truetime)
    strategy.entry("S Stop", strategy.long, 0, stop = center, when = strategy.position_size[1] <= 0 and needstop)
    strategy.entry("L Stop", strategy.short, 0, stop = center, when = strategy.position_size[1] >= 0 and needstop)
if time > timestamp(toyear, tomonth, today, 23, 59)
    strategy.close_all()
    strategy.cancel("Long")
    strategy.cancel("Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Price-Channel-Robot-White-Box-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 1 2 3 Pattern Quantitative Trading Strategy with EMAs MACD and 4th Candle ExtensionPine Script · Mean reversion · 1h
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Moving Average Tracking StrategyPine Script · Mean reversion · 1d