Strategy vault / Trend following
Quant Strategy Based on Linear Regression Intercept
This strategy uses linear regression techniques to calculate the linear regression intercept and uses it as a trading signal to construct a quantitative trading strategy. By analyzing the price time series of stocks…
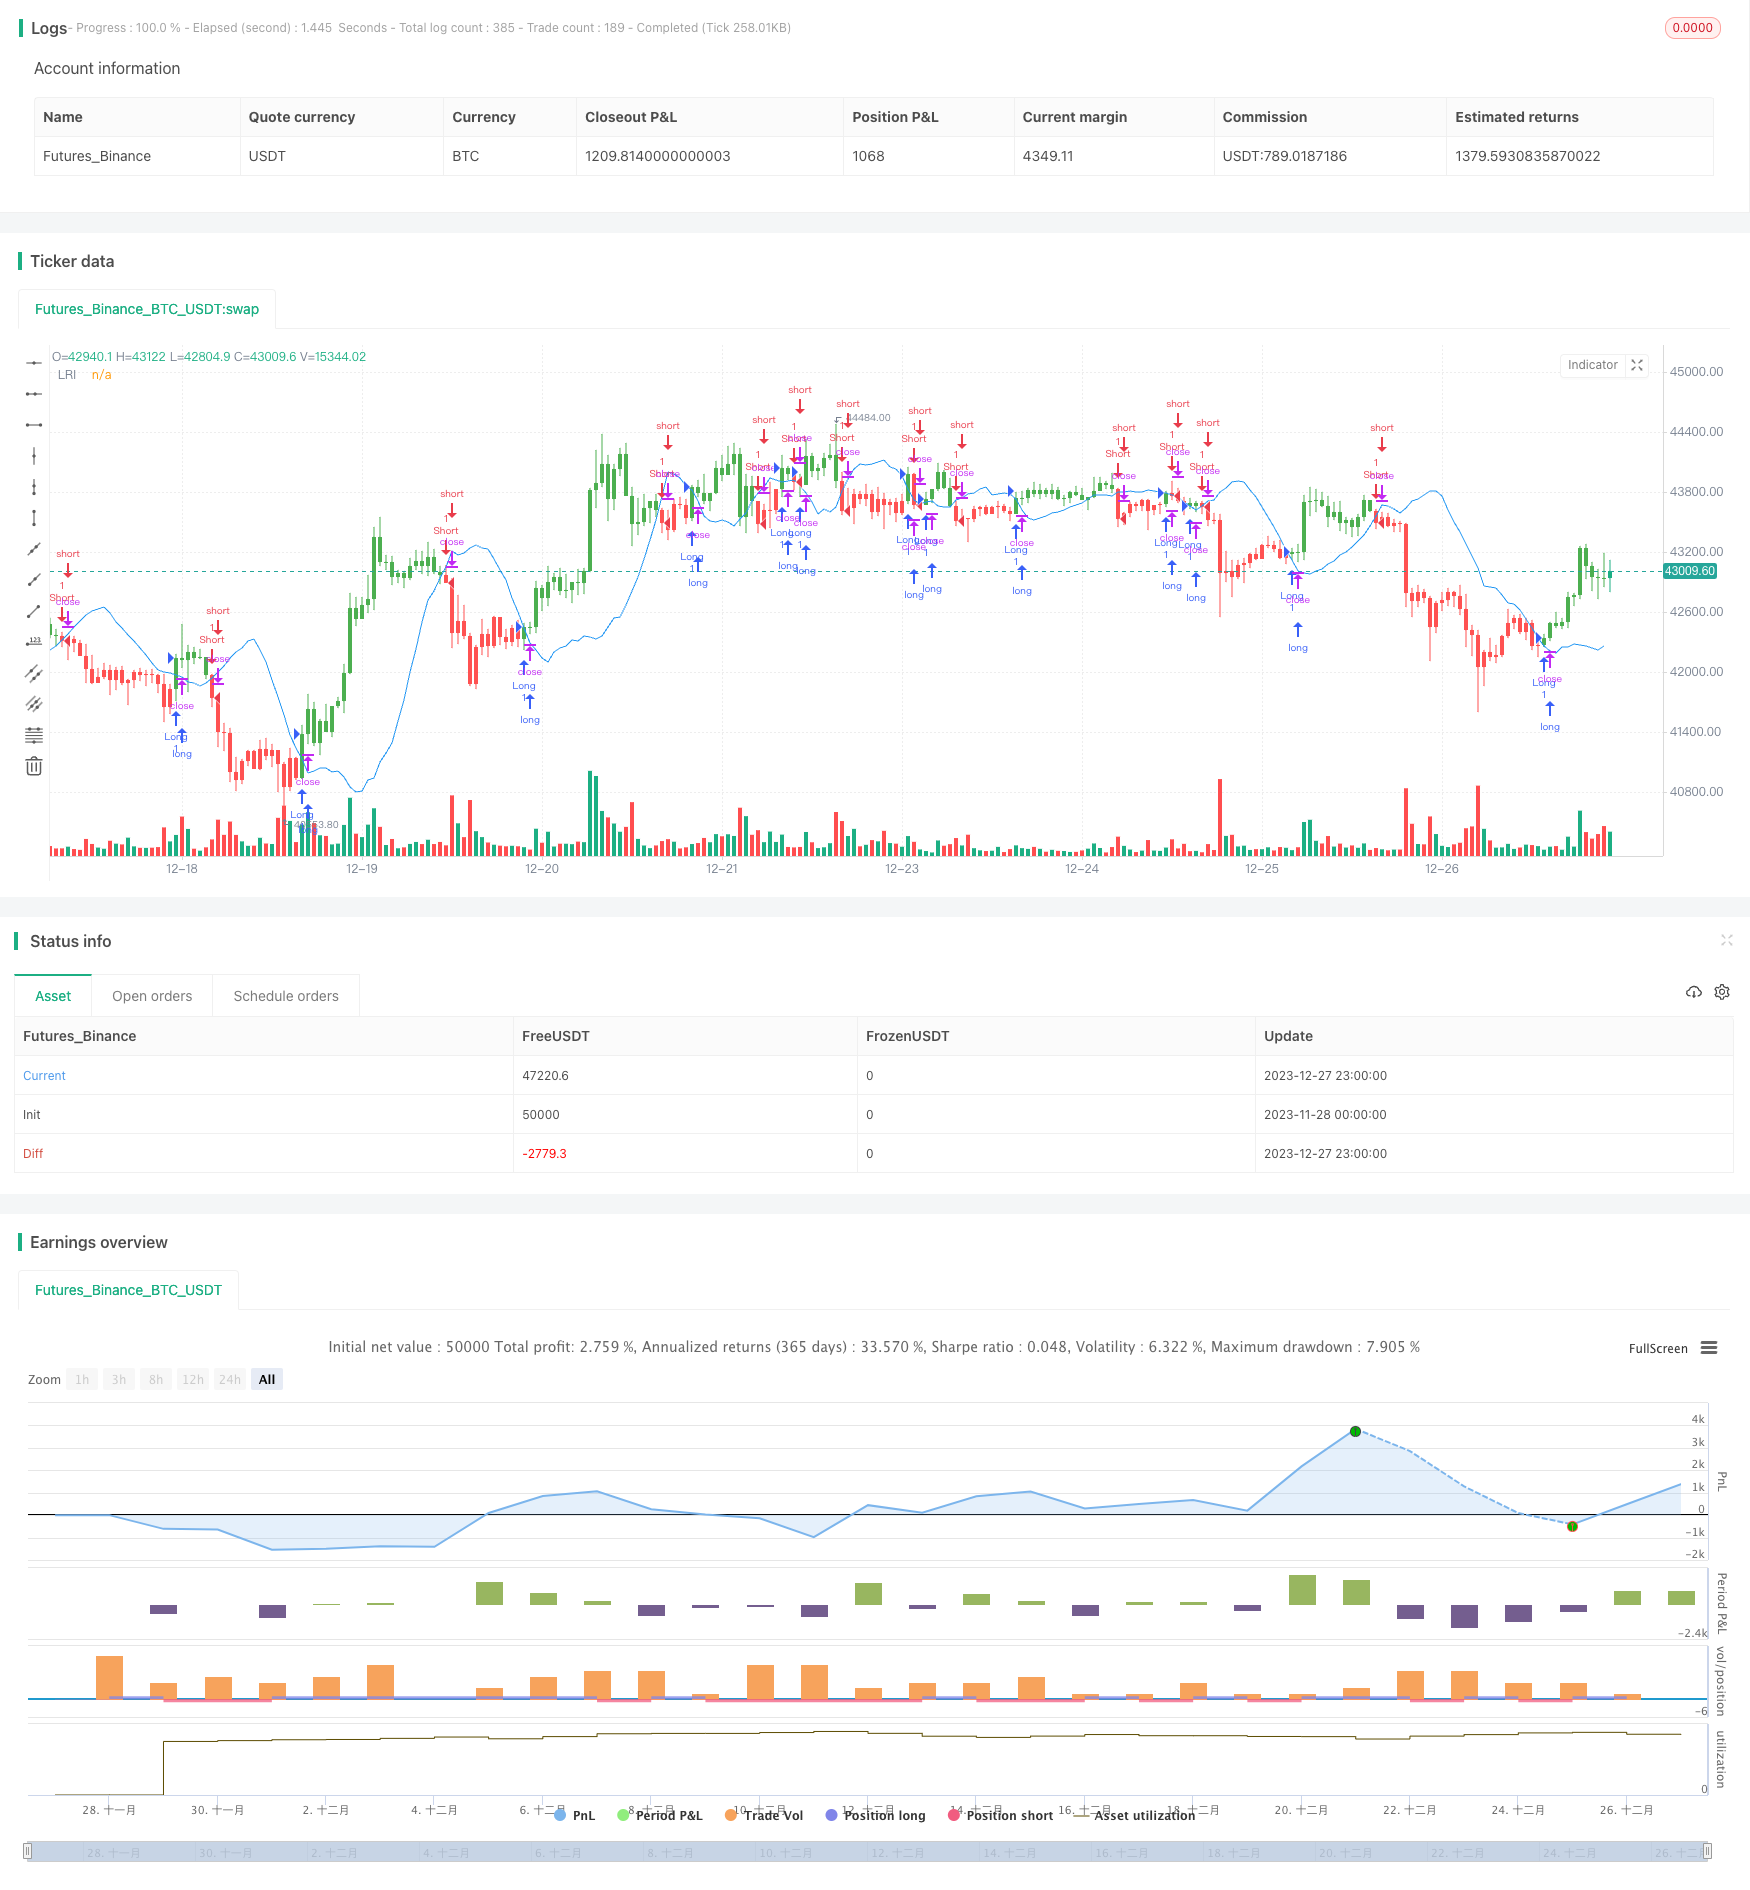
Overview
This strategy uses linear regression techniques to calculate the linear regression intercept and uses it as a trading signal to construct a quantitative trading strategy. By analyzing the price time series of stocks, this strategy fits a linear regression trend line and uses the linear regression intercept to judge whether prices are overestimated or underestimated, thereby generating trading signals.
Strategy Principle
The linear regression intercept indicates the predicted value of Y (usually the price) when the time series value X is 0. This strategy presets the parameter Length, takes the closing price as the source sequence, and calculates the linear regression intercept (xLRI) of the most recent Length days. When the closing price is higher than xLRI, go long; when the closing price is lower than xLRI, go short.
The specific calculation formula is as follows:
xX = Length *(Length - 1)* 0.5
xDivisor = xX *xX - Length* Length *(Length - 1) *(2 * Length - 1) / 6
xXY = Σ(i *Closing Price[i]), i from 0 to Length-1
xSlope = (Length *xXY - xX* Σ(Closing Price, Length))/ xDivisor
xLRI = (Σ(Closing Price, Length) - xSlope * xX) / Length
Through such calculations, the linear regression intercept xLRI for the most recent Length days can be obtained. The strategy judges the price highs and lows based on it to generate trading signals.
Advantages
This strategy has the following advantages:
- Using linear regression techniques, it has certain predictive and trend judgment capabilities for prices.
- Fewer parameters, simpler model, easy to understand and implement.
- Customizable parameter Length to adjust strategy flexibility.
Risks and Solutions
This strategy also has some risks:
- Linear regression fitting is merely a statistical fitting based on historical data, with limited ability to predict future price trends.
- If the company's fundamentals undergo major changes, the results of linear regression fitting may become invalid.
- Improper setting of the parameter Length may lead to overfitting.
Countermeasures:
- Appropriately shorten the parameter Length to prevent overfitting.
- Pay attention to changes in the company's fundamentals and intervene manually to close positions when necessary.
- Adopt adaptive parameter Length to dynamically adjust according to market conditions.
Optimization Directions
This strategy can also be optimized in the following aspects:
- Add a stop loss mechanism to control single loss.
- Combine with other indicators to form a combination strategy to improve stability.
- Add parameter self-adaptive optimization module to make Length parameter change dynamically.
- Add a position control module to prevent over-trading.
Summary
This strategy constructs a simple quantitative trading strategy based on the linear regression intercept. Overall, the strategy has some economic value, but there are also some risks to note. Through continuous optimization, it is expected to further improve the stability and profitability of the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | Length |
| v_input_2_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-11-28 00:00:00
end: 2023-12-28 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 21/03/2018
// Linear Regression Intercept is one of the indicators calculated by using the
// Linear Regression technique. Linear regression indicates the value of the Y
// (generally the price) when the value of X (the time series) is 0. Linear
// Regression Intercept is used along with the Linear Regression Slope to create
// the Linear Regression Line. The Linear Regression Intercept along with the Slope
// creates the Regression line.
//
// You can change long to short in the Input Settings
// WARNING:
//  - For purpose educate only
//  - This script to change bars colors.
////////////////////////////////////////////////////////////
strategy(title="Line Regression Intercept Backtest", overlay = true)
Length = input(14, minval=1)
xSeria = input(title="Source", defval=close)
reverse = input(false, title="Trade reverse")
xX = Length * (Length - 1) * 0.5
xDivisor = xX * xX - Length * Length * (Length - 1) * (2 * Length - 1) / 6
xXY = 0
for i = 0 to Length-1
	xXY := xXY + (i * xSeria[i])
xSlope = (Length * xXY - xX * sum(xSeria, Length)) / xDivisor
xLRI = (sum(xSeria, Length) - xSlope * xX) / Length
pos = iff(close > xLRI, 1,
       iff(close < xLRI, -1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(xLRI, color=blue, title="LRI")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quant-Strategy-Based-on-Linear-Regression-Intercept.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h