Quantitative Investment Strategy Based on Monthly Buy Date
The core idea of this strategy is to find the best buy date each month by buying digital assets on that date and selling them at the end of the month, in order to achieve optimal investment returns. This strategy is…
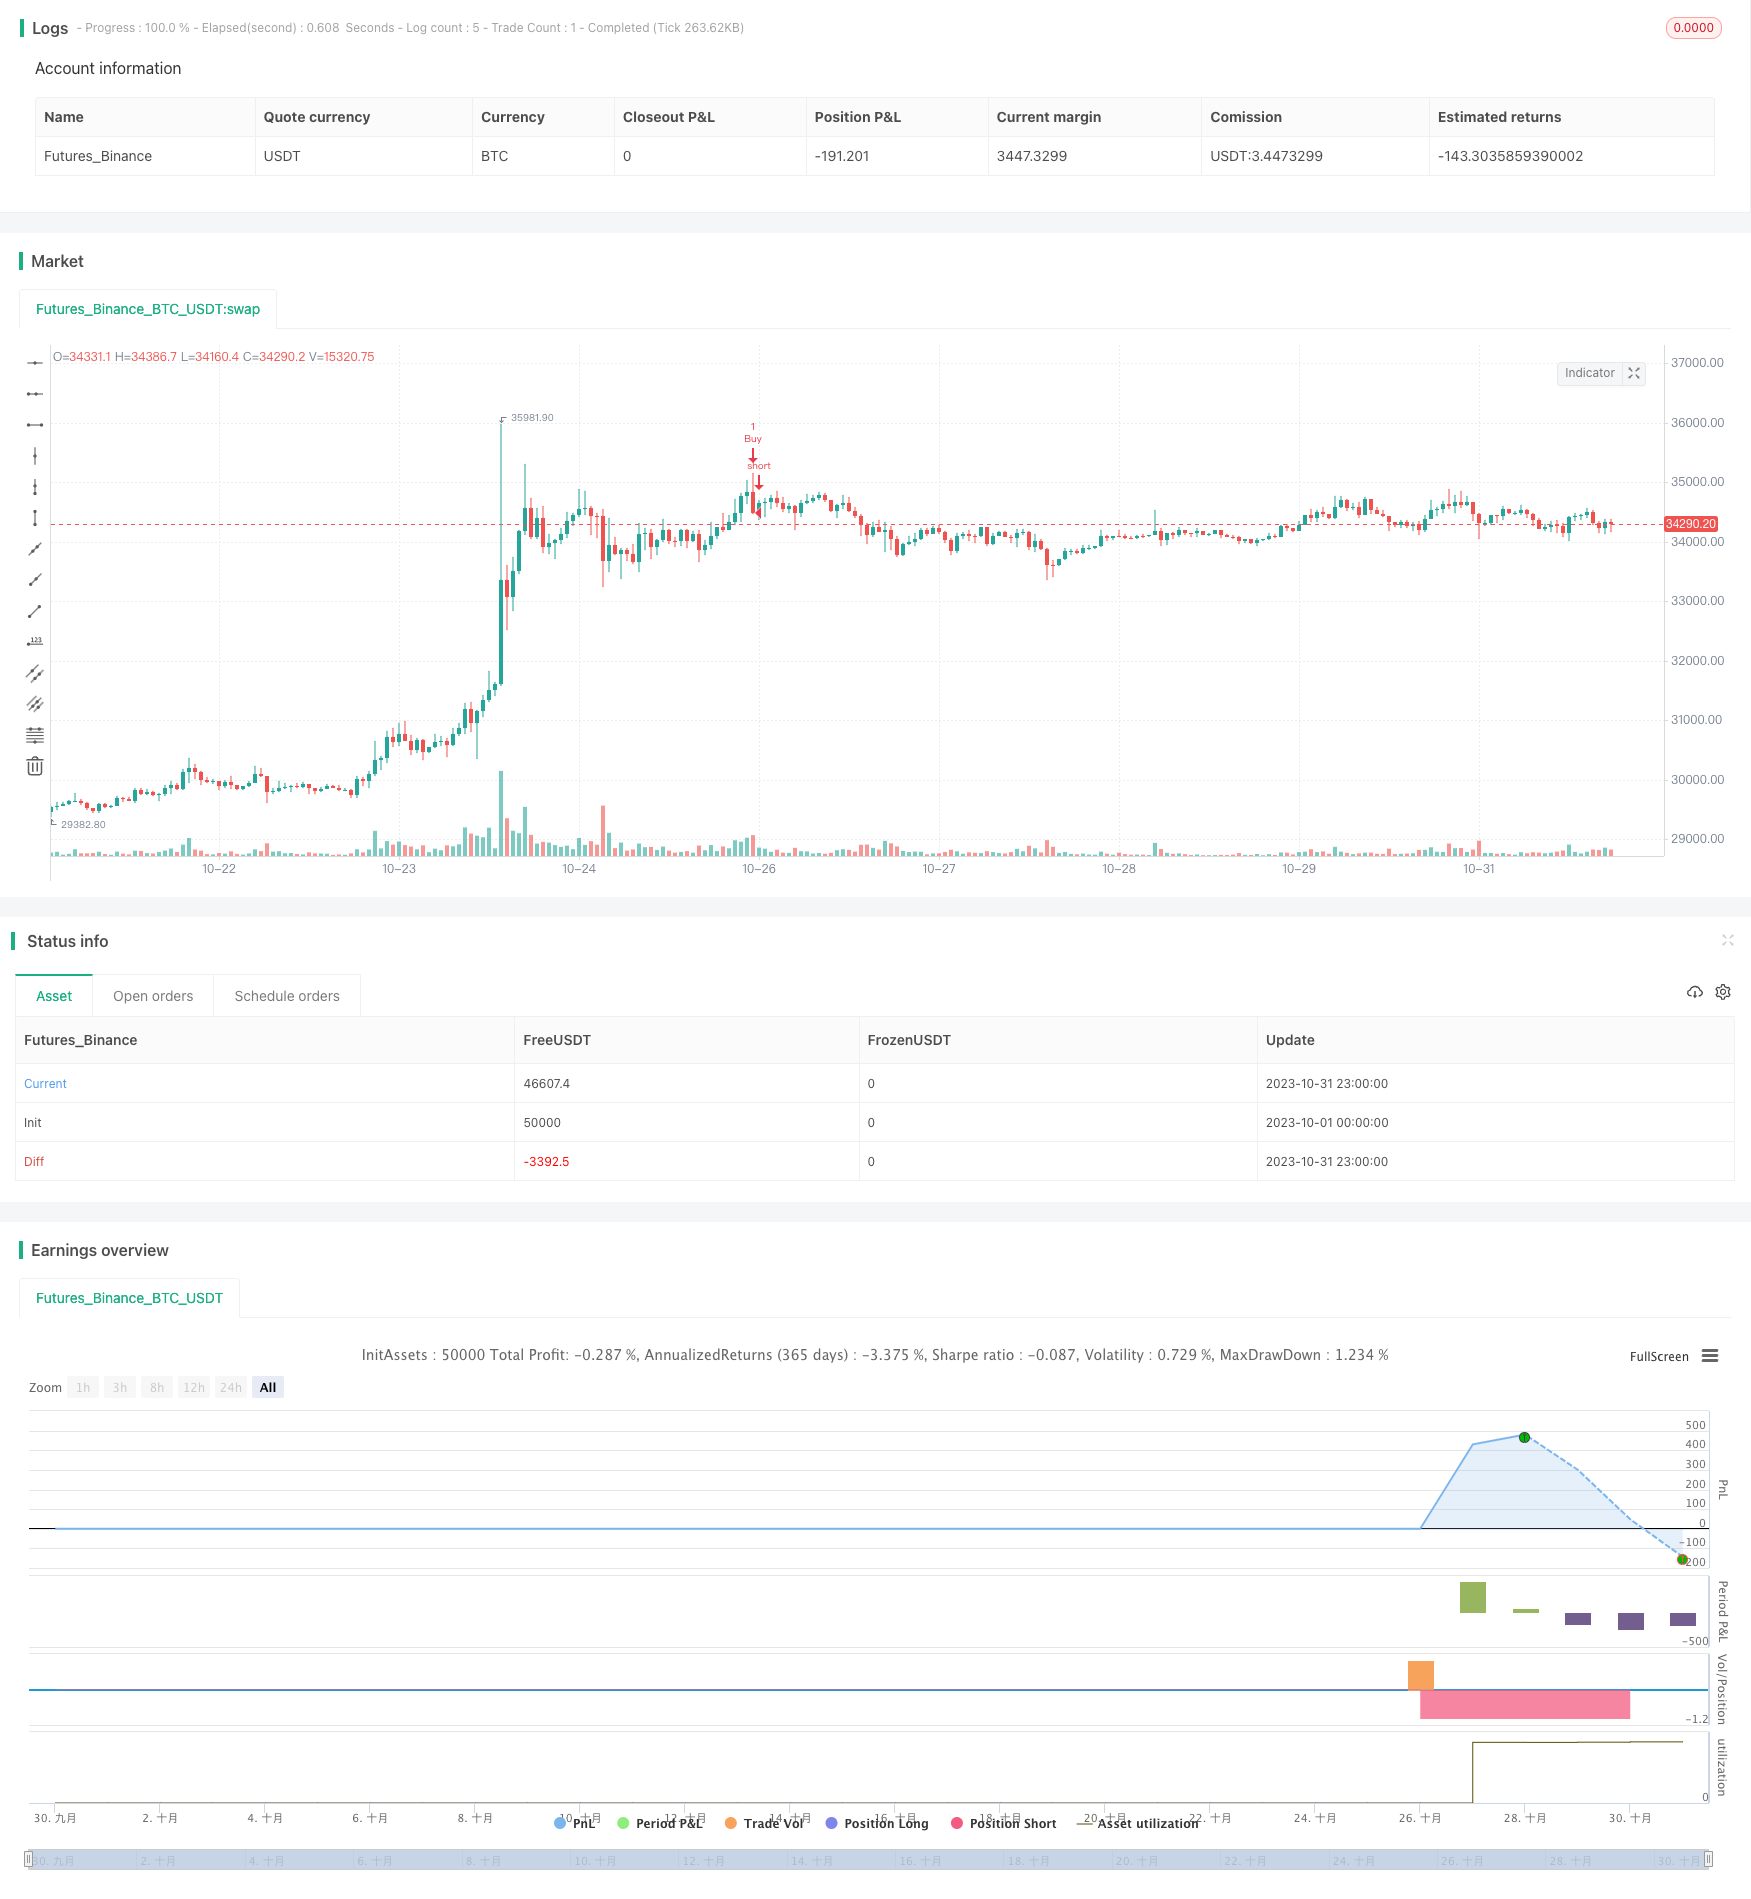
Overview
The core idea of this strategy is to find the best buy date each month by buying digital assets on that date and selling them at the end of the month, in order to achieve optimal investment returns. This strategy is suitable for investors who want to obtain excess returns by taking advantage of intraday price fluctuations.
Strategy Principle
The strategy runs based on the user-defined monthly buy date and sell date. It goes long on the buy date by buying assets, and closes the position on the sell date if set. Otherwise, it closes the position on the strategy end date. This can test the profit difference from different monthly buy dates.
The logic for buy signal is: if it is the user-defined buy date and within the effective date range of the strategy, go long.
The logic for close position signal is: if the sell date is set and it is the sell date now, close position; if no sell date but beyond strategy end date, also close position.
Advantages of the Strategy
- Can find the date of largest price fluctuation each month to obtain excess returns via high frequency intraday trading
- Can identify the optimal buy point by comparing profit patterns from different buy dates
- Can determine if the optimal buy date changes based on key events of the month
- Can balance short-term and long-term trading by setting different sell dates
Risks and Solutions
Price crash risk after buying
- Set stop loss to limit maximum loss
- Choose assets with high liquidity to avoid extreme price swing
Change of optimal buy date
- Monitor data change history and timely adjust optimal buy point
- Reduce position size during high risk periods
Loss caused by incorrect parameter setup
- Test different parameters incrementally and compare profit difference
- Select representative time range for test
Optimization Directions
Consider more factors in determining entry point
- Consider impact of key news events of the month on price
- Analyze price trends of related digital assets
- Add machine learning models to determine optimal timing
Optimize position management mechanism
- Set dynamic take profit to close position
- Adjust position size based on volatility
- Consider holding position across periods
Expand to other trading markets
- Apply to more digital currency trading pairs
- Apply to stocks, forex etc.
- Set up cross-market arbitrage strategies
Summary
This strategy finds the date of largest intraday price swing each month by testing profit difference from different buy dates. It can bring excess returns for investors seeking profits from high frequency intraday trading. Further improvement on determining entry timing, position management and expanding application scope will enhance the stability and profitability of the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_7 | 26 | Entry Day |
| v_input_8 | 6 | Exit Day |
| v_input_9 | false | Close position on exit day? |
| v_input_1 | true | (?Starting From)Start Date |
| v_input_2 | true | Start Month |
| v_input_3 | 2021 | Start Year |
| v_input_4 | 2 | (?Until)End Date |
| v_input_5 | 10 | End Month |
| v_input_6 | 2021 | End Year |
Source Pine Script
/*backtest
start: 2023-10-01 00:00:00
end: 2023-10-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © dennis.decoene

//@version=4
strategy(title="Buy and Hold, which day of month is best to buy?", overlay=true)

// Make input options that configure backtest date range
startDate = input(title="Start Date", type=input.integer,
     defval=1, minval=1, maxval=31, group="Starting From")

startMonth = input(title="Start Month", type=input.integer,
     defval=1, minval=1, maxval=12, group="Starting From")

startYear = input(title="Start Year", type=input.integer,
     defval=2021, minval=1800, maxval=2100, group="Starting From")

endDate = input(title="End Date", type=input.integer,
     defval=2, minval=1, maxval=31, group="Until")
endMonth = input(title="End Month", type=input.integer,
     defval=10, minval=1, maxval=12, group="Until")
endYear = input(title="End Year", type=input.integer,
     defval=2021, minval=1800, maxval=2100, group="Until")

entryday = input(title="Entry Day", type=input.integer,
     defval=26, minval=1, maxval=31, tooltip="When to enter (buy the asset) each month")
exitday = input(title="Exit Day", type=input.integer,
     defval=6, minval=1, maxval=31, tooltip="When to exit (sell the asset) each month")

useExitDay= input(title="Close position on exit day?", type=input.bool, defval=false, tooltip="Use the Exit Day to close each months position it true or close at the end of the period (if false)")

isEntryDay= (dayofmonth(time)==entryday)
isExitDay= (dayofmonth(time)==exitday-1)


inDateRange = true

if (isEntryDay and inDateRange)
    strategy.entry(id="Buy", long=true)

if (isExitDay and useExitDay)
    strategy.close_all()


// Exit open market position when date range ends
if (not inDateRange and not useExitDay)
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a spread arbitrage engine with WebSocket order routing and leg-risk controls from strategies/Quantitative-Investment-Strategy-Based-on-Monthly-Buy-Date.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bitcoin Trading Strategy Based on Ichimoku CloudPine Script · Arbitrage · 1h
- multiple auxiliary RSI indicator strategyPine Script · Arbitrage · 1d
- Time based Strategy with ATR Take ProfitPine Script · Arbitrage · 1h
- Adaptive Regularized Moving Average Cross Market Arbitrage StrategyPine Script · Arbitrage · 1h
- Dual Reversal Arbitrage StrategyPine Script · Arbitrage · 1h
- High Performance Algorithmic Trading Strategy Based on Quantitative ModelsPine Script · Arbitrage · 1d