Strategy vault / Mean reversion
Quantitative Strategy of Negative Volume Index Reversal
The name of this strategy is Negative Volume Index Reversal Strategy. This strategy uses Negative Volume Index (NVI) and its moving average to construct long and short signals and make reversal trades when conditions…
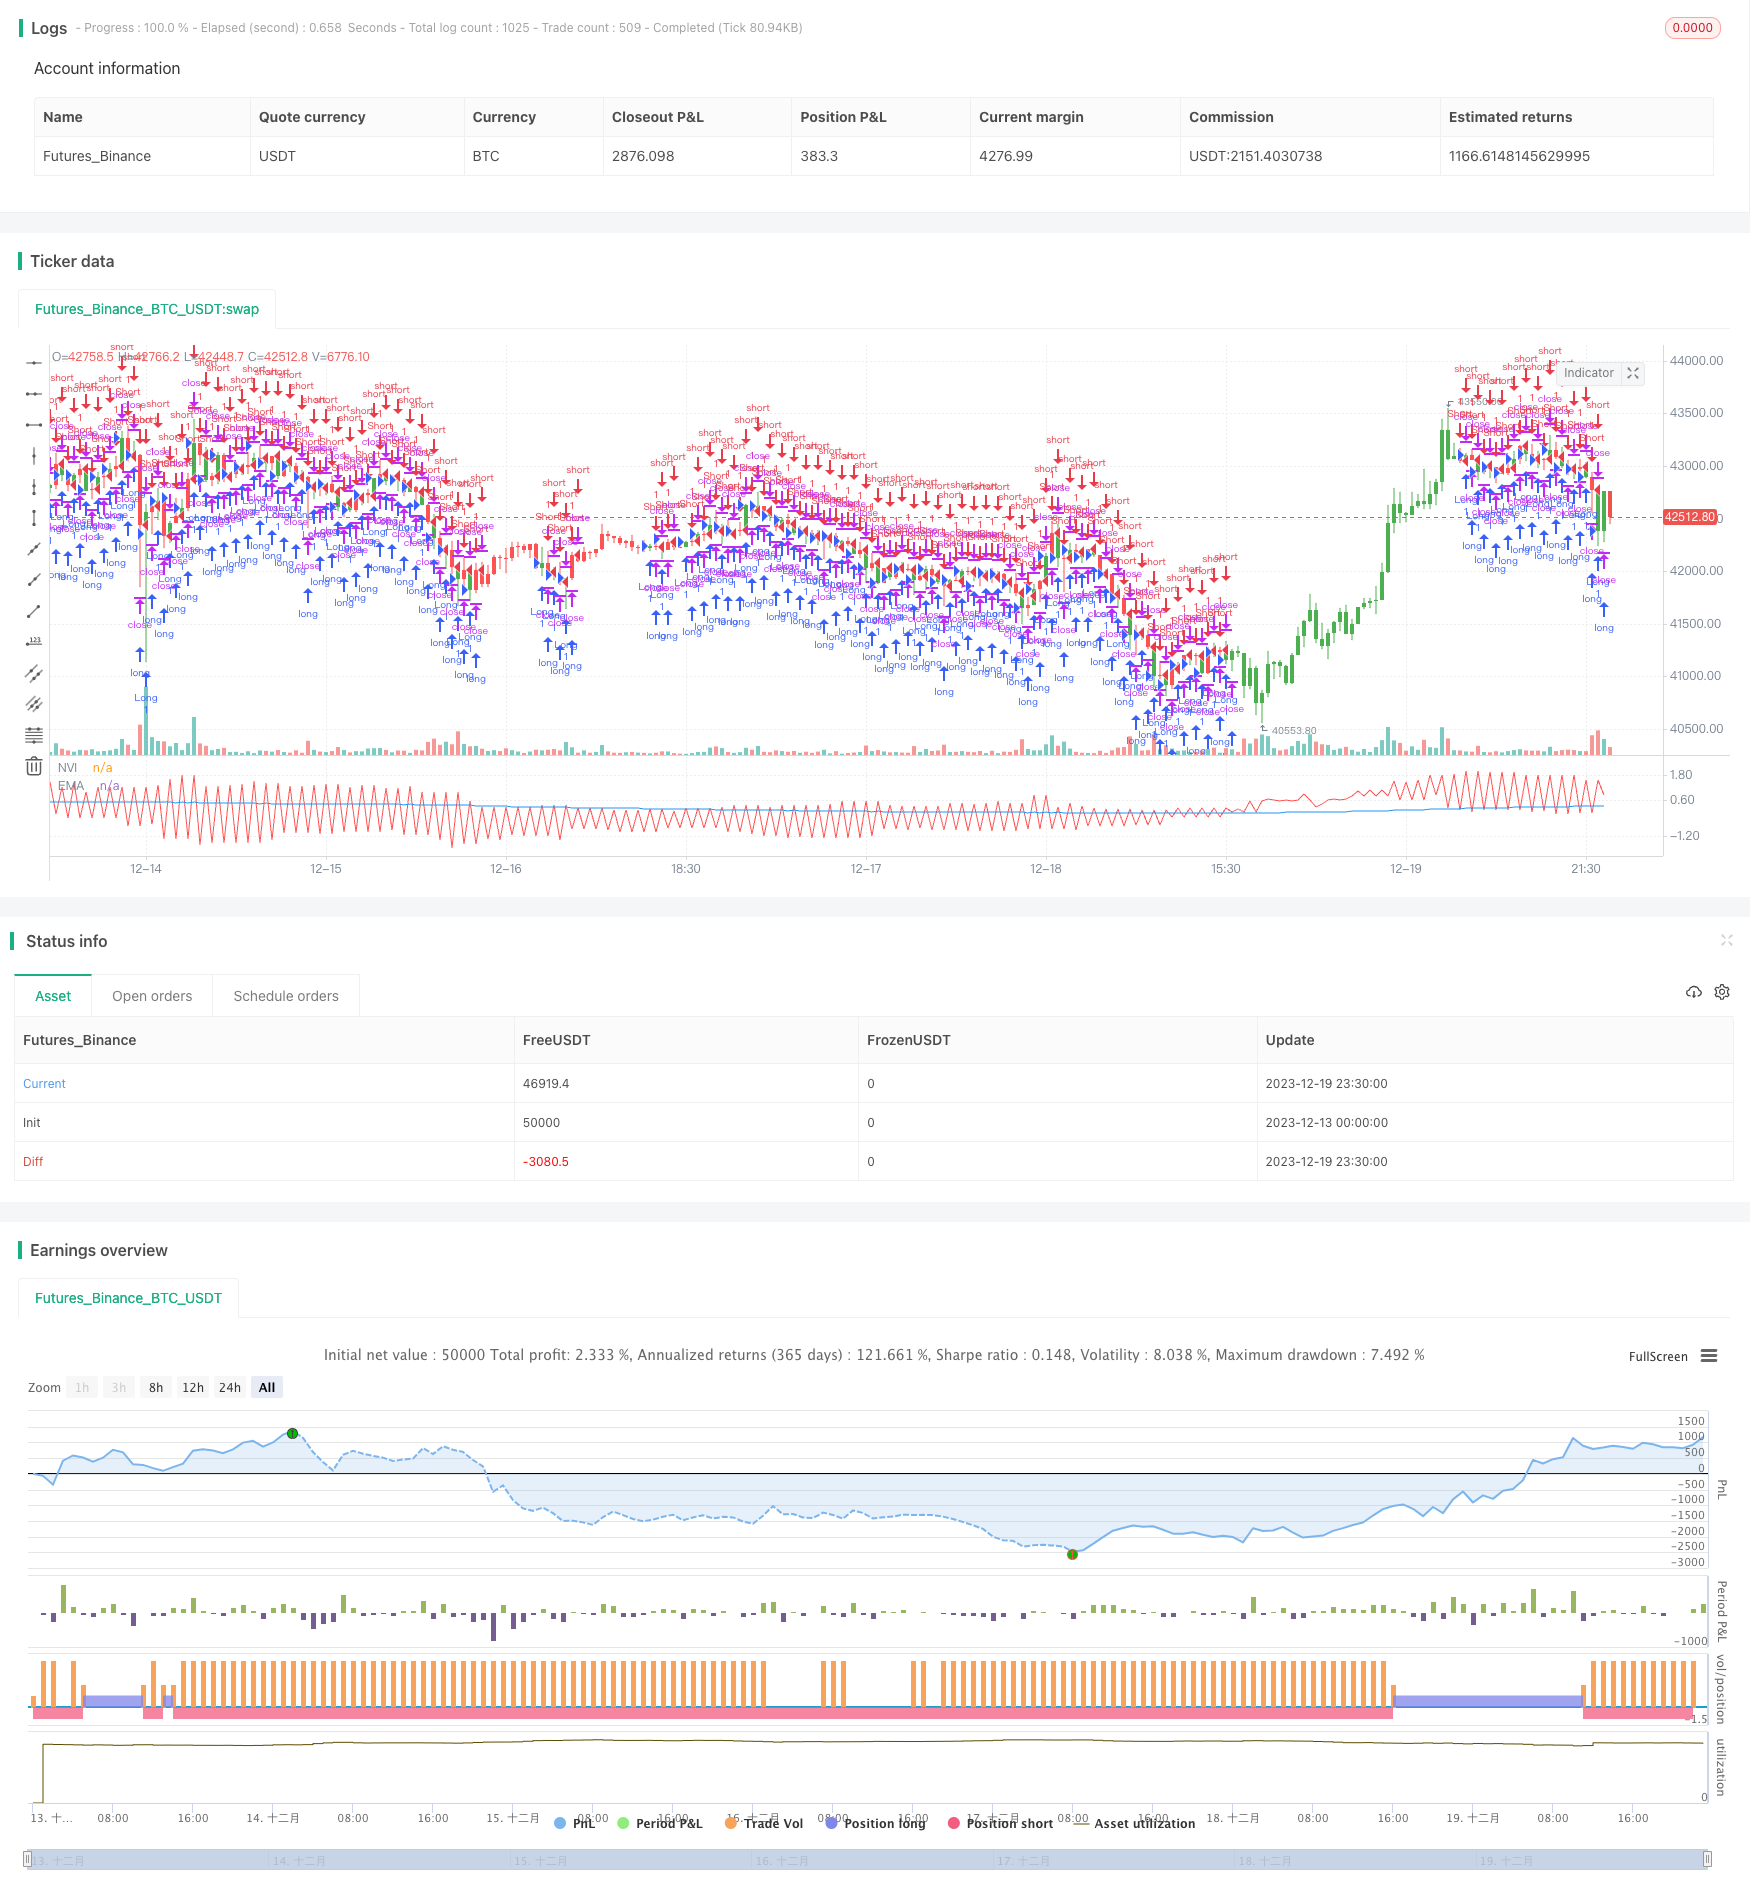
Overview
The name of this strategy is Negative Volume Index Reversal Strategy. This strategy uses Negative Volume Index (NVI) and its moving average to construct long and short signals and make reversal trades when conditions are met. It belongs to the reversal strategy category.
Strategy Principle
The core indicator of the Negative Volume Index reversal strategy is Negative Volume Index (NVI). The calculation formula of NVI is:
If today's volume < previous day's volume: NVI = previous day's NVI + today's price change rate
If today's volume >= previous day's volume: NVI = previous day's NVI
That is to say, NVI is only updated on the day when the trading volume shrinks, and the trend of the price is reflected through the addition and subtraction of the price change rate. The logic of constructing long and short signals with NVI and its moving average is:
When NVI is above its N-day moving average, go long.
When NVI is below its N-day moving average, go short.
So it makes reversal trades when the volume shrinks.
Advantages of the Strategy
The main advantages of the Negative Volume Index reversal strategy are:
Using volume signals can find reversal points and has certain timing advantages.
The strategy logic is simple, easy to understand and implement.
Parameters can be optimized to adapt to different market environments.
Risks of the Strategy
The Negative Volume Index reversal strategy also has some risks:
The accuracy of volume signals cannot be guaranteed, and there is a certain probability of erroneous trades.
Improper parameter settings may lead to over-frequent trading or unclear signals.
Ensure reliable data sources to avoid risks from erroneous volume data.
These risks can be reduced through parameter optimization, stop loss strategies, etc.
Optimization Directions
The Negative Volume Index reversal strategy can be optimized in the following aspects:
Optimize the moving average parameters to find parameters that better describe market characteristics.
Add other indicators for filtering to avoid unnecessary erroneous trades. For example, add larger timeframe trend judgments.
Combine with strong stop loss methods to limit single loss.
Test differences in parameter settings for different varieties, and set adaptive parameters.
Conclusion
The Negative Volume Index reversal strategy makes reversal operations when the trading volume shrinks, aiming to capture potential trend reversal points. This strategy has the advantages of simplicity and easy understanding, and also has certain risks of erroneous trades. The stability and profitability of the strategy can be improved through parameter optimization, adding auxiliary indicators, etc. In general, the Negative Volume Index reversal strategy has good prospects for development and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 255 | EMA_Len |
| v_input_2 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-12-13 00:00:00
end: 2023-12-20 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
////////////////////////////////////////////////////////////
//  Copyright by HPotter 11/08/2017
// The theory behind the indexes is as follows: On days of increasing
// volume, you can expect prices to increase, and on days of decreasing
// volume, you can expect prices to decrease. This goes with the idea of
// the market being in-gear and out-of-gear. Both PVI and NVI work in similar
// fashions: Both are a running cumulative of values, which means you either
// keep adding or subtracting price rate of change each day to the previous day`s
// sum. In the case of PVI, if today`s volume is less than yesterday`s, don`t add
// anything; if today`s volume is greater, then add today`s price rate of change.
// For NVI, add today`s price rate of change only if today`s volume is less than
// yesterday`s.
//
// You can change long to short in the Input Settings
// Please, use it only for learning or paper trading. Do not for real trading.
////////////////////////////////////////////////////////////
strategy(title="Negative Volume Index Backtest", shorttitle="NVI Str")
EMA_Len = input(255, minval=1)
reverse = input(false, title="Trade reverse")
xROC = roc(close, 1)
nRes = iff(volume < volume[1], nz(nRes[1], 0) + xROC, nz(nRes[1], 0))
nResEMA = ema(nRes, EMA_Len)
pos = iff(nRes > nResEMA, 1,
	     iff(nRes < nResEMA, -1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(nRes, color=red, title="NVI")
plot(nResEMA, color=blue, title="EMA")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quantitative-Strategy-of-Negative-Volume-Index-Reversal.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 1 2 3 Pattern Quantitative Trading Strategy with EMAs MACD and 4th Candle ExtensionPine Script · Mean reversion · 1h
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Advanced Quantitative Trend Following and Cloud Reversal Composite Trading StrategyPine Script · Mean reversion · 1d