Quantitative Trading Strategy Based on Random Numbers
The core idea of this strategy is to simulate probability events such as coin flipping and dice rolling using random numbers to determine long or short positions, thus implementing random trading. This kind of…
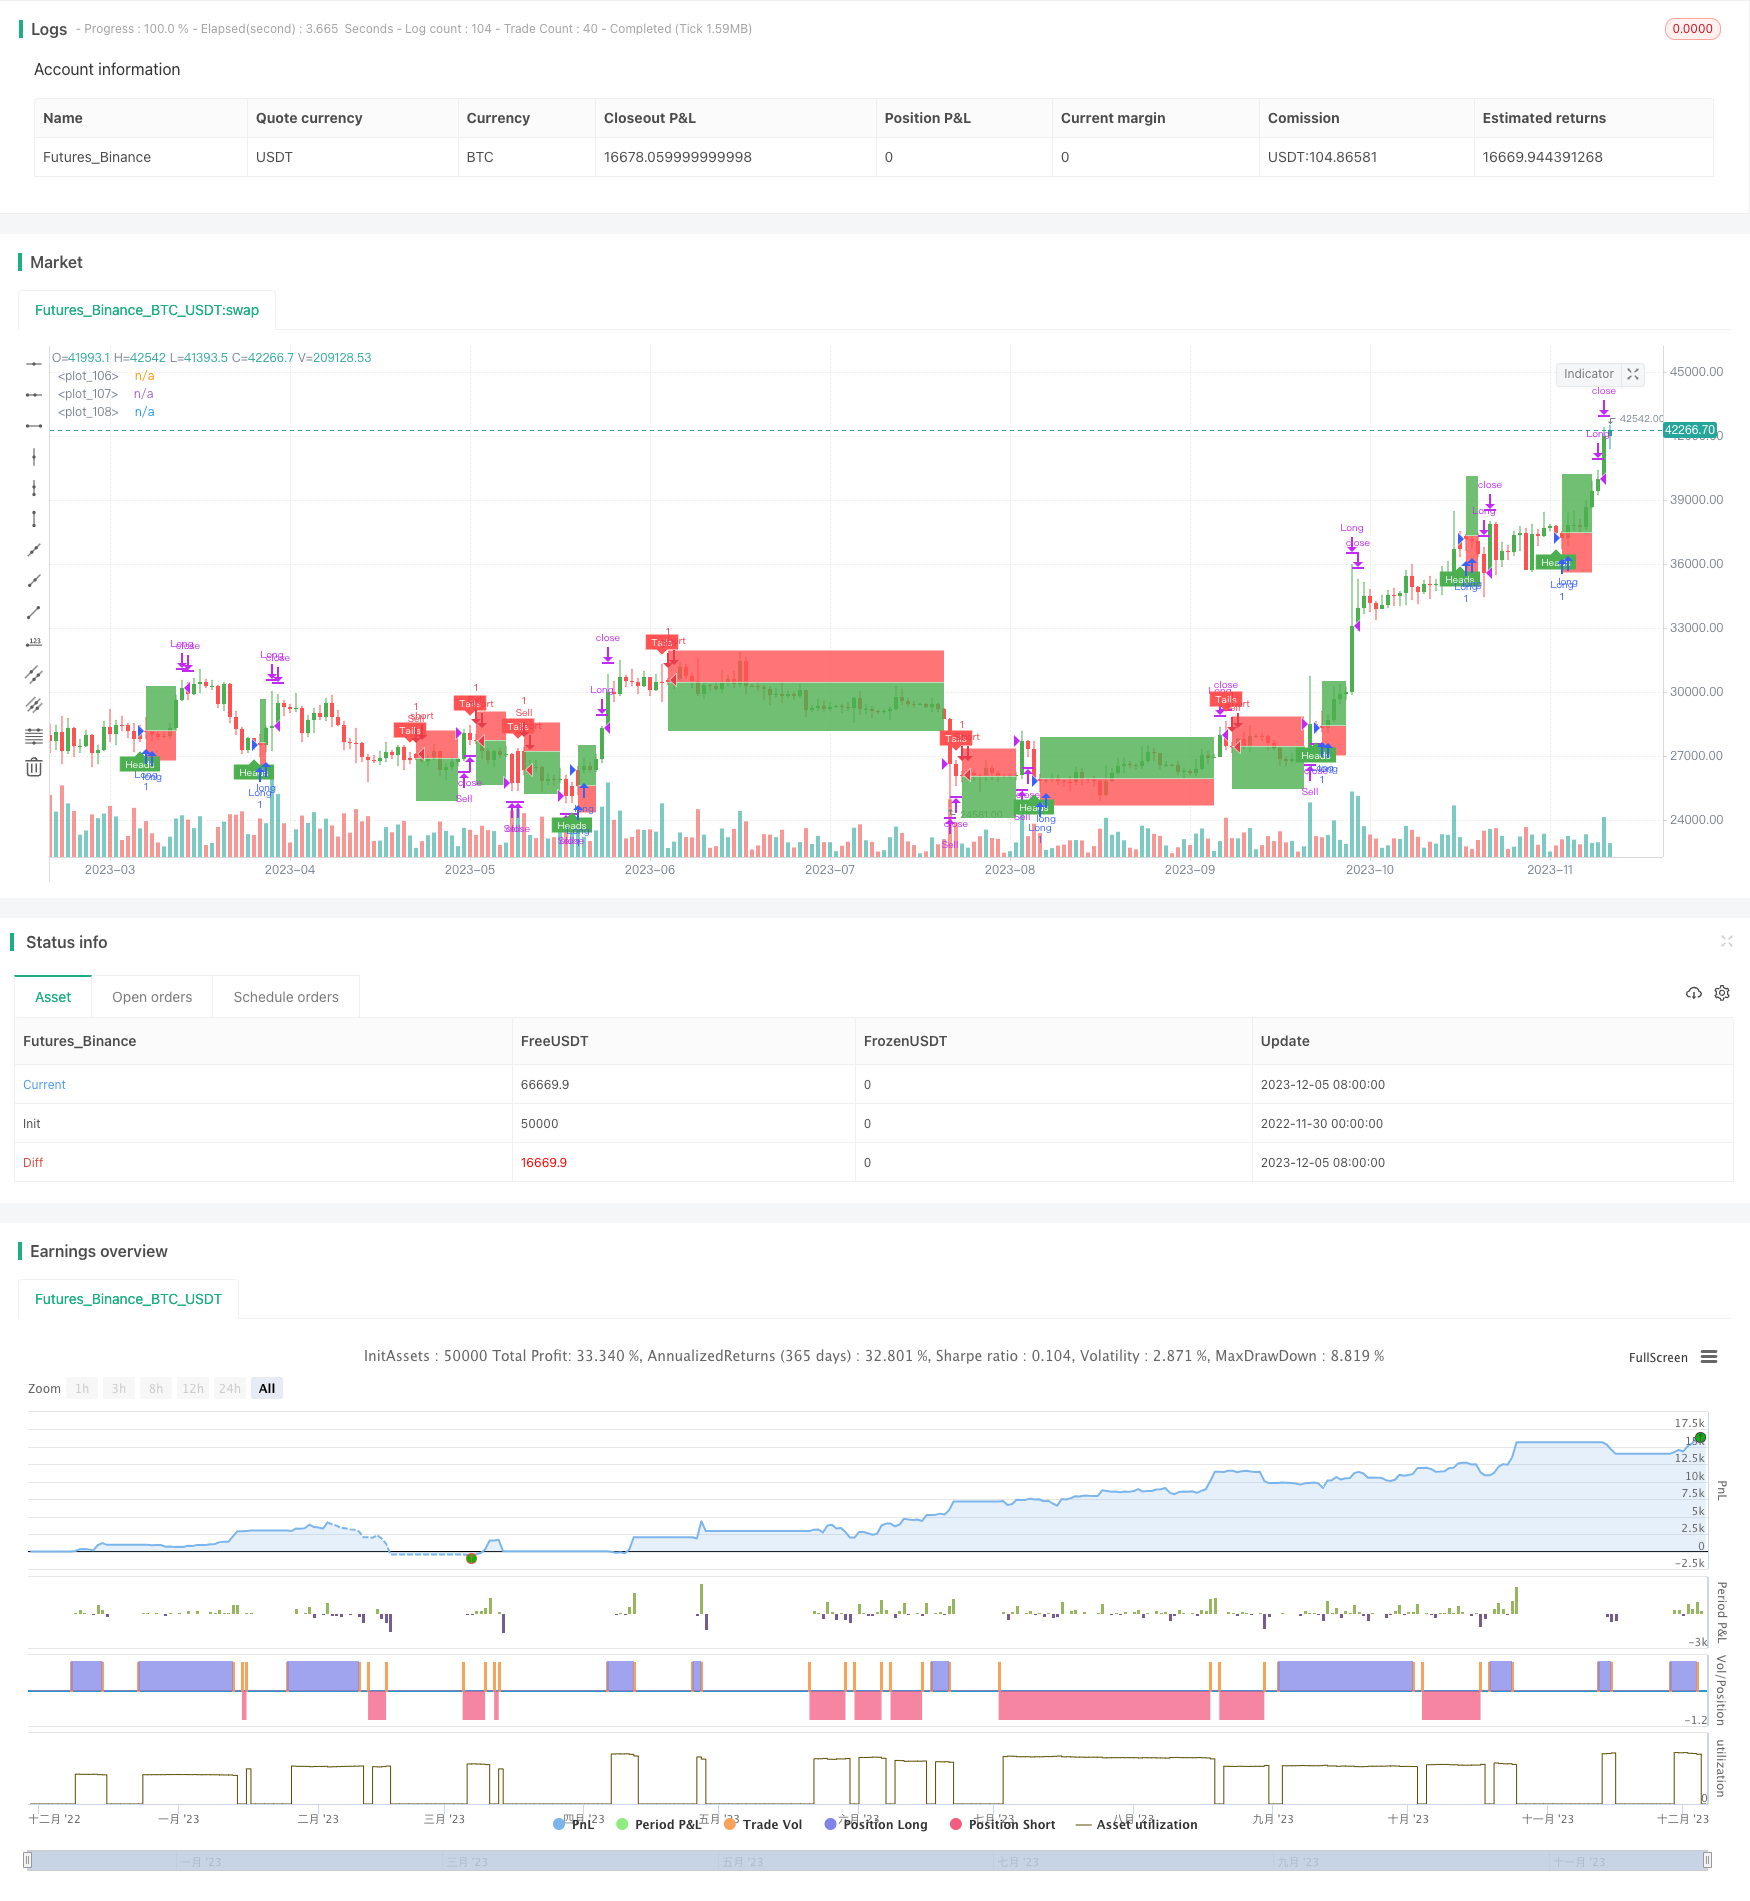
Overview
The core idea of this strategy is to simulate probability events such as coin flipping and dice rolling using random numbers to determine long or short positions, thus implementing random trading. This kind of trading strategy can be used for simulation testing and also as a basic framework for more complex strategy development.
Strategy Principle
Use the
flipvariable to simulate random events and determine long or short based on thecoinLabelrandom number size.Use
riskandratioto set stop loss and take profit lines.Trigger the next trading signal randomly according to the set maximum cycle number.
Control whether to display the close position box through the
plotBoxvariable.stoppedOutandtakeProfitvariables are used to detect stop loss or take profit.Provide backtesting capabilities to test strategy performance.
Advantage Analysis
The code structure is clear and easy to understand and secondary develop.
The UI interaction is friendly and various parameters can be adjusted through the graphical interface.
The randomness is strong and not affected by market fluctuations, with high reliability.
Better return on investment can be obtained through parameter optimization.
Can be used as a demonstration or test for other strategies.
Risk Analysis
Random trading cannot judge the market and there is a certain profit risk.
Unable to determine the optimal parameter combination, repeated testing is required.
There is a risk of super correlation that may result from overly dense random signals.
It is recommended to use stop loss and take profit mechanisms to control risks.
Risks can be reduced by appropriately extending the trading interval.
Optimization Directions
Incorporate more complex factors to generate random signals.
Increase trading varieties to expand test scope.
Optimize UI interaction and increase strategy control capabilities.
Provide more test tools and indicators for parameter optimization.
Can be used as a trading signal or stop loss take profit component added to other strategies.
Summary
The overall framework of this strategy is complete, generating trading signals based on random events, with high reliability. At the same time, it provides parameter adjustment, backtesting, and charting capabilities. It can be used to test novice strategy development, and also as a basic module for other strategies. Through appropriate optimization, the strategy performance can be further improved.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | ------- Trade Activity ------- |
| v_input_2 | 25 | Max Bars between Coin Filps |
| v_input_3 | false | ------- Position Settings ------- |
| v_input_4 | 5 | Risk in % |
| v_input_5 | 1.5 | Risk to Reward Ratio x:1 |
| v_input_6 | false | ------- Plot Options ------- |
| v_input_7 | true | Show Position Boxes |
| v_input_8 | false | ------- Back Testing ------- |
| v_input_9 | true | Run Strategy Back Test |
| v_input_10 | false | Use Custom Date Range for back test |
| v_input_11 | 2021 | Test Start Year |
| v_input_12 | true | Test Start Month |
| v_input_13 | true | Test Start Day |
| v_input_14 | 2021 | Test Stop Year |
| v_input_15 | 5 | Test Stop Month |
| v_input_16 | true | Test Stop Day |
Source Pine Script
/*backtest
start: 2022-11-30 00:00:00
end: 2023-12-06 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © melodicfish

//@version=4
strategy("Coin Flipper Pro",overlay=true,max_bars_back=100)

// ======= User Inputs variables=========

h1=input(title="------- Trade Activity -------",defval=false)
maxBars=input(25.0,title="Max Bars between Coin Filps",step=1.0,minval=4.0)

h2=input(title="------- Position Settings -------",defval=false)
risk=input(defval=5.0,title="Risk in % ",type=input.float, minval=0.001 ,step=0.1)
ratio= input(defval=1.5,title="Risk to Reward Ratio x:1 ",type=input.float, minval=0.001,step=0.1)

h3=input(title="------- Plot Options -------",defval=false)
showBox=input(defval=true, title="Show Position Boxes")

h4=input(title="------- Back Testing -------",defval=false)
runTest=input(defval=true, title="Run Strategy Back Test")
customTime=input(defval=false, title="Use Custom Date Range for back test")


tsYear = input(2021,minval=1000,maxval=9999,title= "Test Start Year")
tsMonth = input(1,minval=1,maxval=12,title= "Test Start Month")
tsDay = input(1,minval=1,maxval=31,title= "Test Start Day")
start = timestamp(tsYear,tsMonth,tsDay,0,0)

teYear = input(2021,minval=1000,maxval=9999,title=  "Test Stop Year")
teMonth = input(5,minval=1,maxval=12,title=  "Test Stop Month")
teDay = input(1,minval=1,maxval=31,title=  "Test Stop Day")
end = timestamp(teYear,teMonth,teDay,0,0)

// ======= variables =========
var barsBetweenflips=25
var coinFlipResult=0.0
var flip=true
var coinLabel=0.0
var stoppedOut= true
var takeProfit=true
var posLive=false
var p1=0.0
var p2=0.0
var p3=0.0
var plotBox=false
var posType=0
long=false
short=false


// ===== Functions ======

getColor() =>
    round(random(1,255))


// ===== Logic ========
if barssince(flip==true)>barsBetweenflips and posLive==false
    flip:=true
    coinLabel:=random(1,10)

    // Candle Colors
candleColor= flip==true and flip[1]==false and barstate.isconfirmed==false?color.rgb(getColor(),getColor(),getColor(),0):flip==false and close>=open?color.green:color.red
candleColor:= barstate.ishistory==true and close>=open?color.green: barstate.ishistory==true and close<open? color.red:candleColor
barcolor(candleColor)

if flip[1]==true and posLive==false
    flip:=false
    barsBetweenflips:=round(random(3,round(maxBars)))
    posLive:=true

long:= flip[1]==true and coinLabel[1]>=5.0
short:= flip[1]==true and coinLabel[1]<5.0


    // Calculate Position Boxes
if long==true and posType!=1

    riskLDEC=1-(risk/100)
    p1:= close[1]*(1+((risk/100)*ratio)) // TargetLine
    p2:=close[1]
    p3:= close[1]*riskLDEC // StopLine
    plotBox:=true
    posType:=1

if short==true and posType!=-1

    riskSDEC=1-((risk*ratio)/100)
    p1:= close[1]*riskSDEC   // TargetLine
    p2:=close[1]
    p3:= close[1]*(1+(risk/100)) // StopLine
    plotBox:=true
    posType:=-1


    // Check Trade Status
stoppedOut:= posType==1 and long==false and low<= p3? true: posType==-1 and short==false and high>=p3? true: false
takeProfit:= posType==1 and long == false and high>= p1? true: posType==-1 and short==false and low<=p1? true: false
if stoppedOut==true or takeProfit==true
    posType:=0
    plotBox:=false
    posLive:=false


// ====== Plots ========
plot1=plot(plotBox and showBox? p1:na,style=plot.style_linebr,color=color.white, transp= 100)
plot2=plot(plotBox and showBox? p2:na,style=plot.style_linebr,color=color.white, transp= 100)
plot3=plot(plotBox and showBox? p3:na,style=plot.style_linebr,color=color.white, transp= 100)
fill(plot1,plot2,color= color.green)
fill(plot2,plot3,color= color.red)
plotshape(flip==true and flip[1]==false and coinLabel>=5.0,style=shape.labelup,location=location.belowbar, color=color.green,size=size.tiny,title="short label",text="Heads",textcolor=color.white)
plotshape(flip==true and flip[1]==false and coinLabel<5.0,style=shape.labeldown,location=location.abovebar, color=color.red,size=size.tiny,title="short label",text="Tails",textcolor=color.white)
if stoppedOut==true
    label.new(bar_index-1, p3, style=label.style_xcross, color=color.orange)
if takeProfit==true
    label.new(bar_index-1, p1, style=label.style_flag, color=color.blue)


if runTest==true and customTime==false or runTest==true and customTime==true and time >= start and time <= end
    strategy.entry("Sell", strategy.short,when=short==true)
    strategy.close("Sell", comment="Close Short", when=stoppedOut==true or takeProfit==true)
    strategy.entry("Long", strategy.long,when=long==true)
    strategy.close("Long",comment="Close Long", when= stoppedOut==true or takeProfit==true )
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-07. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quantitative-Trading-Strategy-Based-on-Random-Numbers.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.