Strategy vault / Mean reversion
Quantitative Trading Strategy for Bottom Reversal
This strategy identifies market bottom by calculating fast RSI indicator and K-line entity filter to determine oversold status. When fast RSI drops below 10 and K-line entity expands, it considers reversal signal…
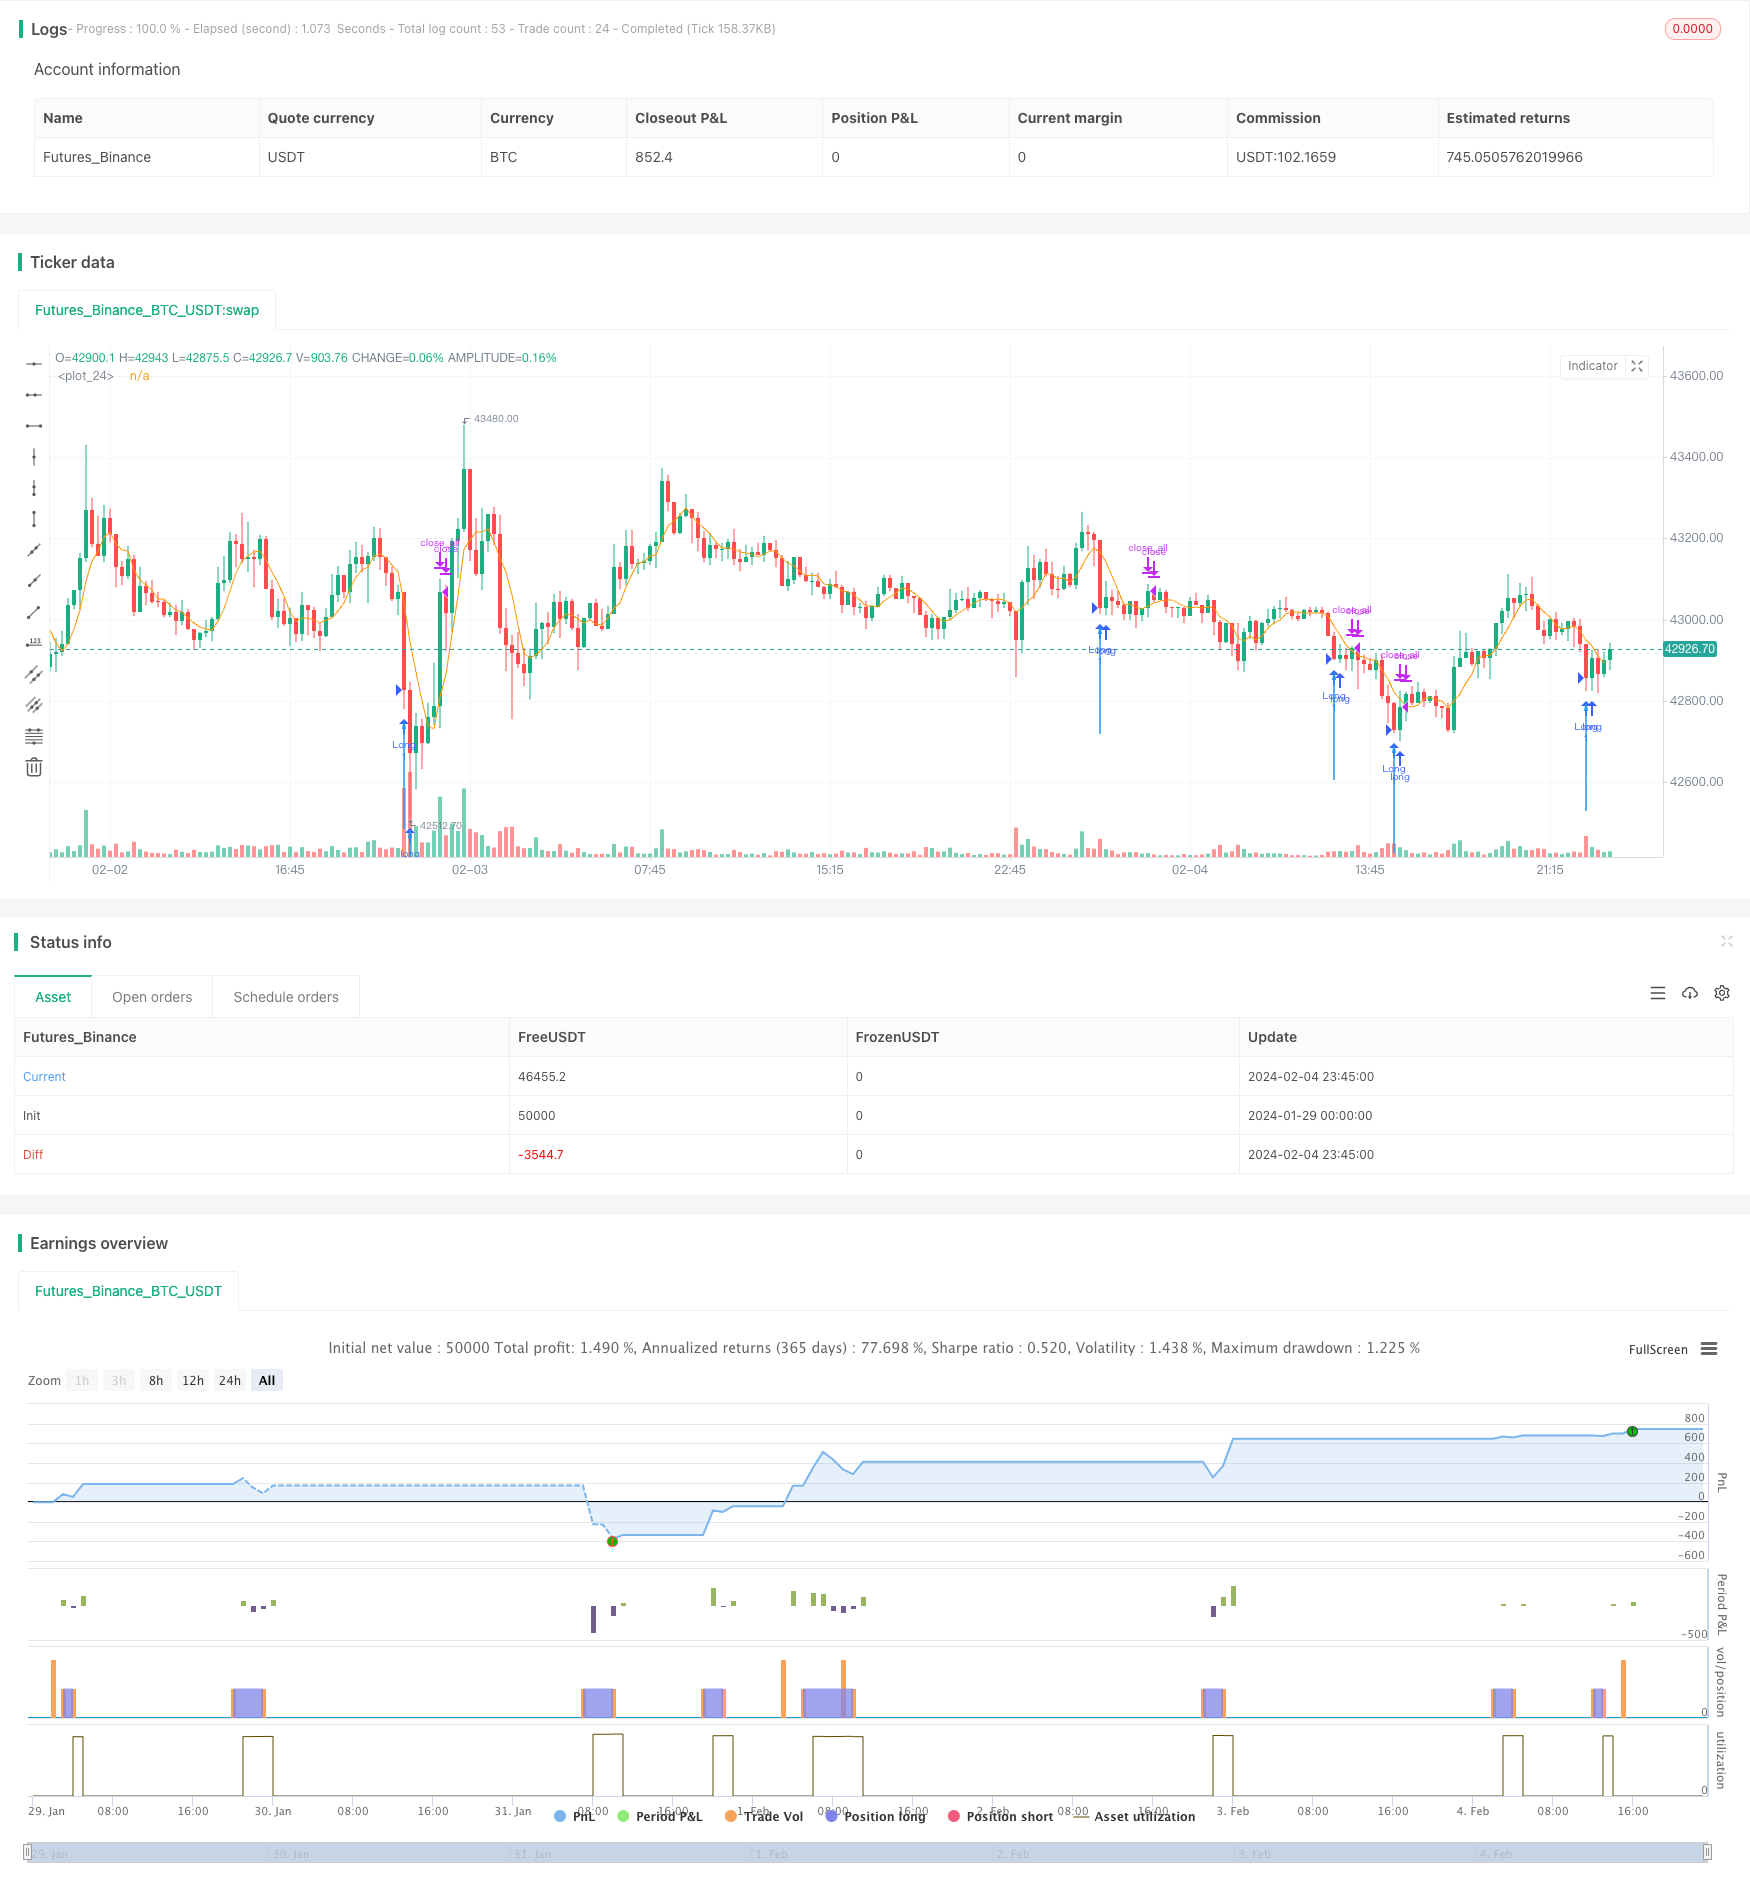
Overview
This strategy identifies market bottom by calculating fast RSI indicator and K-line entity filter to determine oversold status. When fast RSI drops below 10 and K-line entity expands, it considers reversal signal appears for entering long position. This allows detecting market bottom effectively.
Strategy Logic
The strategy is mainly based on two indicators:
Fast RSI Indicator. By calculating the rise and fall percentage of recent 2 days, it quickly judges the overbought and oversold of the market. When fast RSI is below 10, the market is considered oversold.
K-line Entity Filter. By calculating the ratio between K-line entity volume and MA, when the entity volume is greater than 1.5 times MA volume, it is considered as bottom signal.
Firstly, fast RSI below 10 indicates oversold market. Secondly, K-line entity expands to satisfy the condition that entity volume is greater than 1.5 times MA volume. When both conditions are met, it sends out long signal and considers market reaches bottom reversal, which filters out many false signals.
Advantage Analysis
The strategy has the following advantages:
- The fast RSI indicator is sensitive and can quickly determine overbought and oversold.
- The K-line entity filter increases certainty and avoids false breakout.
- Combining fast indicator and K-line pattern can effectively determine market reversal point.
- Low-cost long position realizes bottom fishing operation.
- The strategy logic is simple and clear, easy to understand and implement.
Risk Analysis
There are also some risks in this strategy:
- The market may have consolidation period and keeps falling even oversold.
- Fast RSI may have false signals and entity filter may also be penetrated.
- Backtesting has overfitting risk and live trading performance may differ.
Some solutions for the risks:
- Combine trend indicator to avoid persistent decline.
- Increase other filter conditions to ensure bottom confirmation.
- Optimize multiple parameter combinations to improve stability.
Optimization Directions
Some directions for enhancing the strategy:
- Add stop loss to control downside risk.
- Utilize volatility indicator to avoid abnormal volatility risk.
- Construct multifactor model to ensure effective trading signals.
- Employ machine learning algorithms for parameter optimization.
- Judge trend on larger timeframe to avoid counter trend trading.
Conclusion
This strategy effectively identifies market bottom by fast RSI for oversold and K-line entity filter. The logic is simple for easy implementing and good for catching reversal chance. But certain risks exist and further optimization is needed to improve stability and live performance. Overall speaking, bottom reversal trading strategies designed based on this logic deserve further research.
Source Pine Script
/*backtest
start: 2024-01-29 00:00:00
end: 2024-02-05 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("MarketBottom", shorttitle = "MarketBottom", overlay = true)

//Fast RSI
src = close
fastup = rma(max(change(src), 0), 2)
fastdown = rma(-min(change(src), 0), 2)
fastrsi = fastdown == 0 ? 100 : fastup == 0 ? 0 : 100 - (100 / (1 + fastup / fastdown))

//Body Filter
body = abs(close - open)
abody = sma(body, 10)

mac = sma(close, 10)
len = abs(close - mac)
sma = sma(len, 100)
max = max(open, close)
min = min(open, close)
up = close < open and len > sma * 2 and min < min[1] and fastrsi < 10 and body > abody * 1.5
plotarrow(up == 1 ? 1 : na, colorup = blue, colordown = blue)

sell = sma(close, 5)
exit = high > sell and close > open and body > abody
plot(sell)

if up
    strategy.entry("Long", strategy.long)

if exit
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quantitative-Trading-Strategy-for-Bottom-Reversal.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Advanced Strategy with Volume and Price Pullback Multiple Take ProfitPine Script · Mean reversion · 1h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d