Strategy vault / DCA & fixed investment
Quantized Gradual Weighted DCA Trading Strategy
The Quantized Gradual Weighted DCA Trading Strategy is a quantitative trading strategy that combines moving average indicators for signal triggering and gradual weighted dollar cost averaging mechanisms. The strategy…
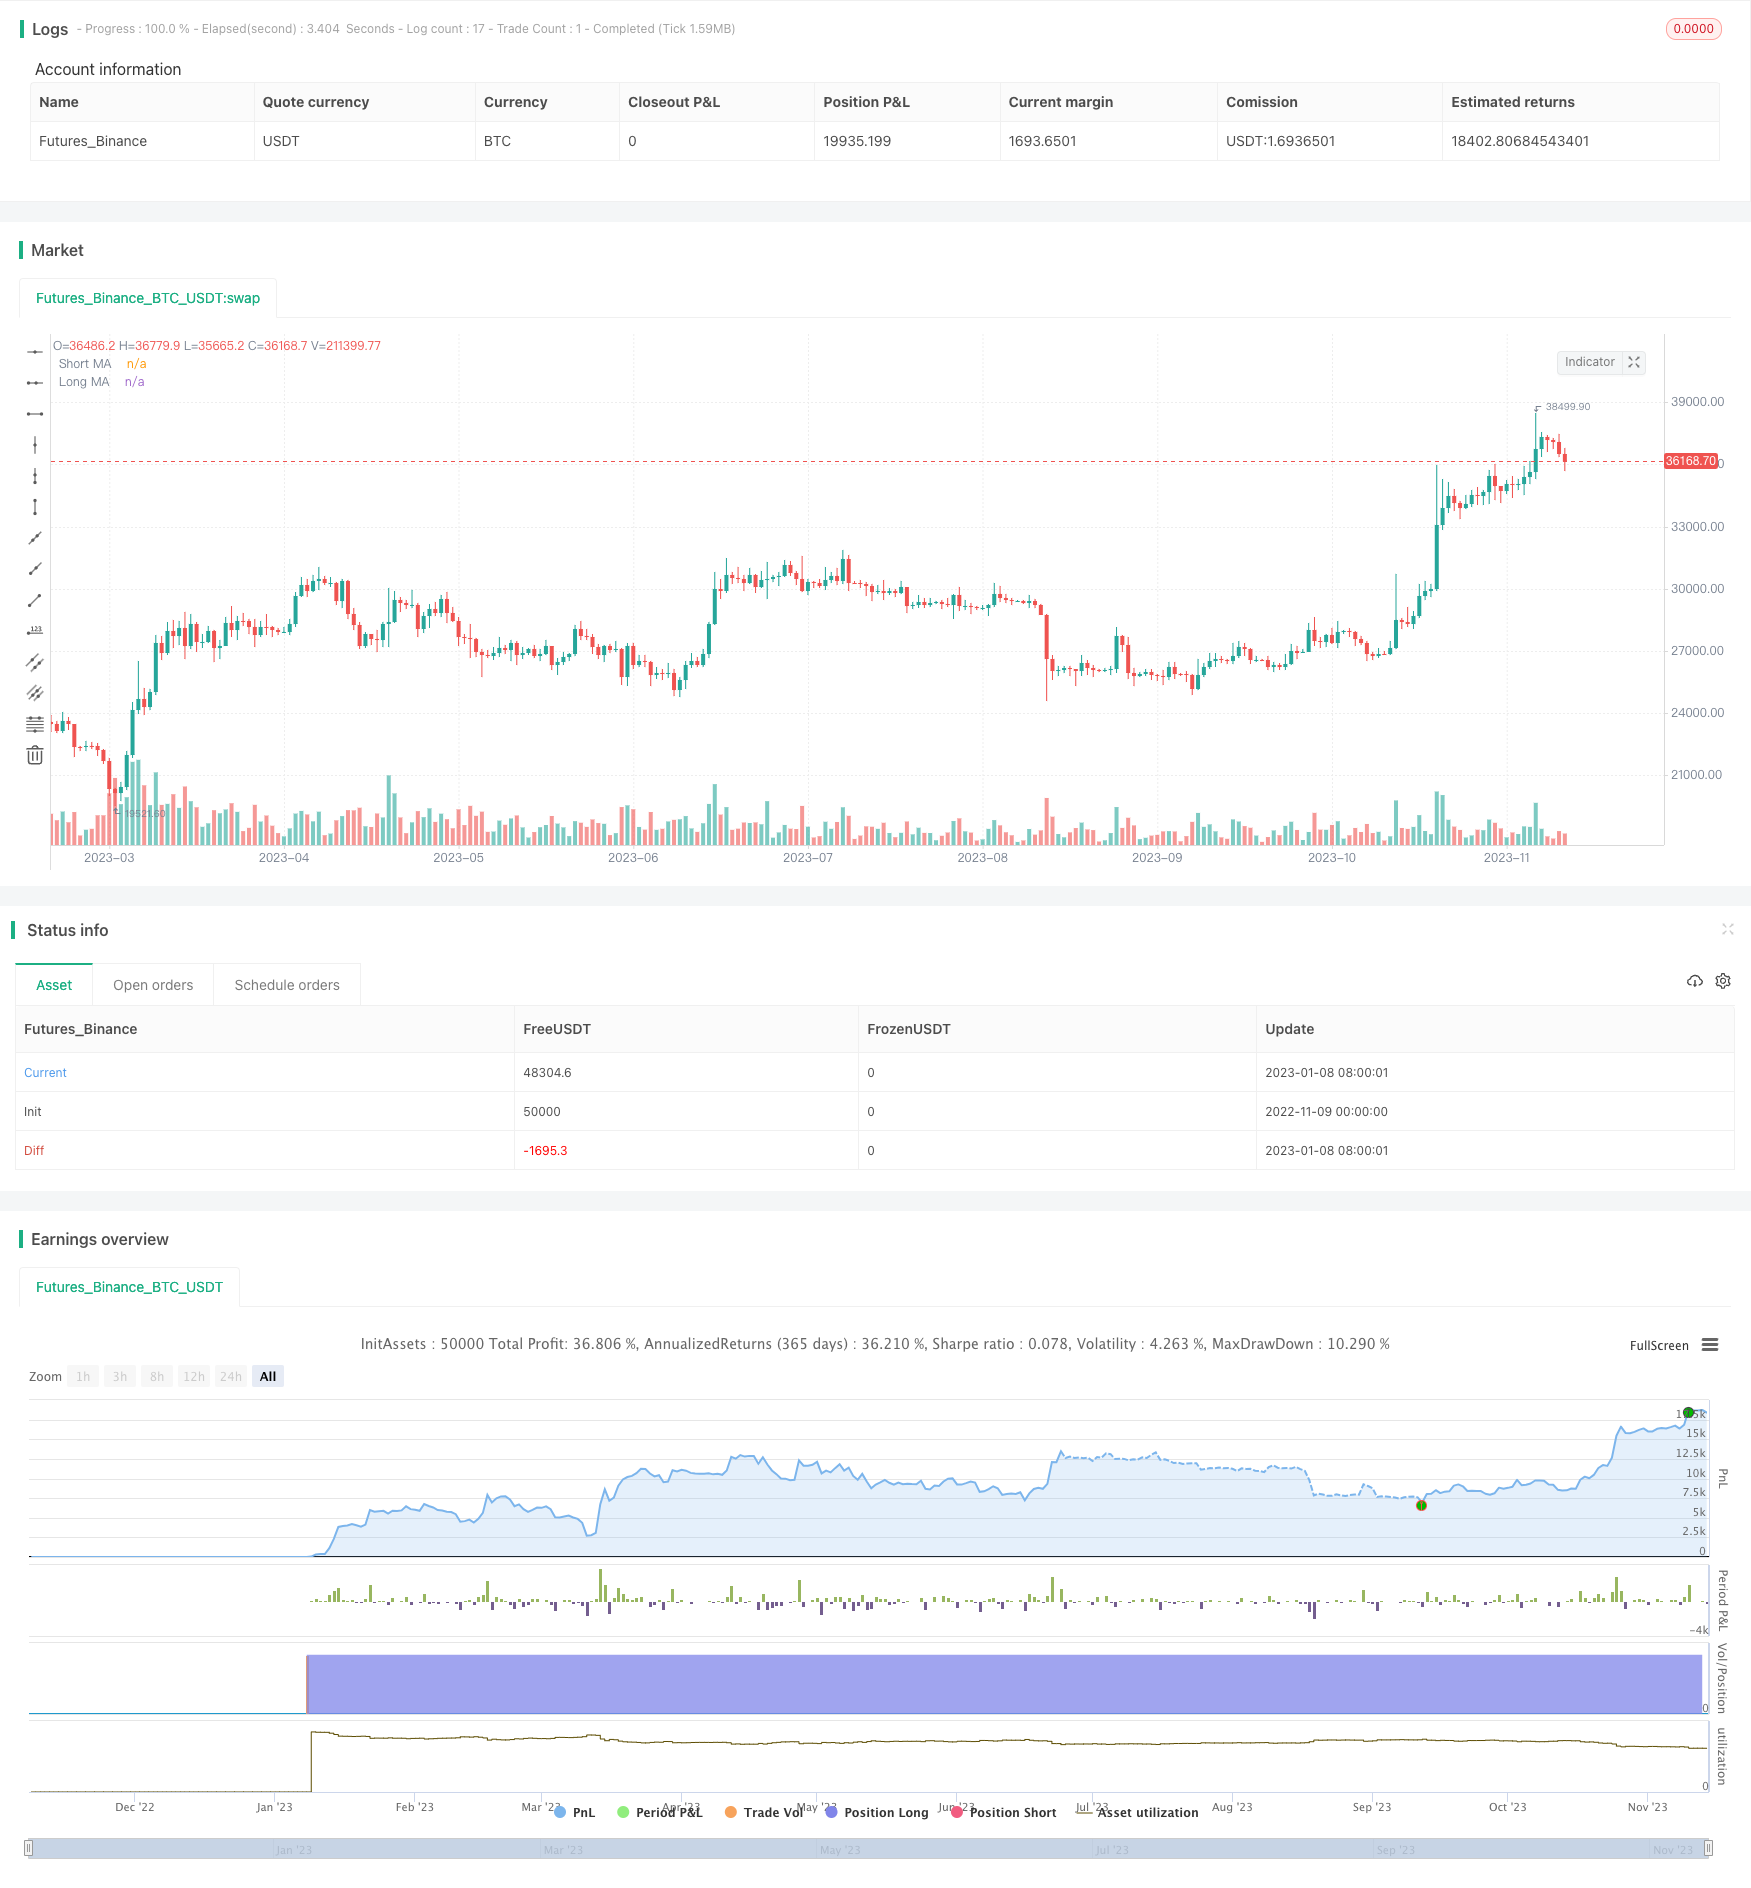
Overview
The Quantized Gradual Weighted DCA Trading Strategy is a quantitative trading strategy that combines moving average indicators for signal triggering and gradual weighted dollar cost averaging mechanisms. The strategy aims to achieve relatively stable returns in strongly trending markets through trend identification and cost averaging.
Principles
The strategy consists of three main components:
Entry signal judgement
It uses fast and slow moving average crossovers as the entry signal. Users can choose between SMA, EMA or HMA for the fast and slow moving averages. When the fast MA crosses above the slow MA, a buy signal is generated. When the fast MA crosses below the slow MA, a sell signal is generated.
Gradual weighted DCA
After a buy signal, the strategy will immediately open a base position. As price continues to fall, the strategy will gradually increase the size of additional safety positions in a weighted manner. The price of each new safety position will be lowered by a fixed percentage relative to the previous one. Also, the allocated funds for each new safety position will be amplified by a factor.
This gradual increase in position size allows a form of cost averaging, obtaining a better average cost while keeping risks in control.
Take profit and Stop loss
When price rises above the take profit line, the strategy will close positions for profit. When price falls below the stop loss line, the strategy will exit positions to control loss.
The take profit line is fixed at base position average price * (1 + fixed percentage).
The stop loss line fluctuates based on the last safety position price, fixed percentage below it.
Advantages
Combining trend and cost averaging makes it more stable
Using trends avoids meaningless whipsaws, and cost averaging provides better entry costs.
Gradual position sizing controls risk
Fixed amplification of safety position sizes, with re-entry threshold, keeps risk in check.
Real-time used funds monitoring
Incorporated balance usage indicator prevents over-leveraging and forced liquidations.
Separate TP/SL for each position
Independent exits allow securing profits and cutting losses.
Risks and Improvements
Price whipsaws can trigger multiple safety orders
In extreme volatility, multiple unnecessary safety orders may be added, increasing loss. Can optimize safety order re-entry threshold.
Moving average parameters need optimization
Different instruments need different moving average periods. Parameter tuning required.
TP/SL levels need backtest optimization
TP/SL ratios determine risk/reward profile. Optimal levels vary.
Add maximum drawdown or holding time based forced exit
Can test incorporating forced exits based on drawdown or holding time to further limit risks.
Summary
The Quantized Gradual Weighted DCA Trading Strategy combines the advantages of trend trading and cost averaging to produce steady returns in strong trends. With optimized parameters, position sizing and re-entry thresholds, it can achieve stable trades with controlled risk. Applicable for hedge funds, CTAs and market neutral strategies.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_string_1 | 0 | (?Strategy)Strategy: Long |
| v_input_string_2 | 0 | Profit currency: Quote (USDT) | Quote (BTC) | Quote (BUSD) |
| v_input_int_1 | 10 | Base order Size |
| v_input_int_2 | 20 | Safety order Size |
| v_input_string_3 | 0 | (?Deal start condition > Trading View custom signal)Entry at Cross Over / Under: Over | Under |
| v_input_string_4 | 0 | Short Moving Average: SMA | EMA | HMA |
| v_input_int_3 | 5 | Period |
| v_input_string_5 | 0 | Long Moving Average: HMA | EMA | SMA |
| v_input_int_4 | 50 | Period |
| v_input_float_1 | 1.5 | (?Take profit / Stop Loss)Target profit (%) |
| v_input_int_5 | 15 | Stop Loss (%) |
| v_input_int_6 | 10 | (?Safety orders)Max safety trades count |
| v_input_float_2 | 0.4 | Price deviation to open safety orders (% from initial order) |
| v_input_float_3 | 1.8 | Safety order volume scale |
| v_input_float_4 | 1.19 | Safety order step scale |
Source Pine Script
/*backtest
start: 2022-11-09 00:00:00
end: 2023-11-15 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © MGTG

//@version=5
Strategy = input.string('Long', options=['Long'], group='Strategy', inline='1',
 tooltip='Long bots profit when asset prices rise, Short bots profit when asset prices fall'
 + '\n\n' + 'Please note: to run a Short bot on a spot exchange account, you need to own the asset you want to trade. The bot will sell the asset at the current chart price and buy it back at a lower price - the profit made is actually trapped equity released from an asset you own that is declining in value.')

Profit_currency = input.string('Quote (USDT)', 'Profit currency', options=['Quote (USDT)', 'Quote (BTC)', 'Quote (BUSD)'], group='Strategy', inline='1')
Base_order_size = input.int(10, 'Base order Size', group='Strategy', inline='2',
 tooltip='The Base Order is the first order the bot will create when starting a new deal.')
Safety_order_size = input.int(20, 'Safety order Size', group='Strategy', inline='2',
 tooltip="Enter the amount of funds your Safety Orders will use to Average the cost of the asset being traded, this can help your bot to close deals faster with more profit. Safety Orders are also known as Dollar Cost Averaging and help when prices moves in the opposite direction to your bot's take profit target.")

Triger_Type = input.string('Over', 'Entry at Cross Over / Under', options=['Over', 'Under'], group='Deal start condition > Trading View custom signal', inline='1',
 tooltip='Deal start condition decision')

Short_Moving_Average  = input.string('SMA', 'Short Moving Average', group='Deal start condition > Trading View custom signal', inline='2',
 options=["SMA", "EMA", "HMA"])
Short_Period         = input.int(5, 'Period', group='Deal start condition > Trading View custom signal', inline='2')
Long_Moving_Average  = input.string('HMA', 'Long Moving Average', group='Deal start condition > Trading View custom signal', inline='3',
 options=["SMA", "EMA", "HMA"])

Long_Period          = input.int(50, 'Period', group='Deal start condition > Trading View custom signal', inline='3')

Target_profit = input.float(1.5, 'Target profit (%)', step=0.05, group='Take profit / Stop Loss', inline='1') * 0.01
Stop_Loss = input.int(15, 'Stop Loss (%)', group='Take profit / Stop Loss', inline='1',
 tooltip='This is the percentage that price needs to move in the opposite direction to your take profit target, at which point the bot will execute a Market Order on the exchange account to close the deal for a smaller loss than keeping the deal open.'
 + '\n' + 'Please note, the Stop Loss is calculated from the price the Safety Order at on the exchange account and not the Dollar Cost Average price.') * 0.01

Max_safety_trades_count = input.int(10, 'Max safety trades count', maxval=10, group='Safety orders', inline='1')
Price_deviation = input.float(0.4, 'Price deviation to open safety orders (% from initial order)', step=0.01, group='Safety orders', inline='2') * 0.01
Safety_order_volume_scale = input.float(1.8, 'Safety order volume scale', step=0.01, group='Safety orders', inline='3')
Safety_order_step_scale = input.float(1.19, 'Safety order step scale', step=0.01, group='Safety orders', inline='3')

// daily_volume  = input.int(500, "Don't start deal(s) if the daily volume is less than", group='Advanced settings', inline='1')
// Minimum_price  = input.int(500, "Minimum price to open deal", group='Advanced settings', inline='1')
// Maximum_price  = input.int(500, "Maximum price to open deal", group='Advanced settings', inline='1')

// Close_deal_after_timeout  = input.int(5, "Close deal after timeout (Hrs)", group='Advanced settings', inline='1')

initial_capital = 8913

strategy(
 title='3Commas Visible DCA Strategy',
 overlay=true,
 initial_capital=initial_capital,
 pyramiding=11,
 process_orders_on_close=true,
 commission_type=strategy.commission.percent,
 commission_value=0.01,
 max_bars_back=5000,
 max_labels_count=50)


// Position
status_none  = strategy.position_size == 0
status_long  = strategy.position_size[1] == 0 and strategy.position_size > 0
status_long_offset  = strategy.position_size[2] == 0 and strategy.position_size[1] > 0
status_short = strategy.position_size[1] == 0 and strategy.position_size < 0
status_increase = strategy.opentrades[1] < strategy.opentrades

Short_Moving_Average_Line =
 Short_Moving_Average == 'SMA' ? ta.sma(close, Short_Period) :
 Short_Moving_Average == 'EMA' ? ta.ema(close, Short_Period) :
 Short_Moving_Average == 'HMA' ? ta.sma(close, Short_Period) : na

Long_Moving_Average_Line =
 Long_Moving_Average == 'SMA' ? ta.sma(close, Long_Period) :
 Long_Moving_Average == 'EMA' ? ta.ema(close, Long_Period) :
 Long_Moving_Average == 'HMA' ? ta.sma(close, Long_Period) : na

Base_order_Condition      = Triger_Type == "Over" ? ta.crossover(Short_Moving_Average_Line, Long_Moving_Average_Line) : ta.crossunder(Short_Moving_Average_Line, Long_Moving_Average_Line) // Buy when close crossing lower band

safety_order_deviation(index) => Price_deviation * math.pow(Safety_order_step_scale,  index - 1)

pd = Price_deviation
ss = Safety_order_step_scale

step(i) =>
 i == 1 ? pd :
 i == 2 ? pd + pd * ss :
 i == 3 ? pd + (pd + pd * ss) * ss :
 i == 4 ? pd + (pd + (pd + pd * ss) * ss) * ss :
 i == 5 ? pd + (pd + (pd + (pd + pd * ss) * ss) * ss) * ss :
 i == 6 ? pd + (pd + (pd + (pd + (pd + pd * ss) * ss) * ss) * ss) * ss :
 i == 7 ? pd + (pd + (pd + (pd + (pd + (pd + pd * ss) * ss) * ss) * ss) * ss) * ss :
 i == 8 ? pd + (pd + (pd + (pd + (pd + (pd + (pd + pd * ss) * ss) * ss) * ss) * ss) * ss) * ss :
 i == 9 ? pd + (pd + (pd + (pd + (pd + (pd + (pd + (pd + pd * ss) * ss) * ss) * ss) * ss) * ss) * ss) * ss :
 i == 10 ? pd + (pd + (pd + (pd + (pd + (pd + (pd + (pd + (pd + pd * ss) * ss) * ss) * ss) * ss) * ss) * ss) * ss) * ss : na

long_line(i) =>
 close[1] - close[1] * (step(i))


Safe_order_line(i) =>
 i == 0 ? ta.valuewhen(status_long, long_line(0), 0) :
 i == 1 ? ta.valuewhen(status_long, long_line(1), 0) :
 i == 2 ? ta.valuewhen(status_long, long_line(2), 0) :
 i == 3 ? ta.valuewhen(status_long, long_line(3), 0) :
 i == 4 ? ta.valuewhen(status_long, long_line(4), 0) :
 i == 5 ? ta.valuewhen(status_long, long_line(5), 0) :
 i == 6 ? ta.valuewhen(status_long, long_line(6), 0) :
 i == 7 ? ta.valuewhen(status_long, long_line(7), 0) :
 i == 8 ? ta.valuewhen(status_long, long_line(8), 0) :
 i == 9 ? ta.valuewhen(status_long, long_line(9), 0) :
 i == 10 ? ta.valuewhen(status_long, long_line(10), 0) : na

TP_line = strategy.position_avg_price * (1 + Target_profit)

SL_line = Safe_order_line(Max_safety_trades_count) * (1 - Stop_Loss)

safety_order_size(i) => Safety_order_size * math.pow(Safety_order_volume_scale, i - 1)


plot(Short_Moving_Average_Line, 'Short MA', color=color.new(color.white, 0), style=plot.style_line)
plot(Long_Moving_Average_Line, 'Long MA', color=color.new(color.green, 0), style=plot.style_line)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 1 ? Safe_order_line(1) : na, 'Safety order1', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 2 ? Safe_order_line(2) : na, 'Safety order2', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 3 ? Safe_order_line(3) : na, 'Safety order3', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 4 ? Safe_order_line(4) : na, 'Safety order4', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 5 ? Safe_order_line(5) : na, 'Safety order5', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 6 ? Safe_order_line(6) : na, 'Safety order6', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 7 ? Safe_order_line(7) : na, 'Safety order7', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 8 ? Safe_order_line(8) : na, 'Safety order8', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 9 ? Safe_order_line(9) : na, 'Safety order9', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 and Max_safety_trades_count >= 10 ? Safe_order_line(10) : na, 'Safety order10', color=color.new(#009688, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 ? TP_line : na, 'Take Profit', color=color.new(color.orange, 0), style=plot.style_linebr)
plot(strategy.position_size > 0 ? SL_line : na, 'Safety', color=color.new(color.aqua, 0), style=plot.style_linebr)


currency =
 Profit_currency == 'Quote (USDT)' ? ' USDT' :
 Profit_currency == 'Quote (BTC)'  ? ' BTC' :
 Profit_currency == 'Quote (BUSD)' ? ' BUSD' : na


if Base_order_Condition
    strategy.entry('Base order', strategy.long, qty=Base_order_size/close, when=Base_order_Condition and strategy.opentrades == 0,
     comment='BO' + ' - ' + str.tostring(Base_order_size) + str.tostring(currency))

for i = 1 to Max_safety_trades_count by 1
    i_s = str.tostring(i)
    strategy.entry('Safety order' + i_s, strategy.long, qty=safety_order_size(i)/close,
     limit=Safe_order_line(i), when=(strategy.opentrades <= i) and strategy.position_size > 0,
     comment='SO' + i_s + ' - ' + str.tostring(safety_order_size(i))  + str.tostring(currency))


for i = 1 to Max_safety_trades_count by 1
    i_s = str.tostring(i)
    // strategy.close('Base order', when=shortCondition)
    // strategy.close('Safety order' + i_s, when=shortCondition)
    // strategy.cancel('Safety order' + i_s, when=shortCondition)
    strategy.cancel('SO' + i_s, when=ta.crossunder(low, SL_line) or ta.crossover(high, TP_line) or status_none)
    strategy.exit('TP/SL','Base order', limit=TP_line, stop=SL_line, comment = Safe_order_line(100) > close ? 'SL' + i_s + ' - ' +  str.tostring(Base_order_size) + str.tostring(currency) : 'TP' + i_s + ' - ' +  str.tostring(Base_order_size) + str.tostring(currency))
    strategy.exit('TP/SL','Safety order' + i_s, limit=TP_line, stop=SL_line, comment = Safe_order_line(100) > close ? 'SL' + i_s + ' - ' +  str.tostring(safety_order_size(i)) + str.tostring(currency) : 'TP' + i_s + ' - ' +  str.tostring(safety_order_size(i)) + str.tostring(currency))
    // strategy.cancel('TP/SP' + i_s, when=Base_order_Condition)
    // strategy.exit('Stop Loss','Base order', stop=SL_line)
    // strategy.exit('Stop Loss','Safety order' + i_s, stop=SL_line)

//----------------label A----------------//

bot_usage(i) =>
 i == 1 ? Base_order_size + safety_order_size(1) :
 i == 2 ? Base_order_size + safety_order_size(1) + safety_order_size(2) :
 i == 3 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) :
 i == 4 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) + safety_order_size(4) :
 i == 5 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) + safety_order_size(4) + safety_order_size(5) :
 i == 6 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) + safety_order_size(4) + safety_order_size(5) + safety_order_size(6) :
 i == 7 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) + safety_order_size(4) + safety_order_size(5) + safety_order_size(6) + safety_order_size(7) :
 i == 8 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) + safety_order_size(4) + safety_order_size(5) + safety_order_size(6) + safety_order_size(7) + safety_order_size(8) :
 i == 9 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) + safety_order_size(4) + safety_order_size(5) + safety_order_size(6) + safety_order_size(7) + safety_order_size(8) + safety_order_size(9) :
 i == 10 ? Base_order_size + safety_order_size(1) + safety_order_size(2) + safety_order_size(3) + safety_order_size(4) + safety_order_size(5) + safety_order_size(6) + safety_order_size(7) + safety_order_size(8) + safety_order_size(9) + safety_order_size(10) : na

equity = strategy.equity
bot_use = bot_usage(Max_safety_trades_count)
bot_dev = float(step(Max_safety_trades_count)) * 100
bot_ava = (bot_use / equity) * 100

string label_A =
 'Balance                                      : ' + str.tostring(math.round(equity, 0), '###,###,###,###') + ' USDT' + '\n' +
 'Max amount for bot usage           : ' + str.tostring(math.round(bot_use, 0), '###,###,###,###') + ' USDT' + '\n' +
 'Max safety order price deviation : ' + str.tostring(math.round(bot_dev, 0), '##.##') + ' %' + '\n' +
 '% of available balance                : ' + str.tostring(math.round(bot_ava, 0), '###,###,###,###') + ' %'
 + (bot_ava > 100 ? '\n \n' +  '⚠ Warning! Bot will use amount greater than you have on exchange' : na)


if status_long
    day_label =
     label.new(
     x=time[1],
     y=high * 1.03,
     text=label_A,
     xloc=xloc.bar_time,
     yloc=yloc.price,
     color=bot_ava > 100 ? color.new(color.yellow, 0) : color.new(color.black, 50),
     style=label.style_label_lower_right,
     textcolor=bot_ava > 100 ? color.new(color.red, 0) : color.new(color.silver, 0),
     size=size.normal,
textalign=text.align_left)Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quantized-Gradual-Weighted-DCA-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Daily DCA Strategy with Touching EMAsPine Script · DCA & fixed investment · 3m
- Mean Reversion Bollinger Band Dollar Cost Averaging Investment StrategyPine Script · DCA & fixed investment · 1d
- Intelligent Wave Trend Dollar Cost Averaging Cyclical Trading StrategyPine Script · DCA & fixed investment · 1h
- Multi Indicator Confirmation EMA Breakout with DCA and Dynamic Take Profit StrategyPine Script · DCA & fixed investment · 1d
- Bollinger Band and RSI Mixing with DCA StrategyPine Script · DCA & fixed investment · 1d
- DCA Dual Moving Average Turtle Trading StrategyPine Script · DCA & fixed investment · 10m