Reversal Breakout Bandpass Combo Strategy
This is a combo strategy driven by two factors - reversal and bandpass, which achieves multi-factor overlay and adapts to different market conditions.
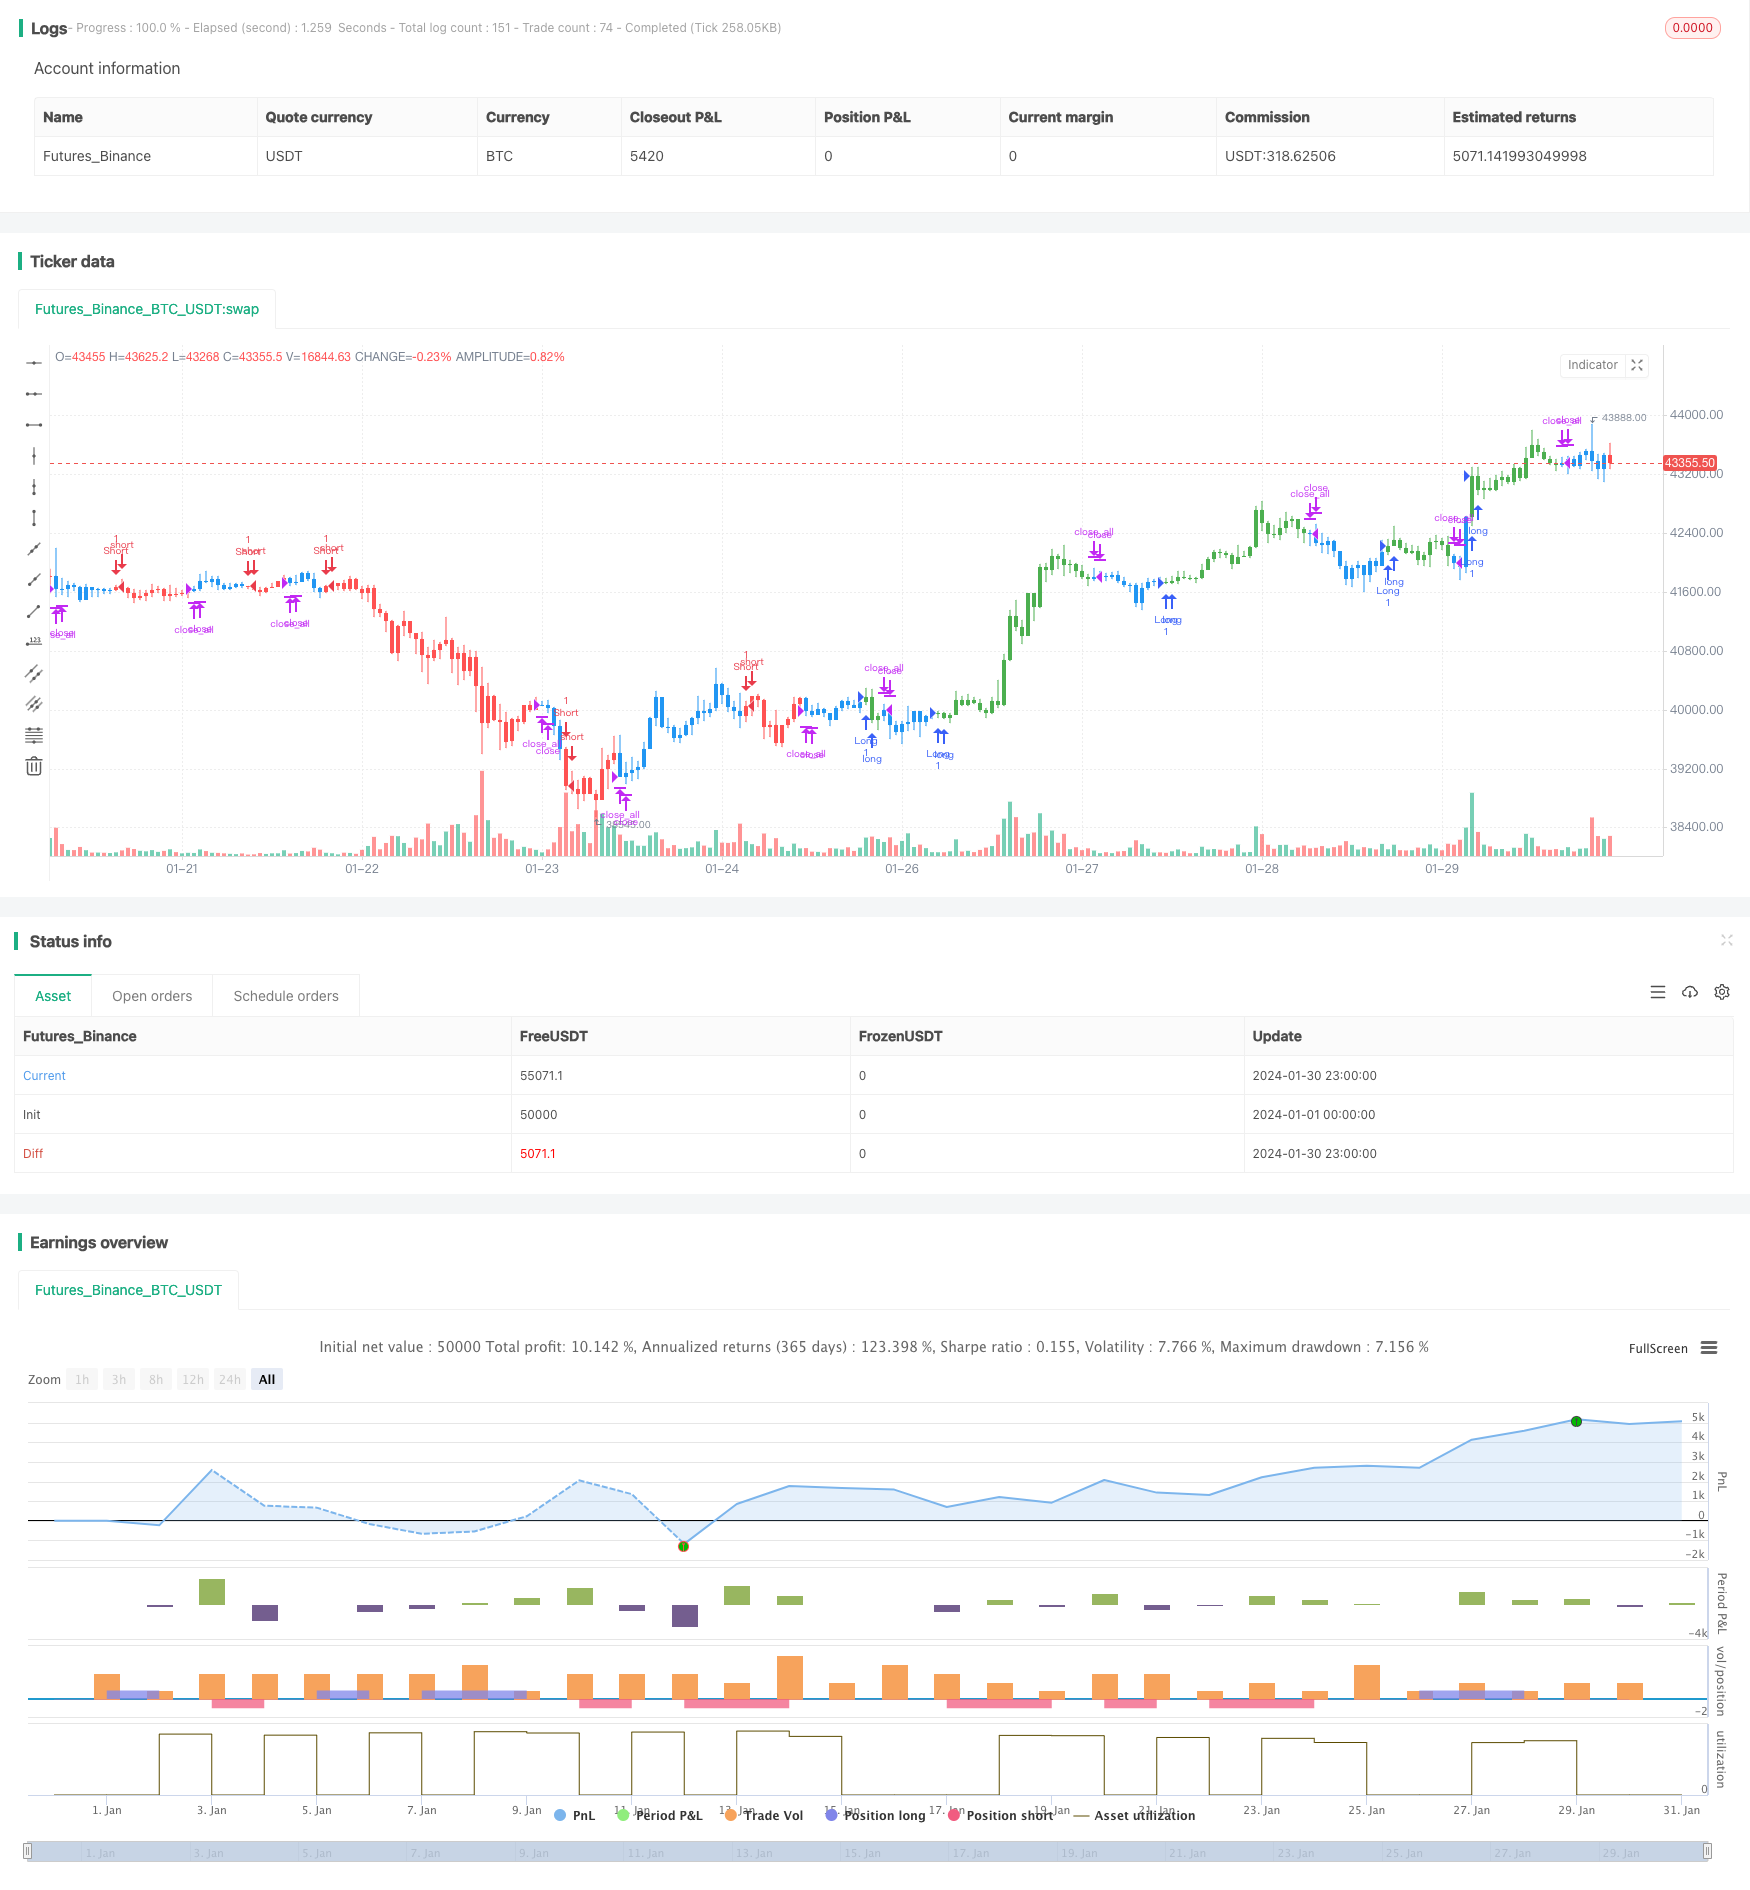
Overview
This is a combo strategy driven by two factors - reversal and bandpass, which achieves multi-factor overlay and adapts to different market conditions.
Strategy Logic
The strategy consists of two sub-strategies:
123 Reversal Strategy: When the close price drops for two consecutive days, if today's close breaks through the lowest price in the previous two days, and the fast line of 9-day Stochastic oscillator crosses above the slow line, go long. When the close price rises for two consecutive days, if today's close drops below the highest price in the previous two days, and the fast line crosses below the slow line, go short.
Bandpass Filter: Calculate a bandpass indicator over a certain period, go long when it is above a threshold, and go short when below.
The combined signal is: take long position if both strategies give long signals, take short position if both give short signals, otherwise clear all positions.
Advantages
- Driven by dual factors, adapts to various market conditions, profitable across regimes
- 123 reversal captures reversal opportunities in range-bound markets
- Bandpass filter tracks trends in trending markets
- Combined signal verifies and avoids erroneous trades
Risks
- Improper parameters may cause over-trading
- Multiple losses may occur in choppy markets
- Transaction costs need to be monitored
Enhancement
- Tune bandpass filter parameters to optimize bandpass calculation
- Adjust 123 reversal parameters to optimize long/short reversal identification
- Add stop loss to control losses for single trades
Summary
This strategy integrates reversal and trend factors to achieve multi-factor driven quantitative trading. The dual-factor verification reduces the probability of erroneous trades, making the strategy perform well across various markets. Further improvements on parameter tuning and stop loss will enhance the strategy's stability and profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | Length |
| v_input_2 | true | KSmoothing |
| v_input_3 | 3 | DLength |
| v_input_4 | 50 | Level |
| v_input_5 | 20 | LengthBF |
| v_input_6 | 0.5 | Delta |
| v_input_7 | false | TriggerLevel |
| v_input_8 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 21/05/2019
// This is combo strategies for get
// a cumulative signal. Result signal will return 1 if two strategies
// is long, -1 if all strategies is short and 0 if signals of strategies is not equal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
// The related article is copyrighted material from
// Stocks & Commodities Mar 2010
// You can use in the xPrice any series: Open, High, Low, Close, HL2, HLC3, OHLC4 and ect...
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


Bandpass_Filter(Length, Delta, TriggerLevel) =>
    xPrice = hl2
    beta = cos(3.14 * (360 / Length) / 180)
    gamma = 1 / cos(3.14 * (720 * Delta / Length) / 180)
    alpha = gamma - sqrt(gamma * gamma - 1)
    BP = 0.0
    pos = 0.0
    BP := 0.5 * (1 - alpha) * (xPrice - xPrice[2]) + beta * (1 + alpha) * nz(BP[1]) - alpha * nz(BP[2])
    pos := iff(BP > TriggerLevel, 1,
	       iff(BP <= TriggerLevel, -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Bandpass Filter", shorttitle="Combo", overlay = true)
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
LengthBF = input(20, minval=1)
Delta = input(0.5)
TriggerLevel = input(0)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posBandpass_Filter = Bandpass_Filter(LengthBF, Delta, TriggerLevel)
pos = iff(posReversal123 == 1 and posBandpass_Filter == 1 , 1,
	   iff(posReversal123 == -1 and posBandpass_Filter == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? red: possig == 1 ? green : blue ) Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Reversal-Breakout-Bandpass-Combo-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h
- Moving Stop Loss Tracking StrategyPine Script · Breakout · 1d
- Quantitative Strategy PSARZigZagMACDART Based on Multi Indicator CombinationPine Script · Breakout · 1m
- Quantitative Trading Price Breakthrough StrategyPine Script · Breakout · 1d
- Stochastic RSI and Volume Based Trading StrategyPine Script · Breakout · 2h