Strategy vault / Mean reversion
Reversal Dual Moving Average Crossover Strategy
Overview: This strategy is based on the classic trading strategy of moving average crossover. It uses dual moving averages, including Simple Moving Average (SMA), Exponential Moving Average (EMA), Variable Weighted…
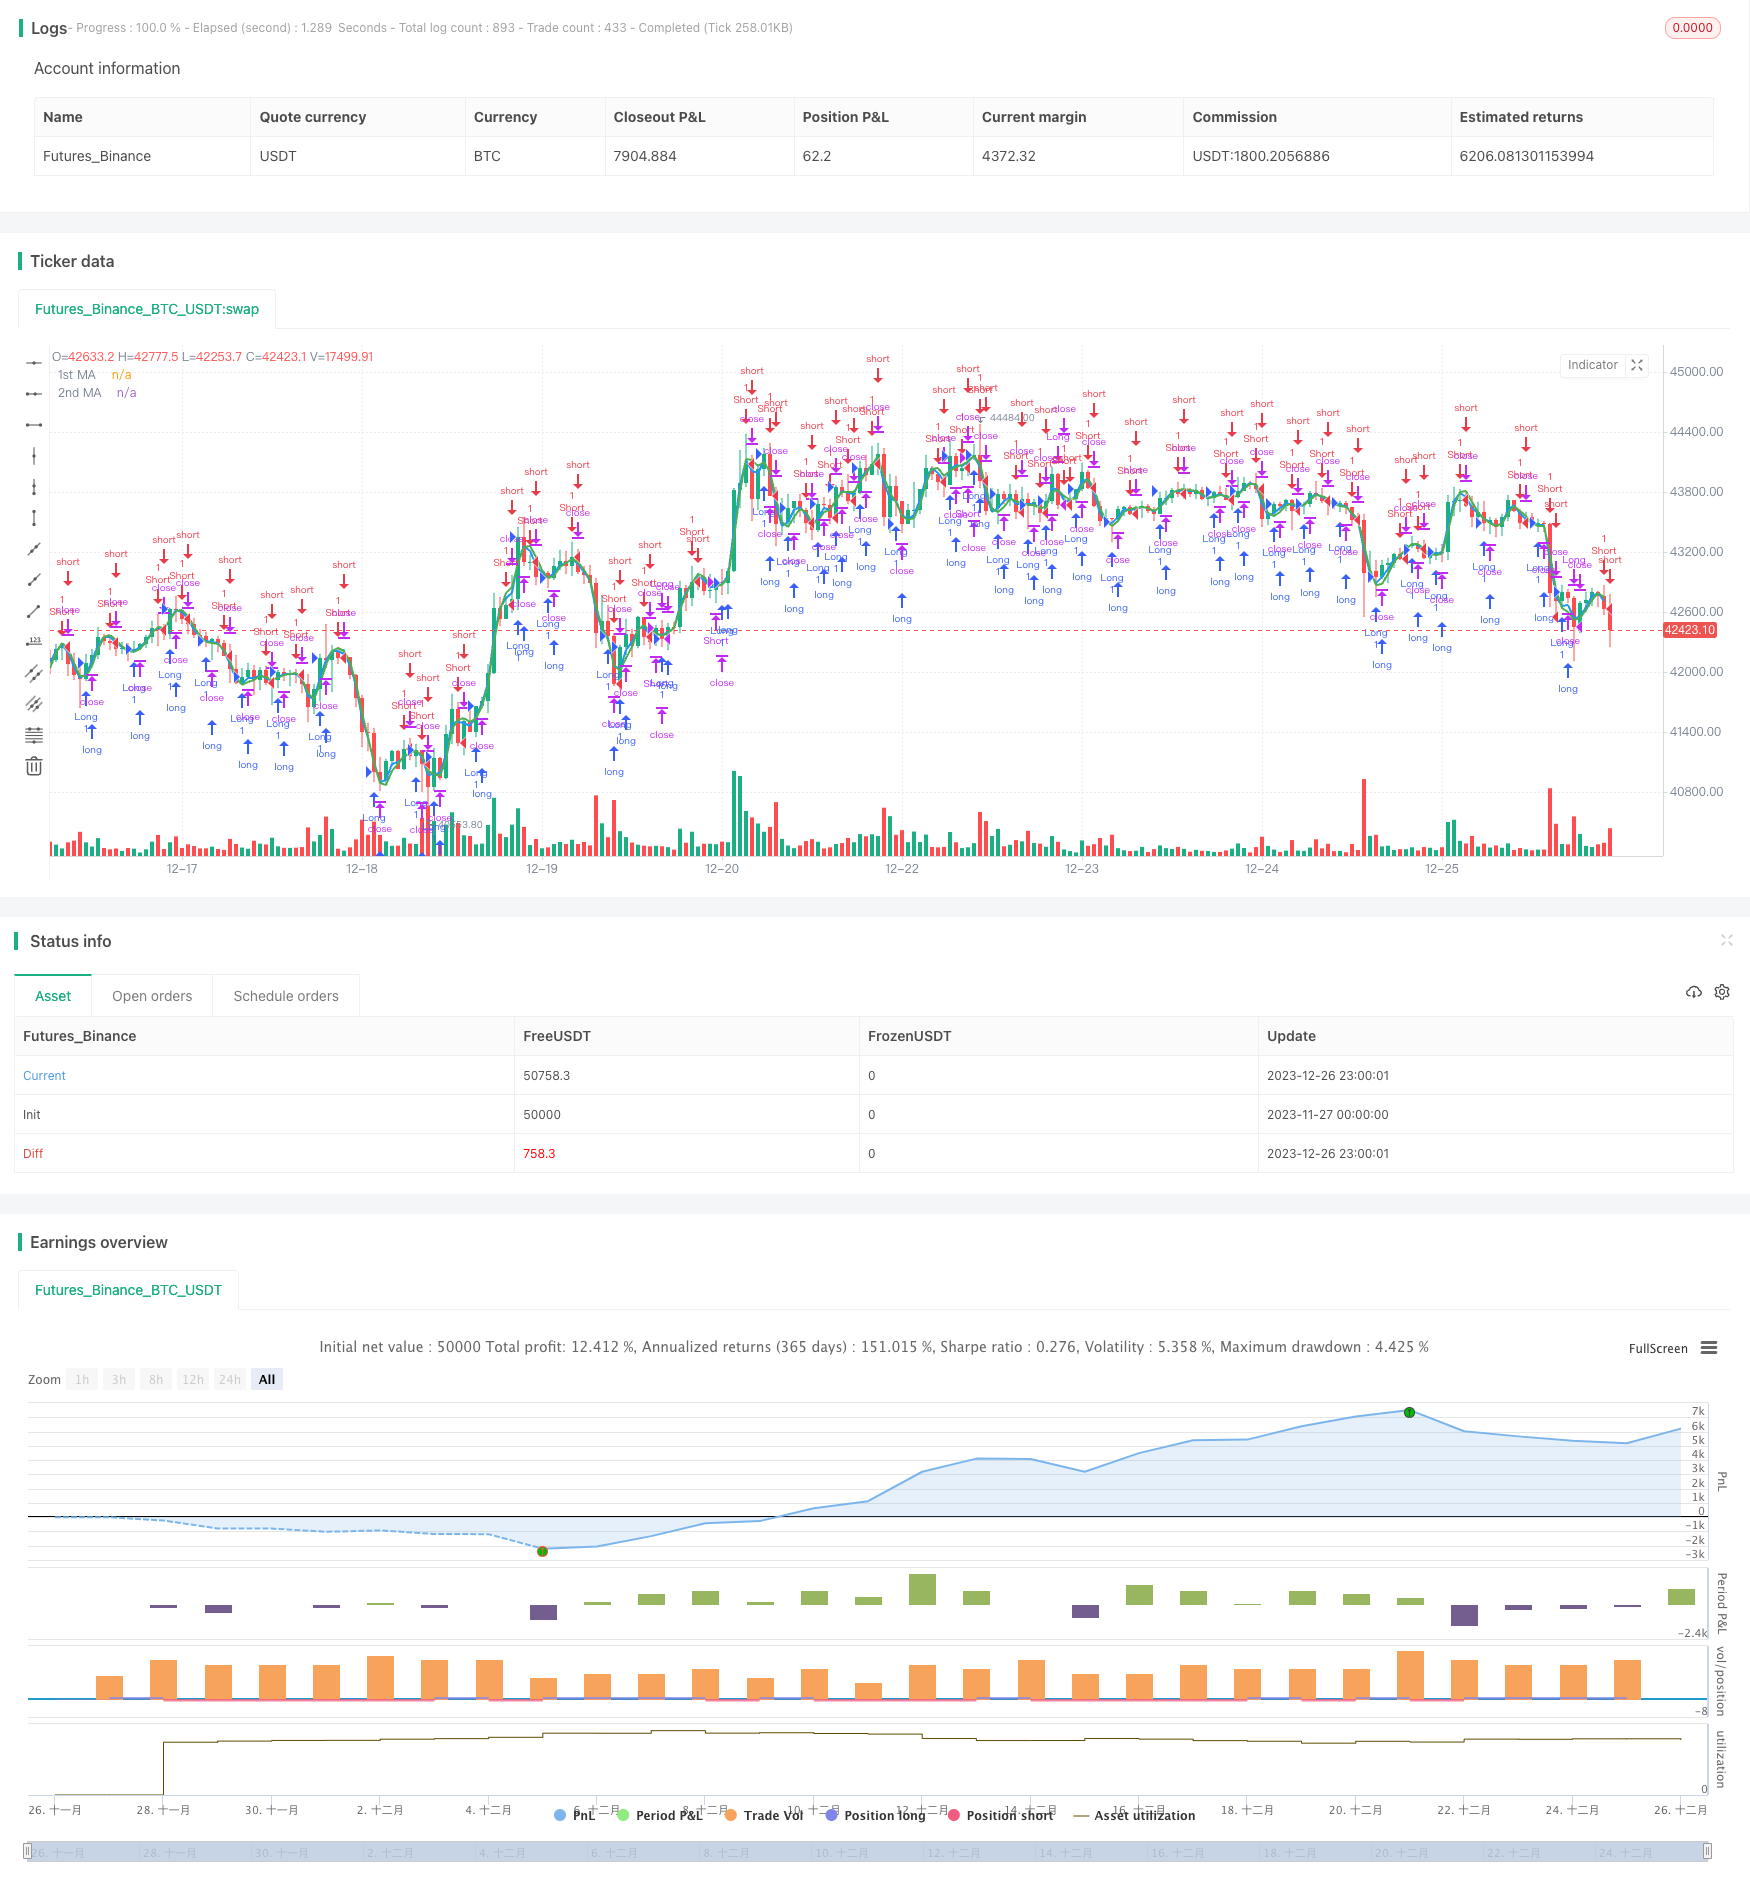
Overview: This strategy is based on the classic trading strategy of moving average crossover. It uses dual moving averages, including Simple Moving Average (SMA), Exponential Moving Average (EMA), Variable Weighted Moving Average (VWMA) and Hull Moving Average (HMA).
Principle: The core logic of the strategy is the dual moving average crossover. By calculating two moving averages with different parameters, a buy signal is generated when the fast moving average crosses over the slow one, and a sell signal is generated when the fast moving average crosses below the slow one. The moving average crossover represents the turning point of the short-term and long-term trends of prices.
Advantage Analysis: The main advantages of the dual moving average crossover strategy are simplicity and ease of operation. With only one signal, the most basic trend judgment can be obtained without too many parameter selections and adjustments, which is very suitable for novice traders. In addition, different types of moving averages are tested to optimize different combinations.
Risk Analysis: The main risk of this strategy is that common moving average crossover strategies will have a lot of false signals, resulting in multiple small profits and flat positions, which affects the overall return. In addition, the fixed fast and slow moving average length settings may fail in certain cycles.
Optimization Directions: 1) Test different periods to determine the optimal combination of moving average crosses; 2) Consider introducing a second set of moving average parameters and RSI indicators to assist in judgment to reduce false signals; 3) Introduce condition judgment based on the incremental change of the MA indicator instead of simple crossover to obtain a more reliable crossover judgment.
Summary: This strategy adopts the framework of the traditional moving average crossover strategy to test dual moving averages to find the optimal combination of moving average periods. At the same time, it adds stop-loss judgments based on the ROC and price of the moving average. Overall it is a simple and easy-to-use dual moving average strategy that conforms to quantitative trading logic. In addition, the rich optimization ideas also provide room for the further development of this strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 5 | 1st MA Length |
| v_input_3 | 0 | 1st MA Type: HMA | EMA | SMA | VWMA |
| v_input_4 | 7 | 2nd MA Length |
| v_input_5 | 0 | 2nd MA Type: HMA | EMA | SMA | VWMA |
| v_input_6 | true | Lookback 1 |
| v_input_7 | 2 | Minimum slope magnitude * 100 |
Source Pine Script
/*backtest
start: 2023-11-27 00:00:00
end: 2023-12-27 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//study(title="MA Crossover Strategy", overlay = true)
strategy("MA Crossover Strategy with MA Turning Point Exits", overlay=true)
src = input(close, title="Source")

price = request.security(syminfo.tickerid, timeframe.period, src)
ma1 = input(5, title="1st MA Length")
type1 = input("HMA", "1st MA Type", options=["SMA", "EMA", "HMA", "VWMA"])

ma2 = input(7, title="2nd MA Length")
type2 = input("HMA", "2nd MA Type", options=["SMA", "EMA", "HMA", "VWMA"])

f_hma(_src, _length)=>
    _return = wma((2*wma(_src, _length/2))-wma(_src, _length), round(sqrt(_length)))
price1 = if (type1 == "SMA")
    sma(price, ma1)
else
    if (type1 == "EMA")
        ema(price, ma1)
    else
        if (type1 == "VWMA")
            vwma(price, ma1)
        else
            f_hma(price, ma1)

price2 = if (type2 == "SMA")
    sma(price, ma2)
else
    if (type2 == "EMA")
        ema(price, ma2)
    else
        if (type2 == "VWMA")
            vwma(price, ma2)
        else
            f_hma(price, ma2)

//plot(series=price, style=line,  title="Price", color=black, linewidth=1, transp=0)
plot(series=price1, style=line,  title="1st MA", color=blue, linewidth=2, transp=0)
plot(series=price2, style=line, title="2nd MA", color=green, linewidth=2, transp=0)


longCondition = crossover(price1, price2)
if (longCondition) // and time>timestamp(2018,6,1,9,30)
    strategy.entry("Long", strategy.long)

shortCondition = crossunder(price1, price2)
if (shortCondition) // and time>timestamp(2018,6,1,9,30)
    strategy.entry("Short", strategy.short)

lookback1 = input(1, "Lookback 1")
roc1 = roc(price1, lookback1)

ma1up = false
ma1down = false
ma2up = false
ma2down = false

ma1up := nz(ma1up[1])
ma1down := nz(ma1down[1])
ma2up := nz(ma2up[1])
ma2down := nz(ma2down[1])

trendStrength1 = input(2, title="Minimum slope magnitude * 100", type=float) * 0.01

if crossover(roc1, trendStrength1)
    ma1up := true
    ma1down := false

if crossunder(roc1, -trendStrength1)
    ma1up := false
    ma1down := true

shortexitCondition = ma1up and ma1down[1]
if (shortexitCondition)
    strategy.close("Short")

longexitCondition = ma1down and ma1up[1]
if (longexitCondition)
    strategy.close("Long")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Reversal-Dual-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dual Moving Average Crossover with RSI Overbought Oversold Pyramid Dynamic Trend Trading StrategyPine Script · Mean reversion · 2h