Strategy vault / Mean reversion
Reversal High Frequency Trading Strategy Based on Shadow Line
This is a high-frequency trading strategy based on the 3-minute K-line of the Coinbase exchange. It calculates the upper and lower shadow lines of the K-line to determine if there is a reversal opportunity in the…
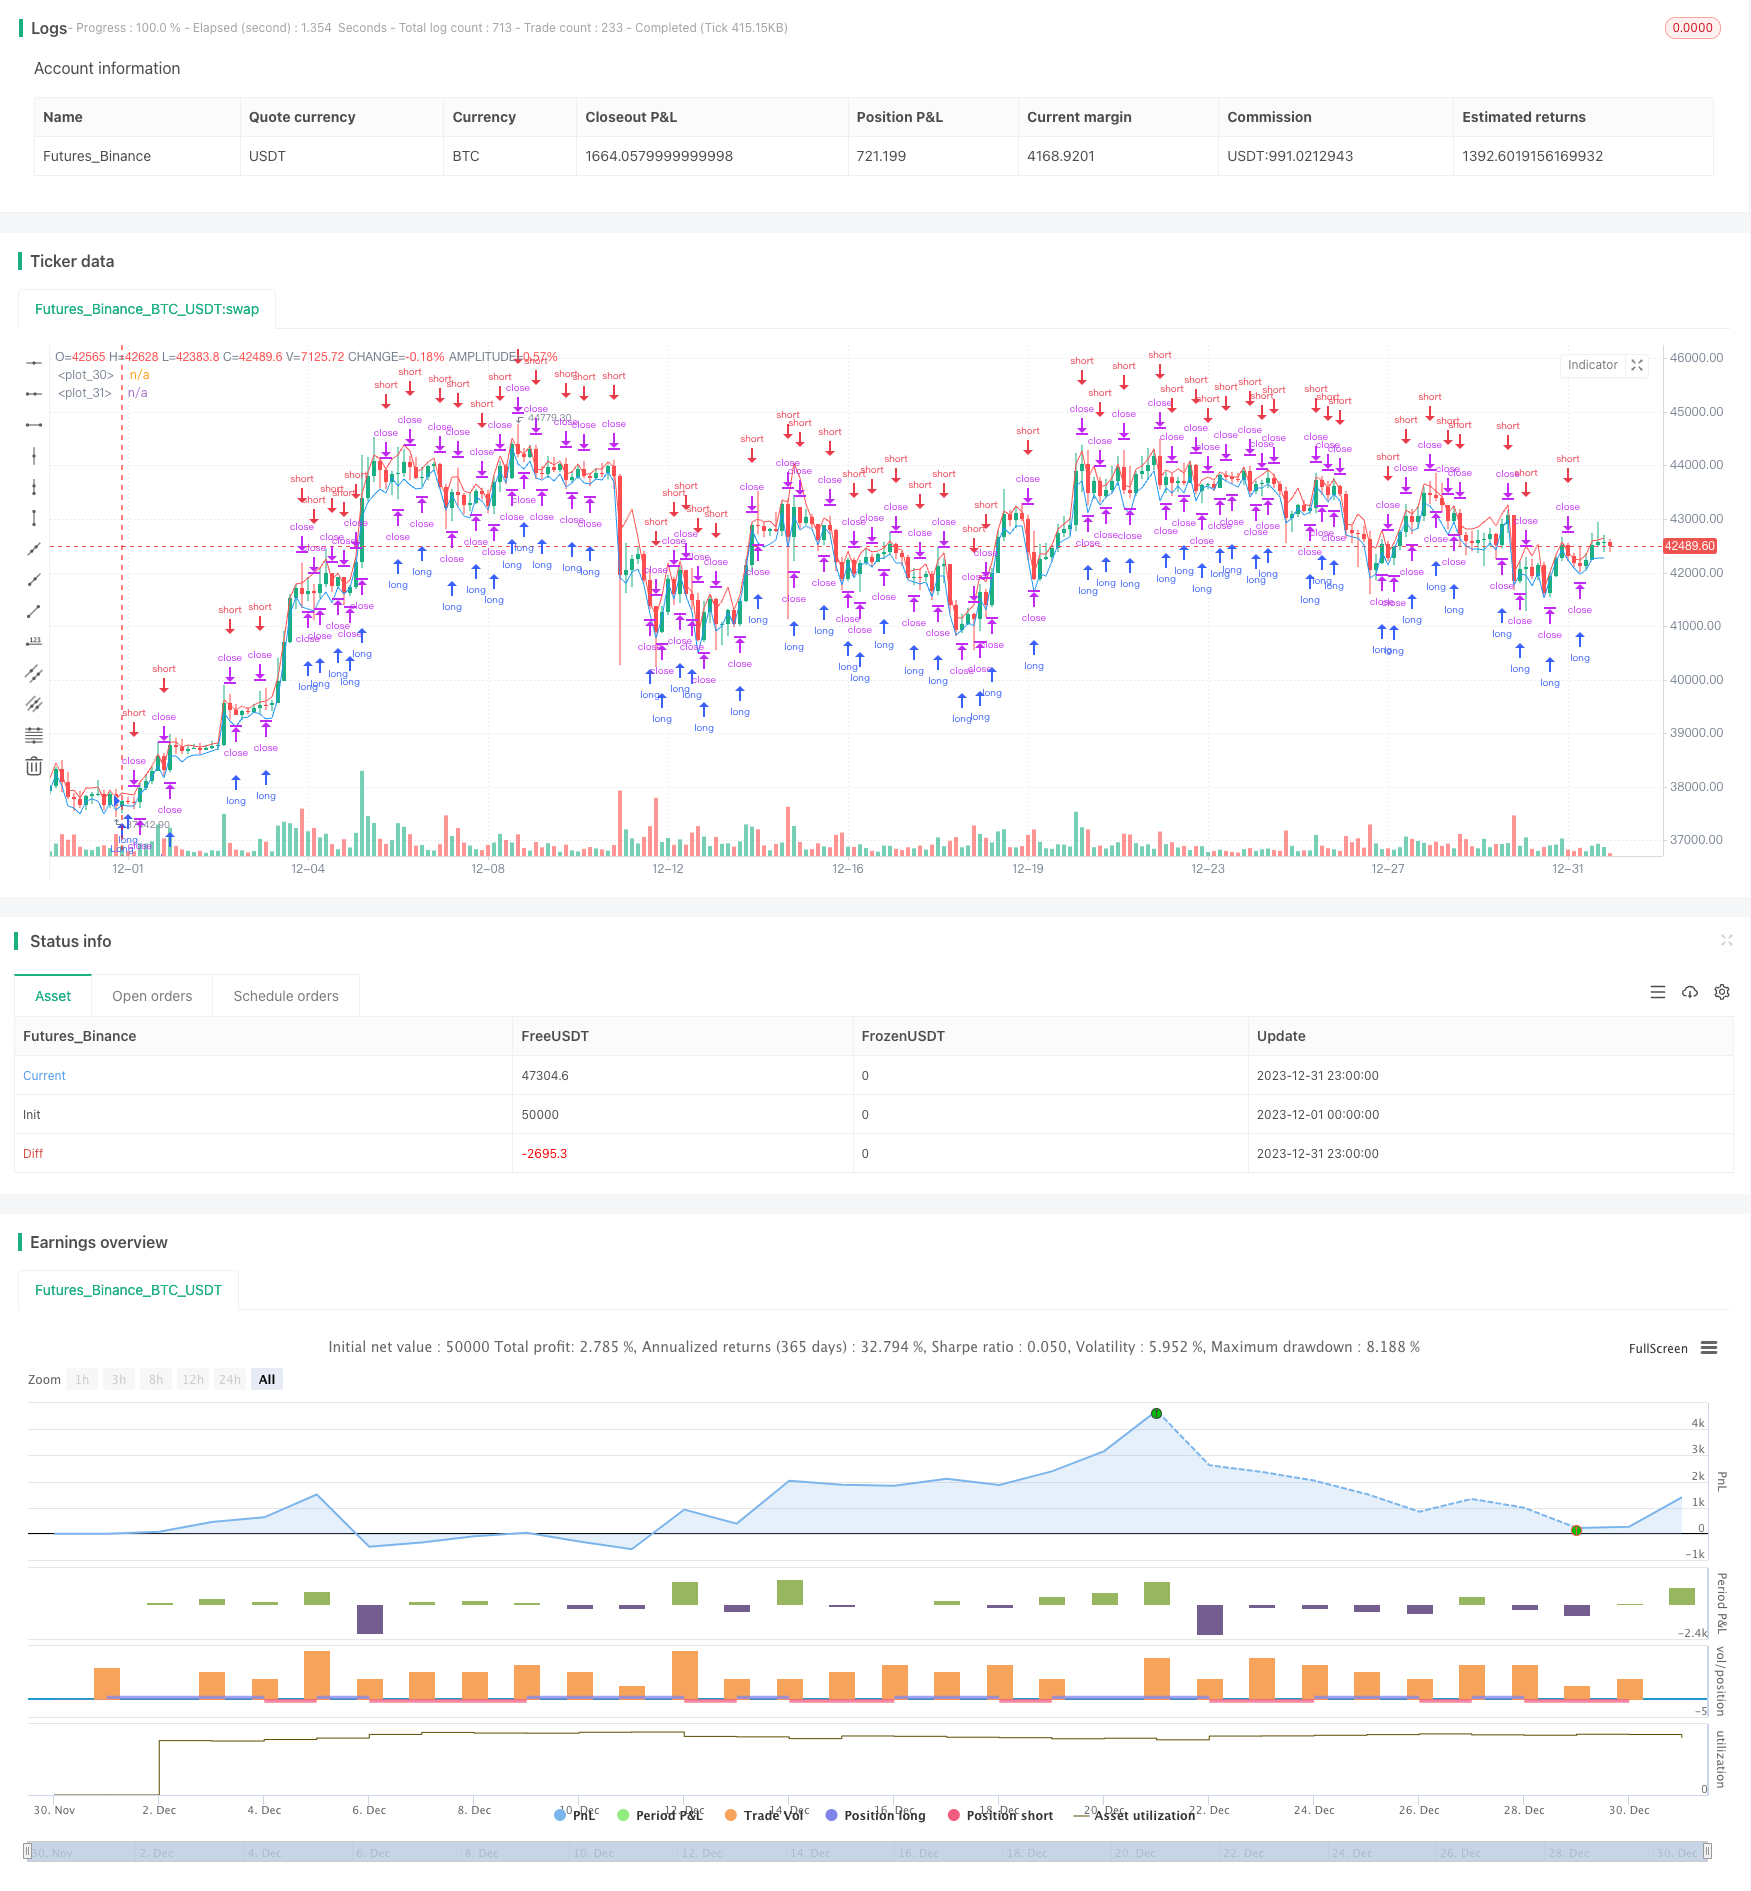
Overview
This is a high-frequency trading strategy based on the 3-minute K-line of the Coinbase exchange. It calculates the upper and lower shadow lines of the K-line to determine if there is a reversal opportunity in the short term. When the rise or fall of the price is relatively large, the strategy will take a position opposite to the trend, expecting a short-term reversal.
Principle
The strategy mainly judges whether there are opportunities for "overbought" or "oversold" in the short term. "Oversold and overbought" usually comes from overly optimistic or pessimistic emotions in the market. When such temporary emotional imbalances occur, prices usually reverse.
Specifically, the strategy calculates the size of the upper and lower shadow lines of the K-line. The larger the shadow line, the more intense the confrontation between buying power and selling power before the closing of the current K-line. If the upper shadow line is too large, it means that many buying orders were defeated by selling orders before the closing of the K-line, indicating that the bullish power is about to weaken. If the lower shadow line is too large, it means that many selling orders were absorbed by buying orders before the closing of the K-line, indicating that bearish power is about to weaken.
According to this logic, when the shadow line is too large (that is, when the price appears "overbought" or "oversold" in the short term), the strategy chooses to take a position opposite to the trend. The stop loss price for establishing a long position is the mid-price of the lower shadow line, and the stop loss price for establishing a short position is the mid-price of the upper shadow line.
Advantage Analysis
The biggest advantage of this strategy is to leverage the short-term irrational fluctuations in the market to achieve reverse arbitrage. It only requires relatively little capital to achieve high efficiency.
Another advantage is that Coinbase is an exchange with greater fluctuations. This strategy takes advantage of its volatile prices to make profits.
Risk Analysis
The biggest risk faced by this strategy is that short-term price fluctuations may not have much predictability. The size of the upper and lower shadow lines may not fully capture all the information about price reversals. Irrational emotions of traders may not follow logical rules either. So there is still some randomness risk in this strategy.
In addition, the setting of stop loss points is also critical. Stop loss points that are too loose may increase the loss of the strategy. Stop loss points that are too strict may miss opportunities. A balance needs to be found between risk-reward ratio and win rate.
Optimization Directions
This strategy can be further optimized in the following dimensions:
- Test different trading varieties, such as more volatile cryptocurrencies
- Optimize the setting logic of stop loss points, such as stop loss combined with ATR
- Add machine learning models to judge the probability of price reversal
- Combine sentiment indicators to measure market optimism/pessimism index
- Optimize position sizing and money management strategies
Summary
Overall, this strategy is a typical statistical arbitrage strategy. It tries to take advantage of short-term irrational price fluctuations to make profits, with some logic and feasibility. The next step is to conduct optimization experiments from more dimensions to make the parameter settings and trading rules of the strategy more scientific and systematic.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2019 | From Year |
| v_input_2 | 12 | From Month |
| v_input_3 | true | From day |
| v_input_4 | 2100 | To Year |
| v_input_5 | 12 | To Month |
| v_input_6 | 31 | To day |
| v_input_7 | 3 | period |
| v_input_8 | 1.2 | sigma |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//for coinbase, 3min logic
//This strategy trades against the short term trend. The first position can be either long or short.
//In the short term, prices fluctuate up and down on wide spread exchanges.
//And if the price moves to one side, the price tends to return to its original position momentarily.
//This strategy set stop order. Stop price is calculated with upper and lower shadows.

strategy("ndb_mm_for_coinbase_btcusd", overlay=true, initial_capital=100000, slippage=50)

fromyear = input(2019, minval = 2017, maxval = 2100, title = "From Year")
frommonth = input(12, minval = 1, maxval = 12, title = "From Month")
fromday = input(1, minval = 01, maxval = 31, title = "From day")
toyear = input(2100, minval = 1900, maxval = 2100, title = "To Year")
tomonth = input(12, minval = 01, maxval = 12, title = "To Month")
today = input(31, minval = 01, maxval = 31, title = "To day")
end = true

length = input(3, title="period")
mag = input(1.2, title="sigma", minval=0.1, step=0.1)

up_shadow = abs(high - max(open, close))
dn_shadow = abs(low - min(open, close))

up_shadow_ma = sma(up_shadow, length) * mag
dn_shadow_ma = sma(dn_shadow, length) * mag

upper = close + dn_shadow_ma
lower = close - up_shadow_ma

plot(upper, color=red)
plot(lower, color=blue)

if strategy.position_size == 0
    strategy.entry("Long", strategy.long)

if 0 < strategy.position_size
    strategy.entry("Short", strategy.short, stop=lower, when=end)

if 0 > strategy.position_size
    strategy.entry("Long", strategy.long, stop=upper, when=end)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Reversal-High-Frequency-Trading-Strategy-Based-on-Shadow-Line.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d