Strategy vault / Mean reversion
RSI and Stochastic RSI Combination Strategy
The strategy is named RSI and Stochastic RSI Combination Strategy. It combines the advantages of Relative Strength Index (RSI) and Stochastic RSI to identify overbought and oversold opportunities. The strategy works…
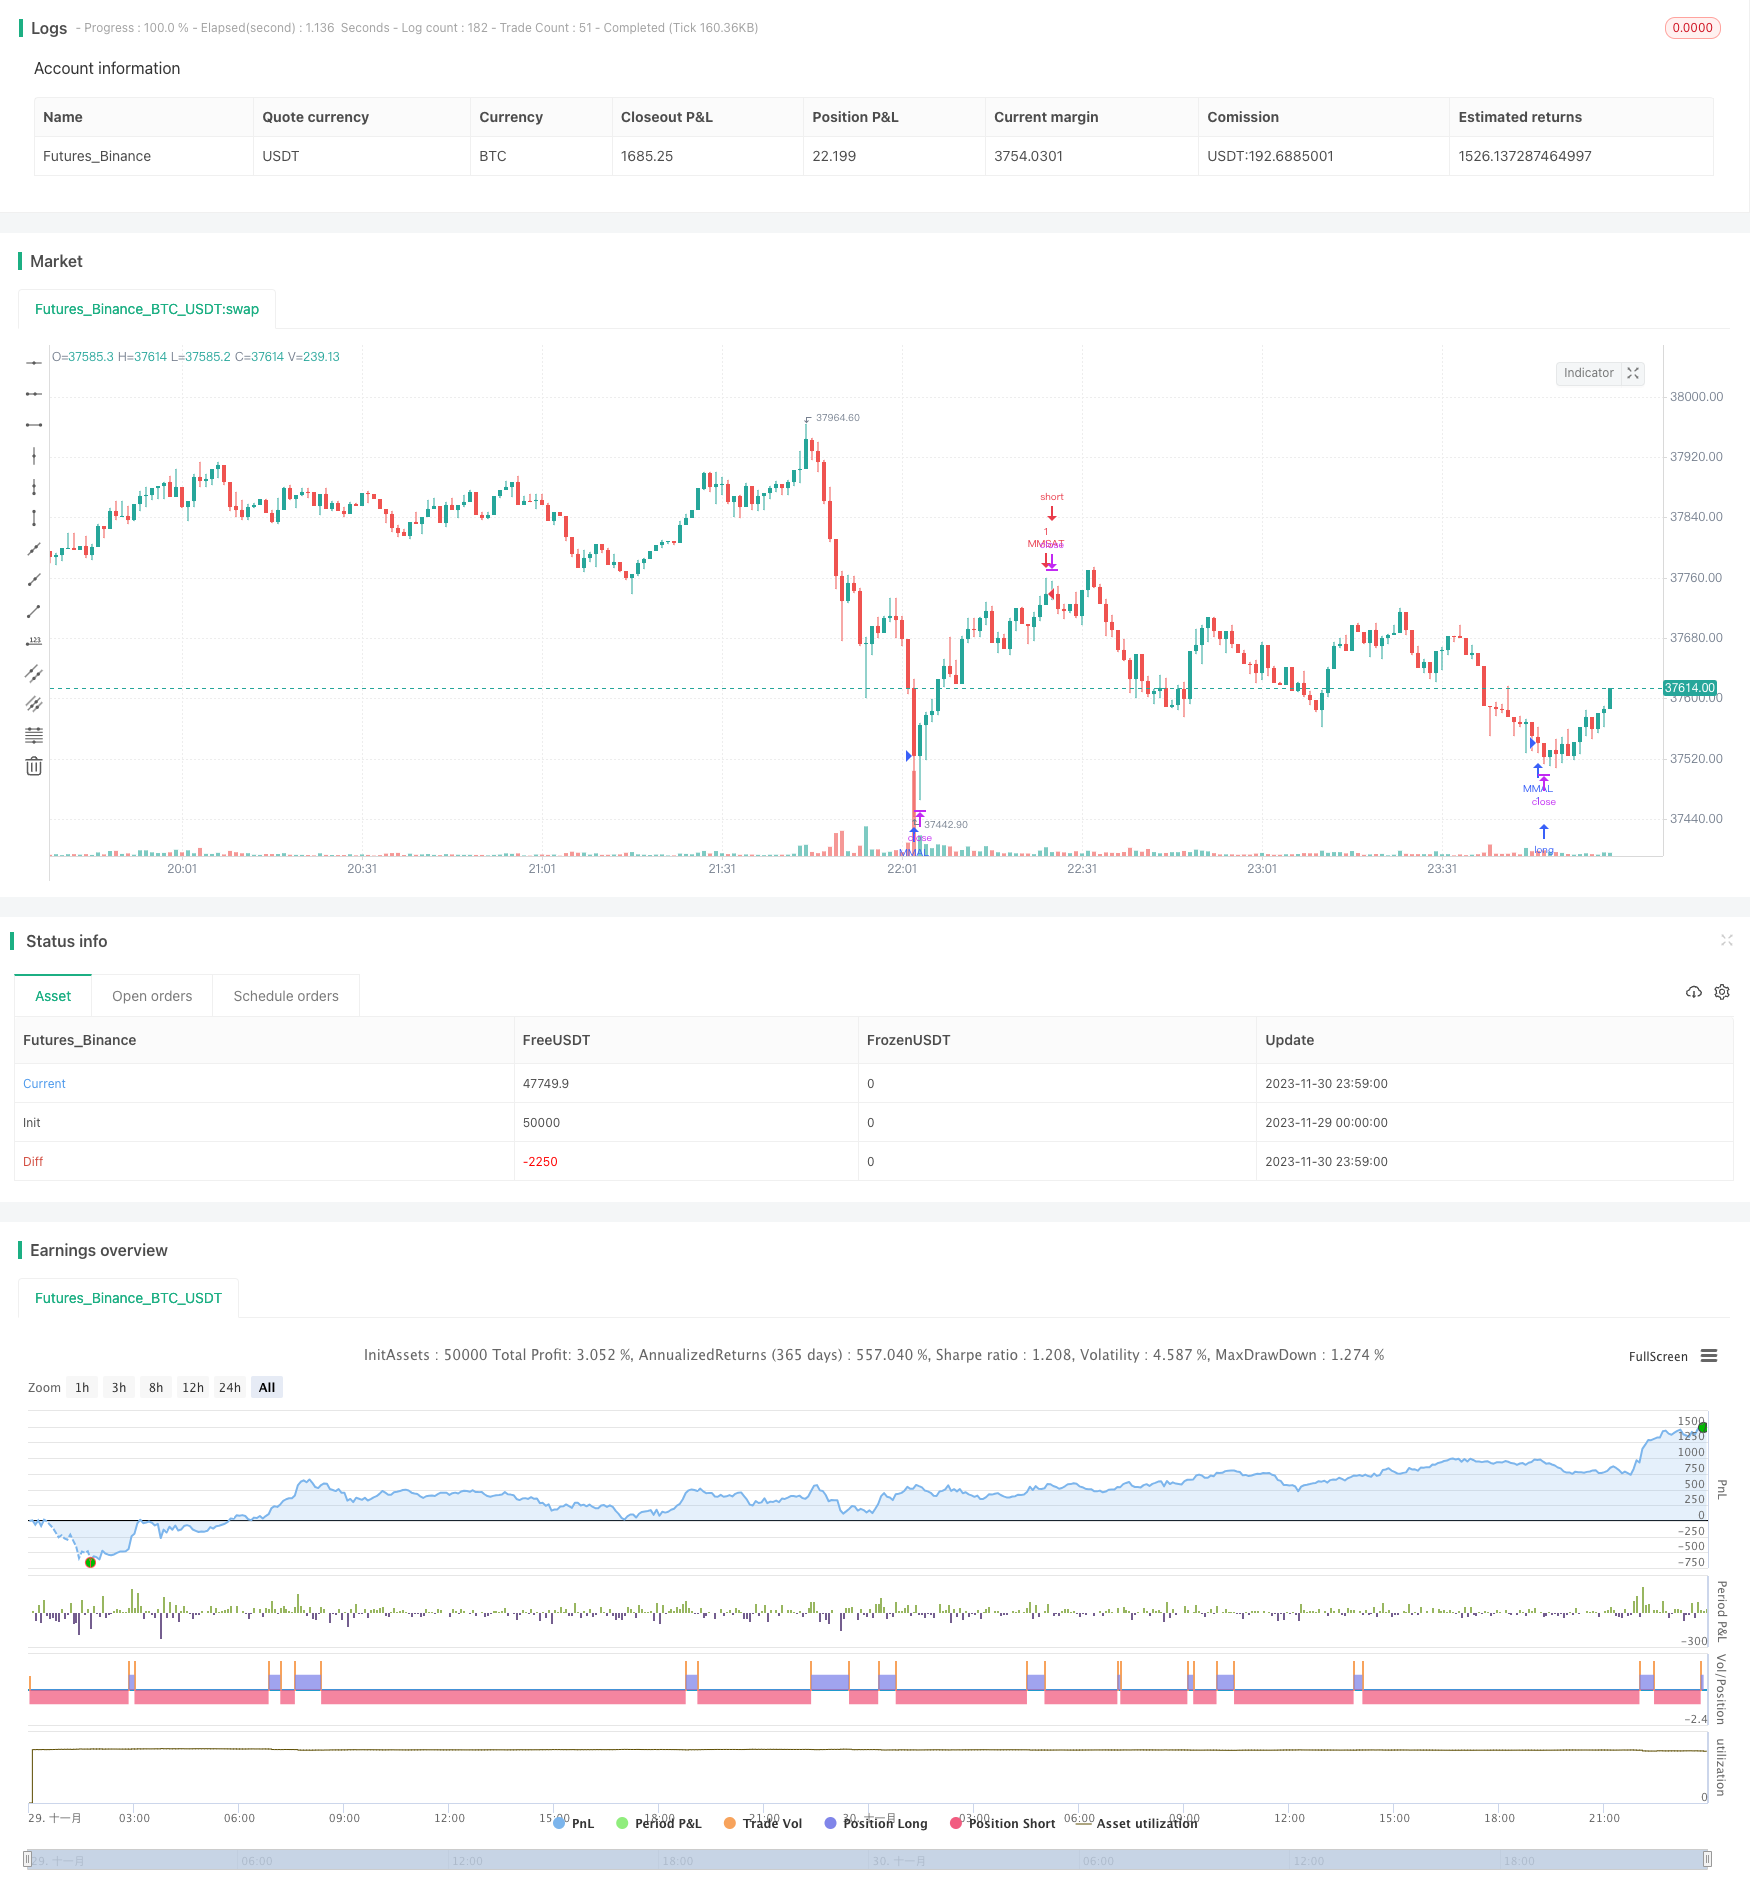
Overview
The strategy is named RSI and Stochastic RSI Combination Strategy. It combines the advantages of Relative Strength Index (RSI) and Stochastic RSI to identify overbought and oversold opportunities. The strategy works well on 5-minute charts for EOS/BTC and BTC/USDT, not suitable for all cryptocurrencies.
Strategy Logic
The strategy uses both RSI indicator and Stochastic RSI indicator. The RSI parameters are length of 10 periods, overbought level at 60 and oversold level at 20. The Stochastic RSI parameters include smoothing period of K line at 3, smoothing period of D line at 3, RSI calculation length of 14, Stochastic RSI calculation length of 14. It identifies oversold when Stochastic RSI K and D values are both below 20, and overbought when Stochastic RSI K and D values are both above 80. Trading signals are generated at overbought and oversold levels.
Advantage Analysis
The strategy combines the advantages of RSI indicator and Stochastic RSI indicator. RSI is effective at identifying overbought and oversold situations. Stochastic RSI incorporates momentum and can detect turning points earlier. The combination works better by considering both price and momentum factors to generate more timely trading signals.
Risk Analysis
The strategy may face risks of too many trades and insufficient profit margin per trade. Solutions include properly adjusting parameters to lower trading frequency and selecting products with larger price swings. In addition, trading costs can also impact the final profit. It's recommended to choose trading platforms with lower commissions or appropriately scale up position sizes.
Improvement Directions
Parameters of this strategy can be further optimized, such as adjusting RSI parameters, Stochastic RSI parameters, overbought/oversold threshold values etc. In addition, other indicators like EMA can be combined to filter signals and improve quality. Trying multi-product combinations to utilize correlations between different products can also help obtain more stable overall returns.
Conclusion
The strategy integrates the advantages of RSI indicator and Stochastic RSI indicator to generate trading signals at relative overbought and oversold levels. Parameters can be further tuned and trading rules can be customized for different products. Combinations with other strategies or indicators can also be explored. Overall speaking, this strategy suits quantitative traders looking to identify short-term trading opportunities.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | length |
| v_input_2 | 20 | overSold |
| v_input_3 | 60 | overBought |
| v_input_4 | 3 | smoothK |
| v_input_5 | 3 | smoothD |
| v_input_6 | 14 | lengthRSI |
| v_input_7 | 14 | lengthStoch |
| v_input_8_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_9 | 20 | srsilow |
| v_input_10 | 80 | srsiup |
| v_input_11 | 2018 | yearfrom |
| v_input_12 | 2019 | yearuntil |
| v_input_13 | true | monthfrom |
| v_input_14 | 12 | monthuntil |
| v_input_15 | true | dayfrom |
| v_input_16 | 31 | dayuntil |
Source Pine Script
/*backtest
start: 2023-11-29 00:00:00
end: 2023-12-01 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("RSI+STOCHRSI", overlay=true)
length = input( 10)
overSold = input( 20 )
overBought = input( 60 )
price = close
vrsi = rsi(price, length)

smoothK = input(3, minval=1)
smoothD = input(3, minval=1)
lengthRSI = input(14, minval=1)
lengthStoch = input(14, minval=1)
src = input(close, title="RSI Source")

rsi1 = rsi(src, lengthRSI)
k = sma(stoch(rsi1, rsi1, rsi1, lengthStoch), smoothK)
d = sma(k, smoothD)
srsilow=input(20)
srsiup=input(80)

sourceup = high
sourcelow = low
source=close


yearfrom = input(2018)
yearuntil =input(2019)
monthfrom =input(1)
monthuntil =input(12)
dayfrom=input(1)
dayuntil=input(31)


if (  (d<srsilow) and (k<srsilow) and (vrsi<overSold))
    strategy.entry("MMAL", strategy.long, stop=close, oca_name="TREND", comment="AL")
else
    strategy.cancel(id="MMAL")


if ( (d> srsiup ) and (k>srsiup ) and (vrsi >overBought) )
    strategy.entry("MMSAT", strategy.short,stop=close, oca_name="TREND",  comment="SAT")
else
    strategy.cancel(id="MMSAT")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-07. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-and-Stochastic-RSI-Combination-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- 3EMA with Stochastic RSI StrategyPine Script · Mean reversion · 1h
- Dual Reversal Overlap Selective StrategyPine Script · Mean reversion · 1h
- Market Cypher Wave B Automated Trading StrategyPine Script · Mean reversion · 1h