Strategy vault / Trend following
RSI and Trend MA Dual Filter Trading Strategy
This strategy is a dual-filter trading system combining RSI (Relative Strength Index) and trend moving average. It operates on daily timeframes by integrating RSI overbought/oversold signals with long-term trend…
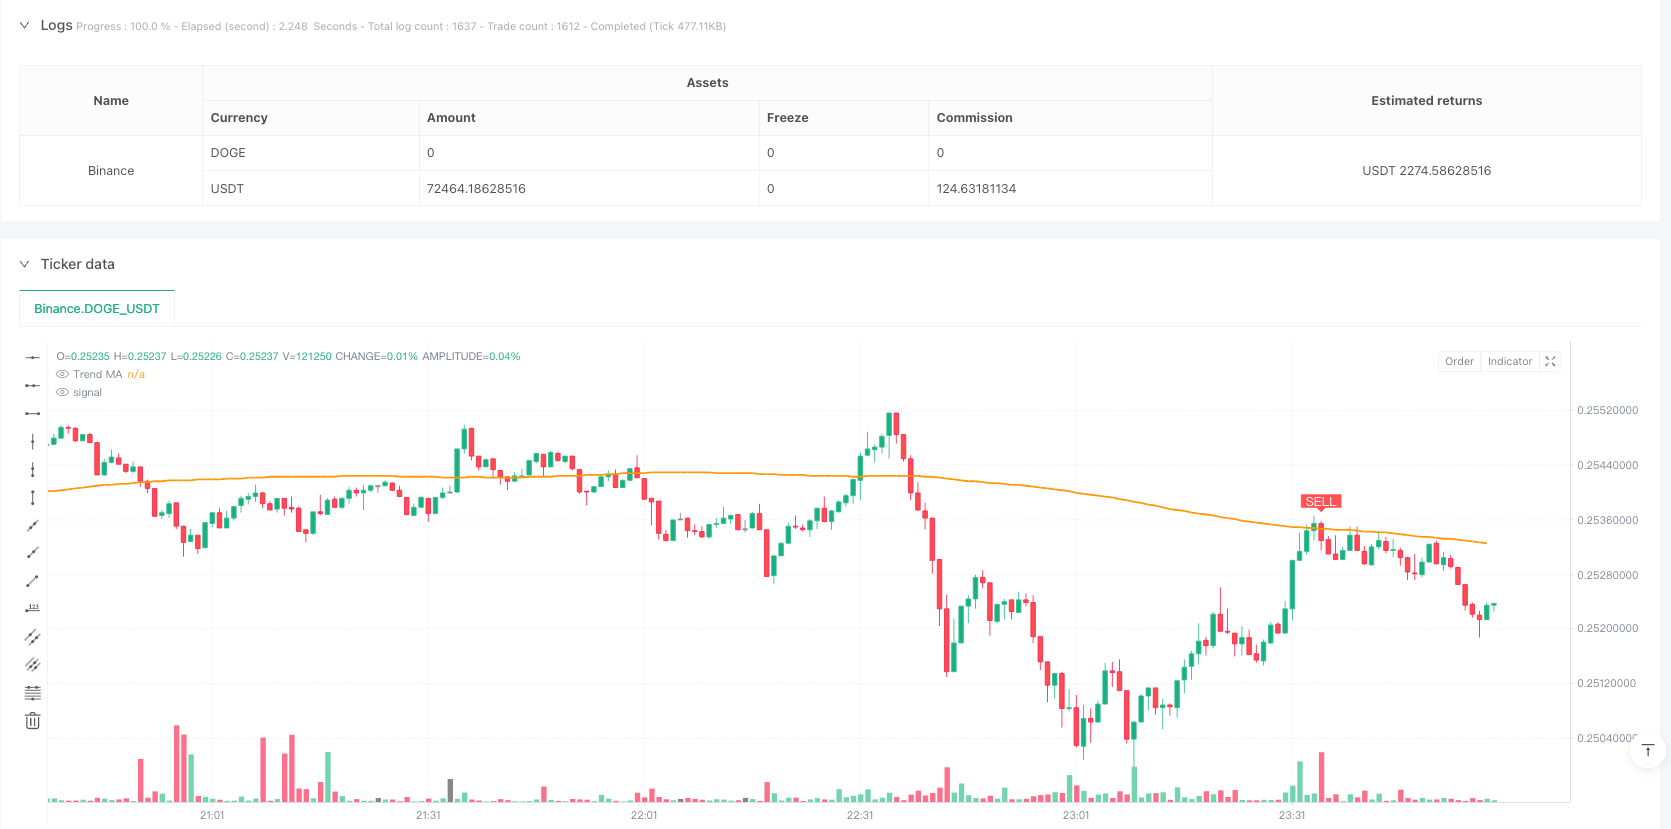
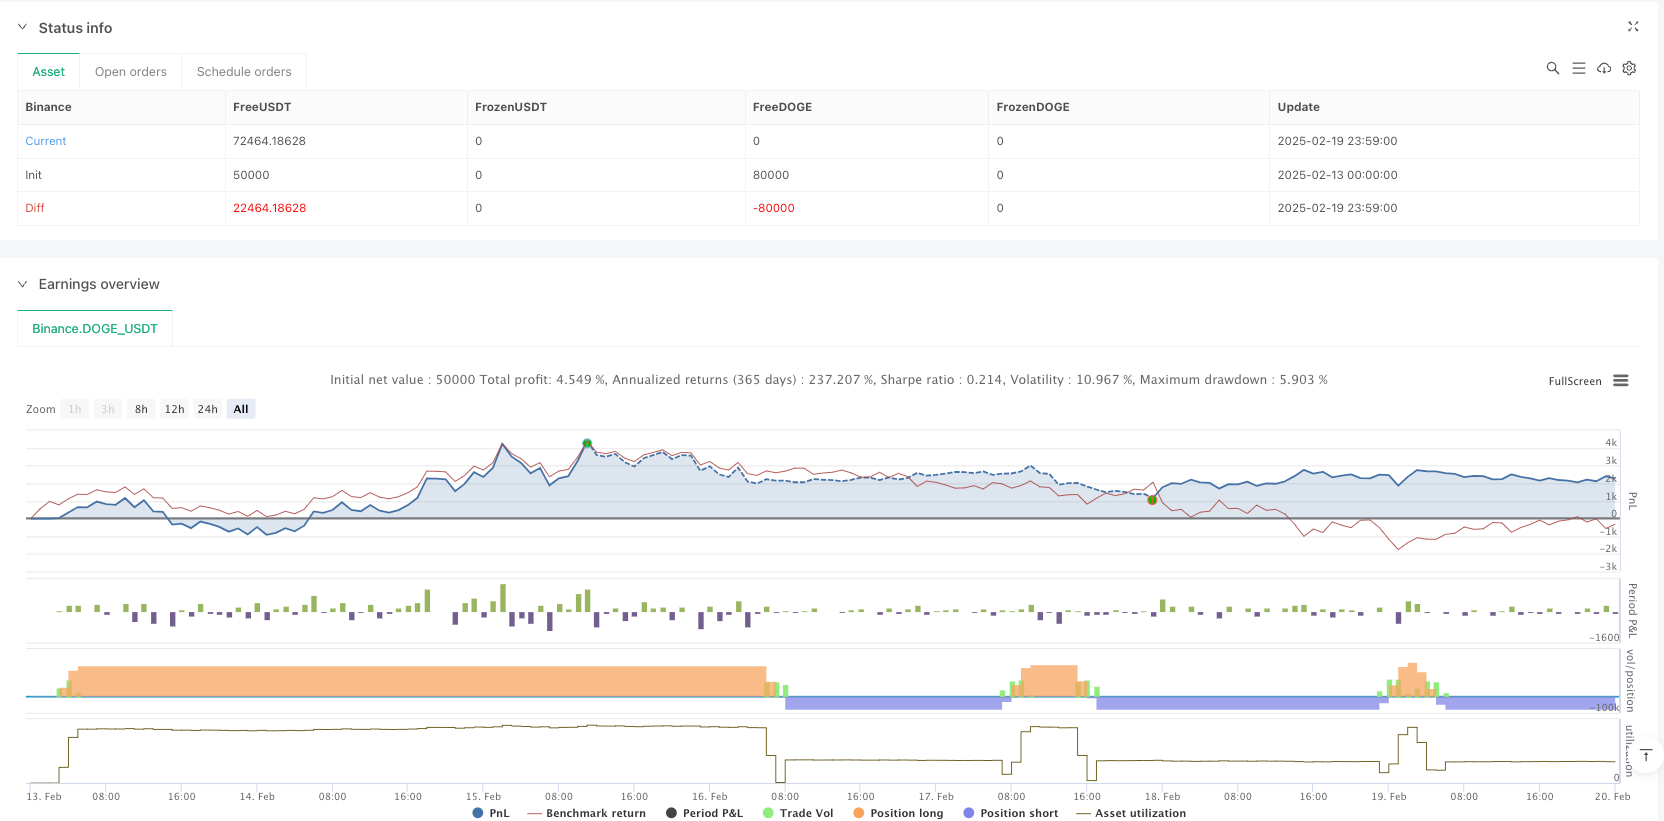
Overview
This strategy is a dual-filter trading system combining RSI (Relative Strength Index) and trend moving average. It operates on daily timeframes by integrating RSI overbought/oversold signals with long-term trend moving averages. The core innovation lies in adding a trend filter to traditional RSI trading signals to enhance accuracy and reliability.
Strategy Principles
The strategy is based on the following core components:
- RSI indicator for identifying overbought/oversold areas, default period 14
- Overbought level set at 70, oversold level at 30
- 200-period simple moving average as trend filter
- Buy condition: RSI crosses above oversold level with price above MA
- Sell condition: RSI crosses below overbought level with price below MA The strategy automatically executes trades at each signal and can be configured with alerts.
Strategy Advantages
- Dual confirmation mechanism significantly improves trading reliability
- Combines trend and momentum indicators to reduce false signals
- Fully automated trading execution system
- Flexible parameter settings allow strategy optimization
- Integrated real-time alerts for practical operation
- Clear visualization of trading signals
- Supports backtesting for strategy validation
Strategy Risks
- May generate frequent signals in choppy markets
- Potential lag at trend reversal points
- Performance may be affected by improper parameter settings
- Large drawdowns possible during extreme market volatility Risk management recommendations:
- Set appropriate stop-loss levels
- Adjust position sizing properly
- Regularly optimize strategy parameters
- Incorporate additional technical indicators for confirmation
Strategy Optimization Directions
- Add volatility filter to adjust trading criteria during high volatility periods
- Implement adaptive parameters based on market conditions
- Incorporate volume confirmation to improve signal reliability
- Develop more sophisticated exit mechanisms
- Integrate multiple timeframe analysis for broader market perspective
Summary
This strategy builds a robust trading system by combining RSI and trend moving averages. The design is rational, with clear operational rules and good practicality. Through proper risk management and continuous optimization, this strategy has the potential to achieve stable returns in actual trading.
Source Pine Script
/*backtest
start: 2025-02-13 00:00:00
end: 2025-02-20 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Binance","currency":"DOGE_USDT"}]
*/

//@version=5
strategy("Leading Indicator Strategy – Daily Signals", overlay=true,
     pyramiding=1, initial_capital=100000,
     default_qty_type=strategy.percent_of_equity, default_qty_value=100)

/// **Inputs for Customization**
rsiLength   = input.int(14,  minval=1, title="RSI Period")
oversold    = input.float(30.0, minval=1, maxval=50, title="Oversold Level")
overbought  = input.float(70.0, minval=50, maxval=100, title="Overbought Level")
maLength    = input.int(200, minval=1, title="Trend MA Period")
useTrendFilter = input.bool(true, title="Use Trend Filter (MA)",
     tooltip="Require price above MA for buys and below MA for sells")

/// **Indicator Calculations**
rsiValue = ta.rsi(close, rsiLength)                      // RSI calculation
trendMA  = ta.sma(close, maLength)                       // Long-term moving average

/// **Signal Conditions** (RSI crosses with optional trend filter)
buySignal  = ta.crossover(rsiValue, oversold)            // RSI crosses above oversold level
sellSignal = ta.crossunder(rsiValue, overbought)         // RSI crosses below overbought level

bullCond = buySignal and (not useTrendFilter or close > trendMA)   // final Buy condition
bearCond = sellSignal and (not useTrendFilter or close < trendMA)  // final Sell condition

/// **Trade Execution** (entries and exits with alerts)
if bullCond
    strategy.close("Short",  alert_message="Buy Signal – Closing Short")   // close short position if open
    strategy.entry("Long",  strategy.long,  alert_message="Buy Signal – Enter Long")  // go long
if bearCond
    strategy.close("Long",   alert_message="Sell Signal – Closing Long")   // close long position if open
    strategy.entry("Short", strategy.short, alert_message="Sell Signal – Enter Short") // go short

/// **Plotting** (MA and signal markers for clarity)
plot(trendMA, color=color.orange, linewidth=2, title="Trend MA")
plotshape(bullCond, title="Buy Signal", style=shape.labelup, location=location.belowbar,
     color=color.green, text="BUY", textcolor=color.white)
plotshape(bearCond, title="Sell Signal", style=shape.labeldown, location=location.abovebar,
     color=color.red, text="SELL", textcolor=color.white)

// (Optional) Plot RSI in a separate pane for reference:
// plot(rsiValue,  title="RSI", color=color.blue)
// hline(oversold, title="Oversold",  color=color.gray, linestyle=hline.style_dotted)
// hline(overbought, title="Overbought", color=color.gray, linestyle=hline.style_dotted)
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-and-Trend-MA-Dual-Filter-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Dual SMA Crossover StrategyPine Script · Trend following · 5m
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Trend Detection Strategy Based on Gaussian Channel and Stochastic RSI FilterPine Script · Trend following · 1h
- YinYang RSI Volume Trend Trading StrategyPine Script · Trend following · 1h
- AlphaTrend Dual Tracking StrategyPine Script · Trend following · 1h