Strategy vault / Mean reversion
RSI Bullish and Bearish Divergence Trading Strategy
This strategy judges the bullish and bearish trends of the market and makes trading decisions by calculating the divergence of RSI indicator. Specifically, it will judge hidden bullish signals when RSI forms lower…
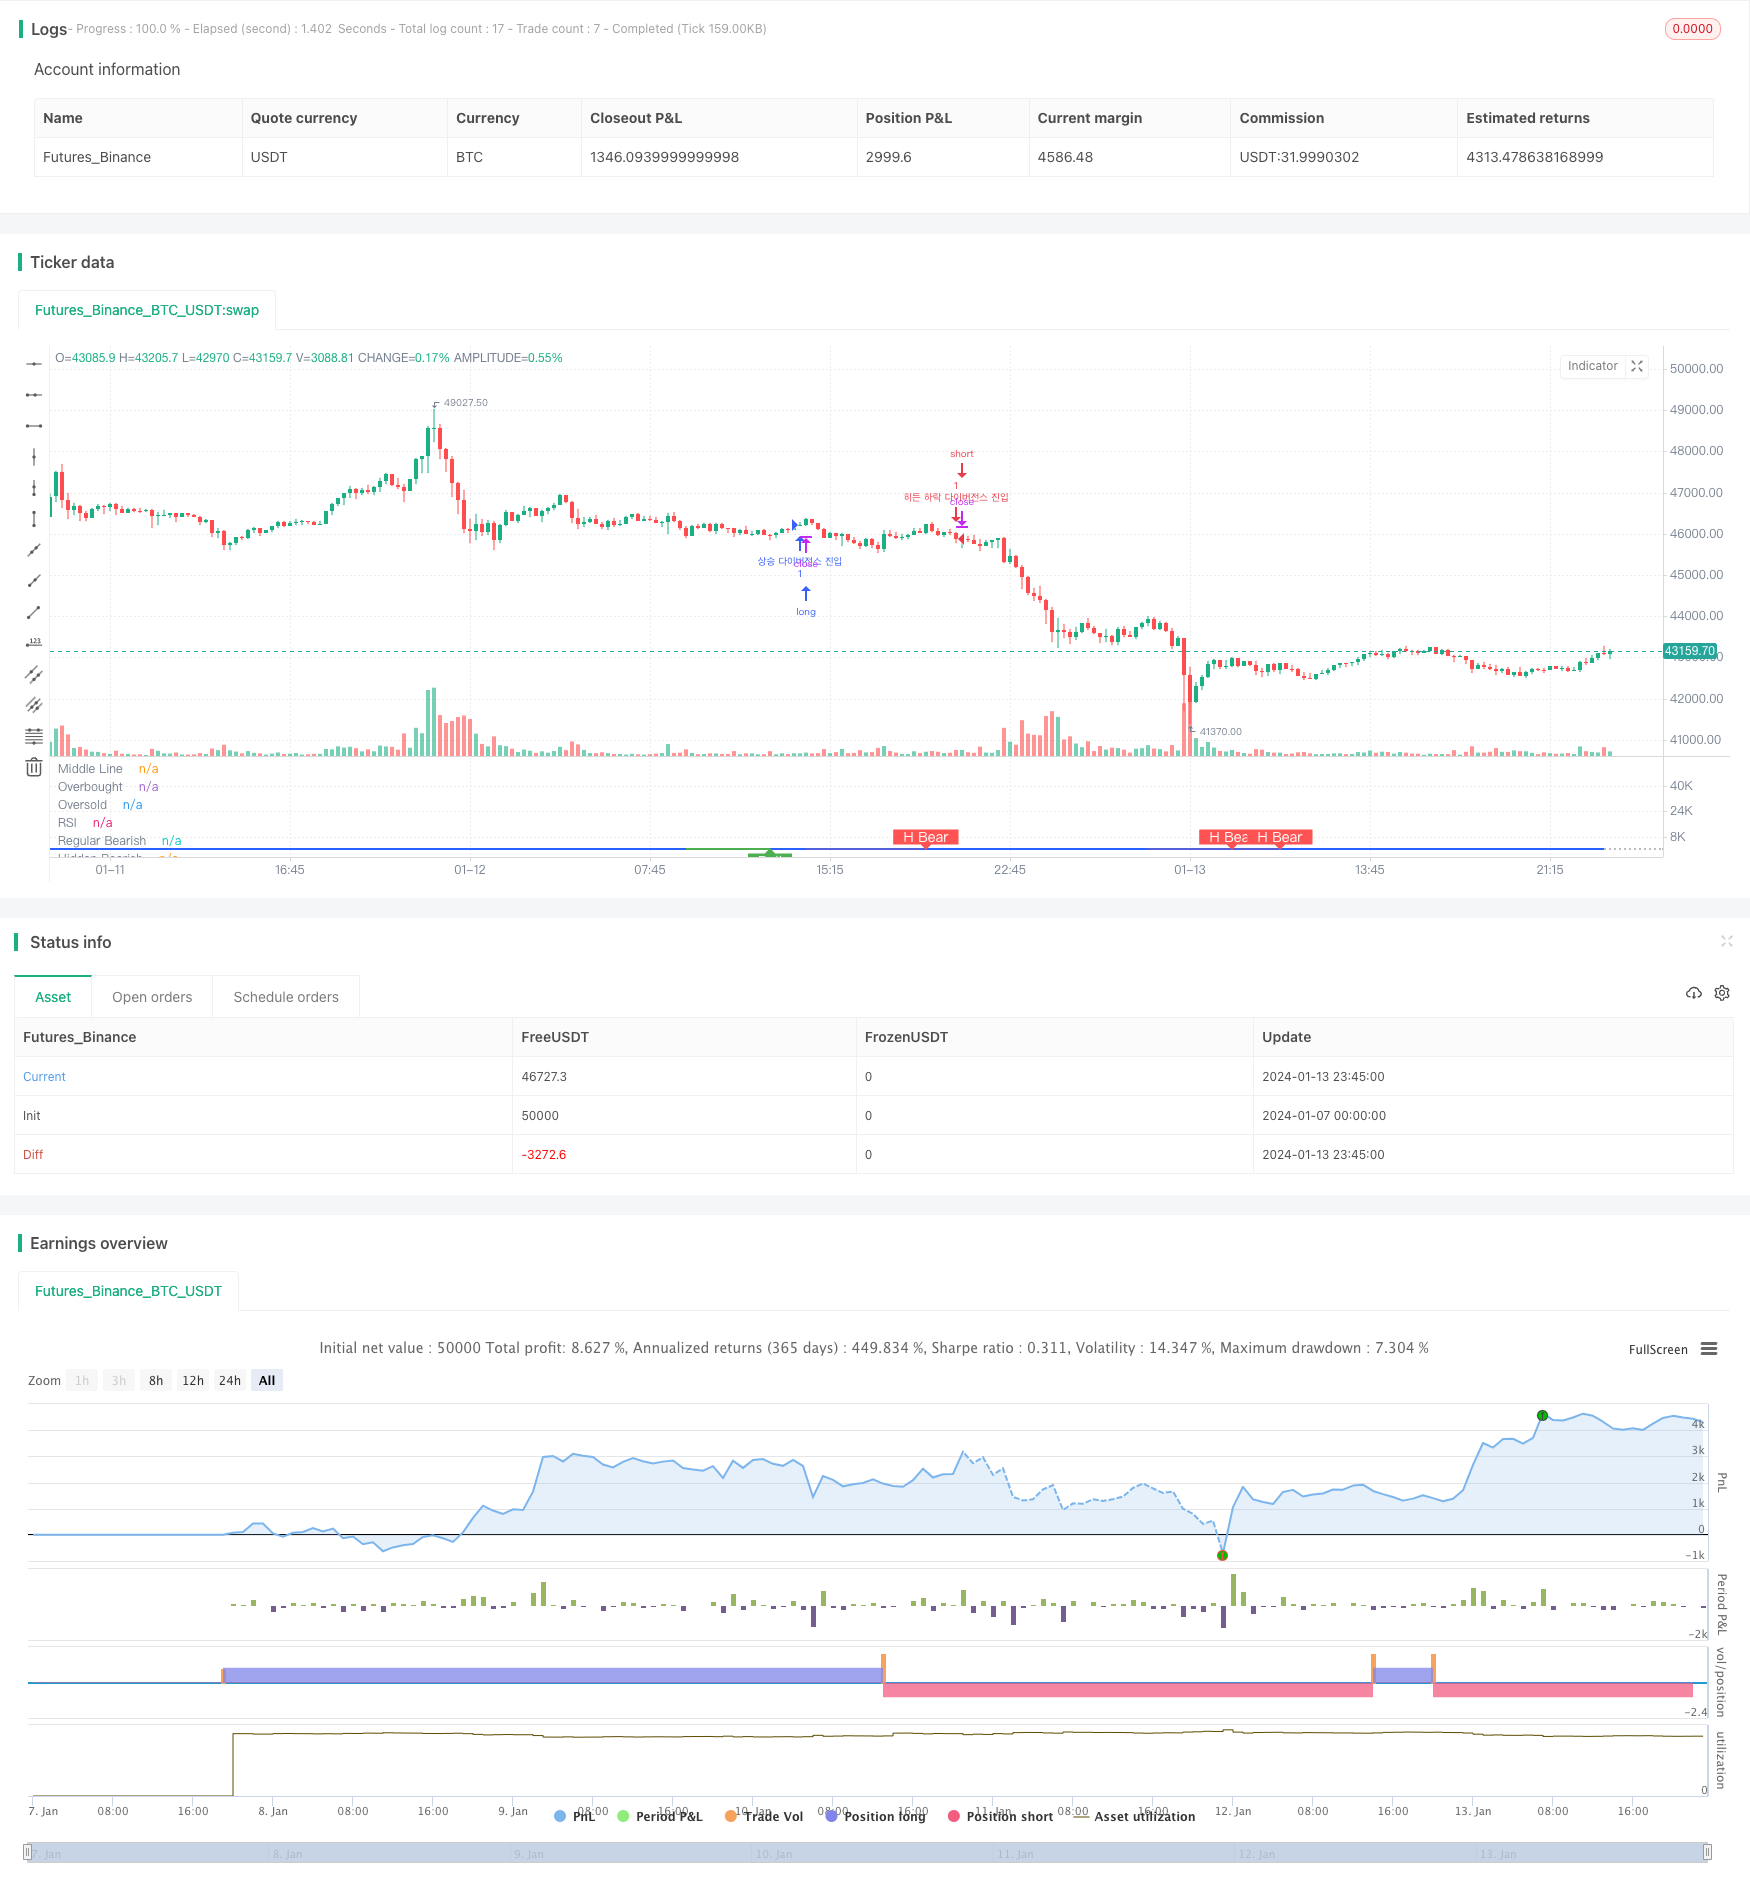
Overview
This strategy judges the bullish and bearish trends of the market and makes trading decisions by calculating the divergence of RSI indicator. Specifically, it will judge hidden bullish signals when RSI forms lower lows but prices form higher lows. And it will judge hidden bearish signals when RSI forms higher highs but prices form lower highs. Then it determines the potential bullish or bearish trends of the market based on these signals and makes trades.
Strategy Logic
The strategy is mainly based on the bullish and bearish divergence theory of RSI indicator. When RSI and price form reverse divergences, it indicates potential reversals of the market. There are four specific situations:
Regular Bullish Signal: RSI forms higher low while price forms lower low. It indicates the buying power pushes up the RSI but not fully reflects on the price, implying strengthened bullish power.
Hidden Bullish Signal: RSI forms lower low while price forms higher low. It implies the selling power pushes down the RSI but not the price, indicating strengthened bullish power.
Regular Bearish Signal: RSI forms lower high while price forms higher high. It implies the selling power pushes up the price but not RSI, indicating strengthened bearish power.
Hidden Bearish Signal: RSI forms higher high while price forms lower high. It indicates buying power pushes up RSI but not price, implying strengthened bearish power.
Based on the above divergences, it judges the potential bullish or bearish trends of the market and the strengthening of buying/selling power to formulate trading strategies.
Advantages
- Utilize the bullish and bearish divergence theory of RSI to determine the potential trends of market.
- Also combine price actions to confirm, avoiding noisy signals.
- Able to capture critical signals before fast reversals of market.
- Implement visualized indication for bullish and bearish signals, easy and intuitive to operate.
- Customizable parameters fitting different market environments.
Risks
- Divergences between RSI and price may not necessarily imply reversals, could just be range-bound actions.
- Hidden signals have relatively larger noise, risks of misjudgement.
- Need to incorporate more indicators or technical analysis methods to confirm the signals.
- Improper parameter settings may also affect the judgements.
Enhancement Directions
- Incorporate MACD, KDJ and other indicators with RSI to determine entry signals.
- Add stop loss strategy to reduce losses per trade.
- Optimize parameter settings like searching for more suitable RSI periods.
- Introduce machine learning algorithms to train the accuracy of capturing entry signals.
- Implement websocket for real-time quotes to reduce signal confirmation latency.
Summary
The strategy mainly leverages the bullish and bearish divergences of RSI to determine the potential bullish or bearish trends of market by capturing the relative strength changes between buying and selling power behind the price actions. It has certain predictive capabilities of reversals. But it also has risks of noisy signals. Ways like parameter optimization, indicator combination, machine learning can help further enhance the stability and profitability of the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 20 | RSI Period |
| v_input_1_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 5 | Pivot Lookback Right |
| v_input_3 | 5 | Pivot Lookback Left |
| v_input_4 | 60 | Max of Lookback Range |
| v_input_5 | 5 | Min of Lookback Range |
| v_input_6 | true | Plot Bullish |
| v_input_7 | true | Plot Hidden Bullish |
| v_input_8 | true | Plot Bearish |
| v_input_9 | true | Plot Hidden Bearish |
Source Pine Script
/*backtest
start: 2024-01-07 00:00:00
end: 2024-01-14 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy(title="Divergence Indicator")
len = input.int(title="RSI Period", minval=1, defval=20)
src = input(title="RSI Source", defval=close)
lbR = input(title="Pivot Lookback Right", defval=5)
lbL = input(title="Pivot Lookback Left", defval=5)
rangeUpper = input(title="Max of Lookback Range", defval=60)
rangeLower = input(title="Min of Lookback Range", defval=5)
plotBull = input(title="Plot Bullish", defval=true)
plotHiddenBull = input(title="Plot Hidden Bullish", defval=true)
plotBear = input(title="Plot Bearish", defval=true)
plotHiddenBear = input(title="Plot Hidden Bearish", defval=true)
bearColor = color.red
bullColor = color.green
hiddenBullColor = color.new(color.green, 80)
hiddenBearColor = color.new(color.red, 80)
textColor = color.white
noneColor = color.new(color.white, 100)
osc = ta.rsi(src, len)

plot(osc, title="RSI", linewidth=2, color=#2962FF)
hline(50, title="Middle Line", color=#787B86, linestyle=hline.style_dotted)
obLevel = hline(70, title="Overbought", color=#787B86, linestyle=hline.style_dotted)
osLevel = hline(30, title="Oversold", color=#787B86, linestyle=hline.style_dotted)
fill(obLevel, osLevel, title="Background", color=color.rgb(33, 150, 243, 90))

plFound = na(ta.pivotlow(osc, lbL, lbR)) ? false : true
phFound = na(ta.pivothigh(osc, lbL, lbR)) ? false : true
_inRange(cond) =>
	bars = ta.barssince(cond == true)
	rangeLower <= bars and bars <= rangeUpper

//------------------------------------------------------------------------------
// Regular Bullish
// Osc: Higher Low

oscHL = osc[lbR] > ta.valuewhen(plFound, osc[lbR], 1) and _inRange(plFound[1])

// Price: Lower Low

priceLL = low[lbR] < ta.valuewhen(plFound, low[lbR], 1)
// bull : 상승 Condition : 조건
bullCond = plotBull and priceLL and oscHL and plFound // 상승다이버전스?
strategy.entry("상승 다이버전스 진입", strategy.long, when = bullCond)
// strategy.close("상승 다이버전스 진입", when = ta.crossover(osc, 70))
plot(
     plFound ? osc[lbR] : na,
     offset=-lbR,
     title="Regular Bullish",
     linewidth=2,
     color=(bullCond ? bullColor : noneColor)
     )

plotshape(
	 bullCond ? osc[lbR] : na,
	 offset=-lbR,
	 title="Regular Bullish Label",
	 text=" Bull ",
	 style=shape.labelup,
	 location=location.absolute,
	 color=bullColor,
	 textcolor=textColor
	 )

//------------------------------------------------------------------------------
// Hidden Bullish
// Osc: Lower Low

oscLL = osc[lbR] < ta.valuewhen(plFound, osc[lbR], 1) and _inRange(plFound[1])

// Price: Higher Low

priceHL = low[lbR] > ta.valuewhen(plFound, low[lbR], 1)
hiddenBullCond = plotHiddenBull and priceHL and oscLL and plFound
strategy.entry("히든 상승 다이버전스 진입", strategy.long, when = hiddenBullCond)
// strategy.close("히든 상승 다이버전스 진입", when = ta.crossover(osc, 70))
plot(
	 plFound ? osc[lbR] : na,
	 offset=-lbR,
	 title="Hidden Bullish",
	 linewidth=2,
	 color=(hiddenBullCond ? hiddenBullColor : noneColor)
	 )

plotshape(
	 hiddenBullCond ? osc[lbR] : na,
	 offset=-lbR,
	 title="Hidden Bullish Label",
	 text=" H Bull ",
	 style=shape.labelup,
	 location=location.absolute,
	 color=bullColor,
	 textcolor=textColor
	 )

//------------------------------------------------------------------------------
// Regular Bearish
// Osc: Lower High

oscLH = osc[lbR] < ta.valuewhen(phFound, osc[lbR], 1) and _inRange(phFound[1])

// Price: Higher High

priceHH = high[lbR] > ta.valuewhen(phFound, high[lbR], 1)
// bear : 하락
bearCond = plotBear and priceHH and oscLH and phFound
strategy.entry("하락 다이버전스 진입", strategy.short, when = bearCond)
// strategy.close("하락 다이버전스 진입", when = ta.crossunder(osc, 50))
plot(
	 phFound ? osc[lbR] : na,
	 offset=-lbR,
	 title="Regular Bearish",
	 linewidth=2,
	 color=(bearCond ? bearColor : noneColor)
	 )

plotshape(
	 bearCond ? osc[lbR] : na,
	 offset=-lbR,
	 title="Regular Bearish Label",
	 text=" Bear ",
	 style=shape.labeldown,
	 location=location.absolute,
	 color=bearColor,
	 textcolor=textColor
	 )

//------------------------------------------------------------------------------
// Hidden Bearish
// Osc: Higher High

oscHH = osc[lbR] > ta.valuewhen(phFound, osc[lbR], 1) and _inRange(phFound[1])

// Price: Lower High

priceLH = high[lbR] < ta.valuewhen(phFound, high[lbR], 1)

hiddenBearCond = plotHiddenBear and priceLH and oscHH and phFound
strategy.entry("히든 하락 다이버전스 진입", strategy.short, when = hiddenBearCond)
// strategy.close("히든 하락 다이버전스 진입", when = ta.crossunder(osc, 50))
plot(
	 phFound ? osc[lbR] : na,
	 offset=-lbR,
	 title="Hidden Bearish",
	 linewidth=2,
	 color=(hiddenBearCond ? hiddenBearColor : noneColor)
	 )

plotshape(
	 hiddenBearCond ? osc[lbR] : na,
	 offset=-lbR,
	 title="Hidden Bearish Label",
	 text=" H Bear ",
	 style=shape.labeldown,
	 location=location.absolute,
	 color=bearColor,
	 textcolor=textColor
)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Bullish-and-Bearish-Divergence-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic MACD and Ichimoku Cloud Trading StrategyPine Script · Mean reversion · 1h
- Quantitative Trading Strategy Based on Bollinger Bands and RSIPine Script · Mean reversion · 1h
- Trend Reversal Momentum Indicators Crossover Tracking StrategyPine Script · Mean reversion · 1h
- Multi Timeframe Gold Reversal Tracking StrategyPine Script · Mean reversion · 2h
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d
- A Combined RSI Strategy with Moving Average and MACDPine Script · Mean reversion · 1d