Strategy vault / Mean reversion
RSI Dynamic Range Reversal Quantitative Strategy with Volatility Optimization Model
This strategy is a dynamic range reversal trading system based on the RSI indicator, capturing market turning points through adjustable overbought/oversold zones combined with convergence/divergence sensitivity…
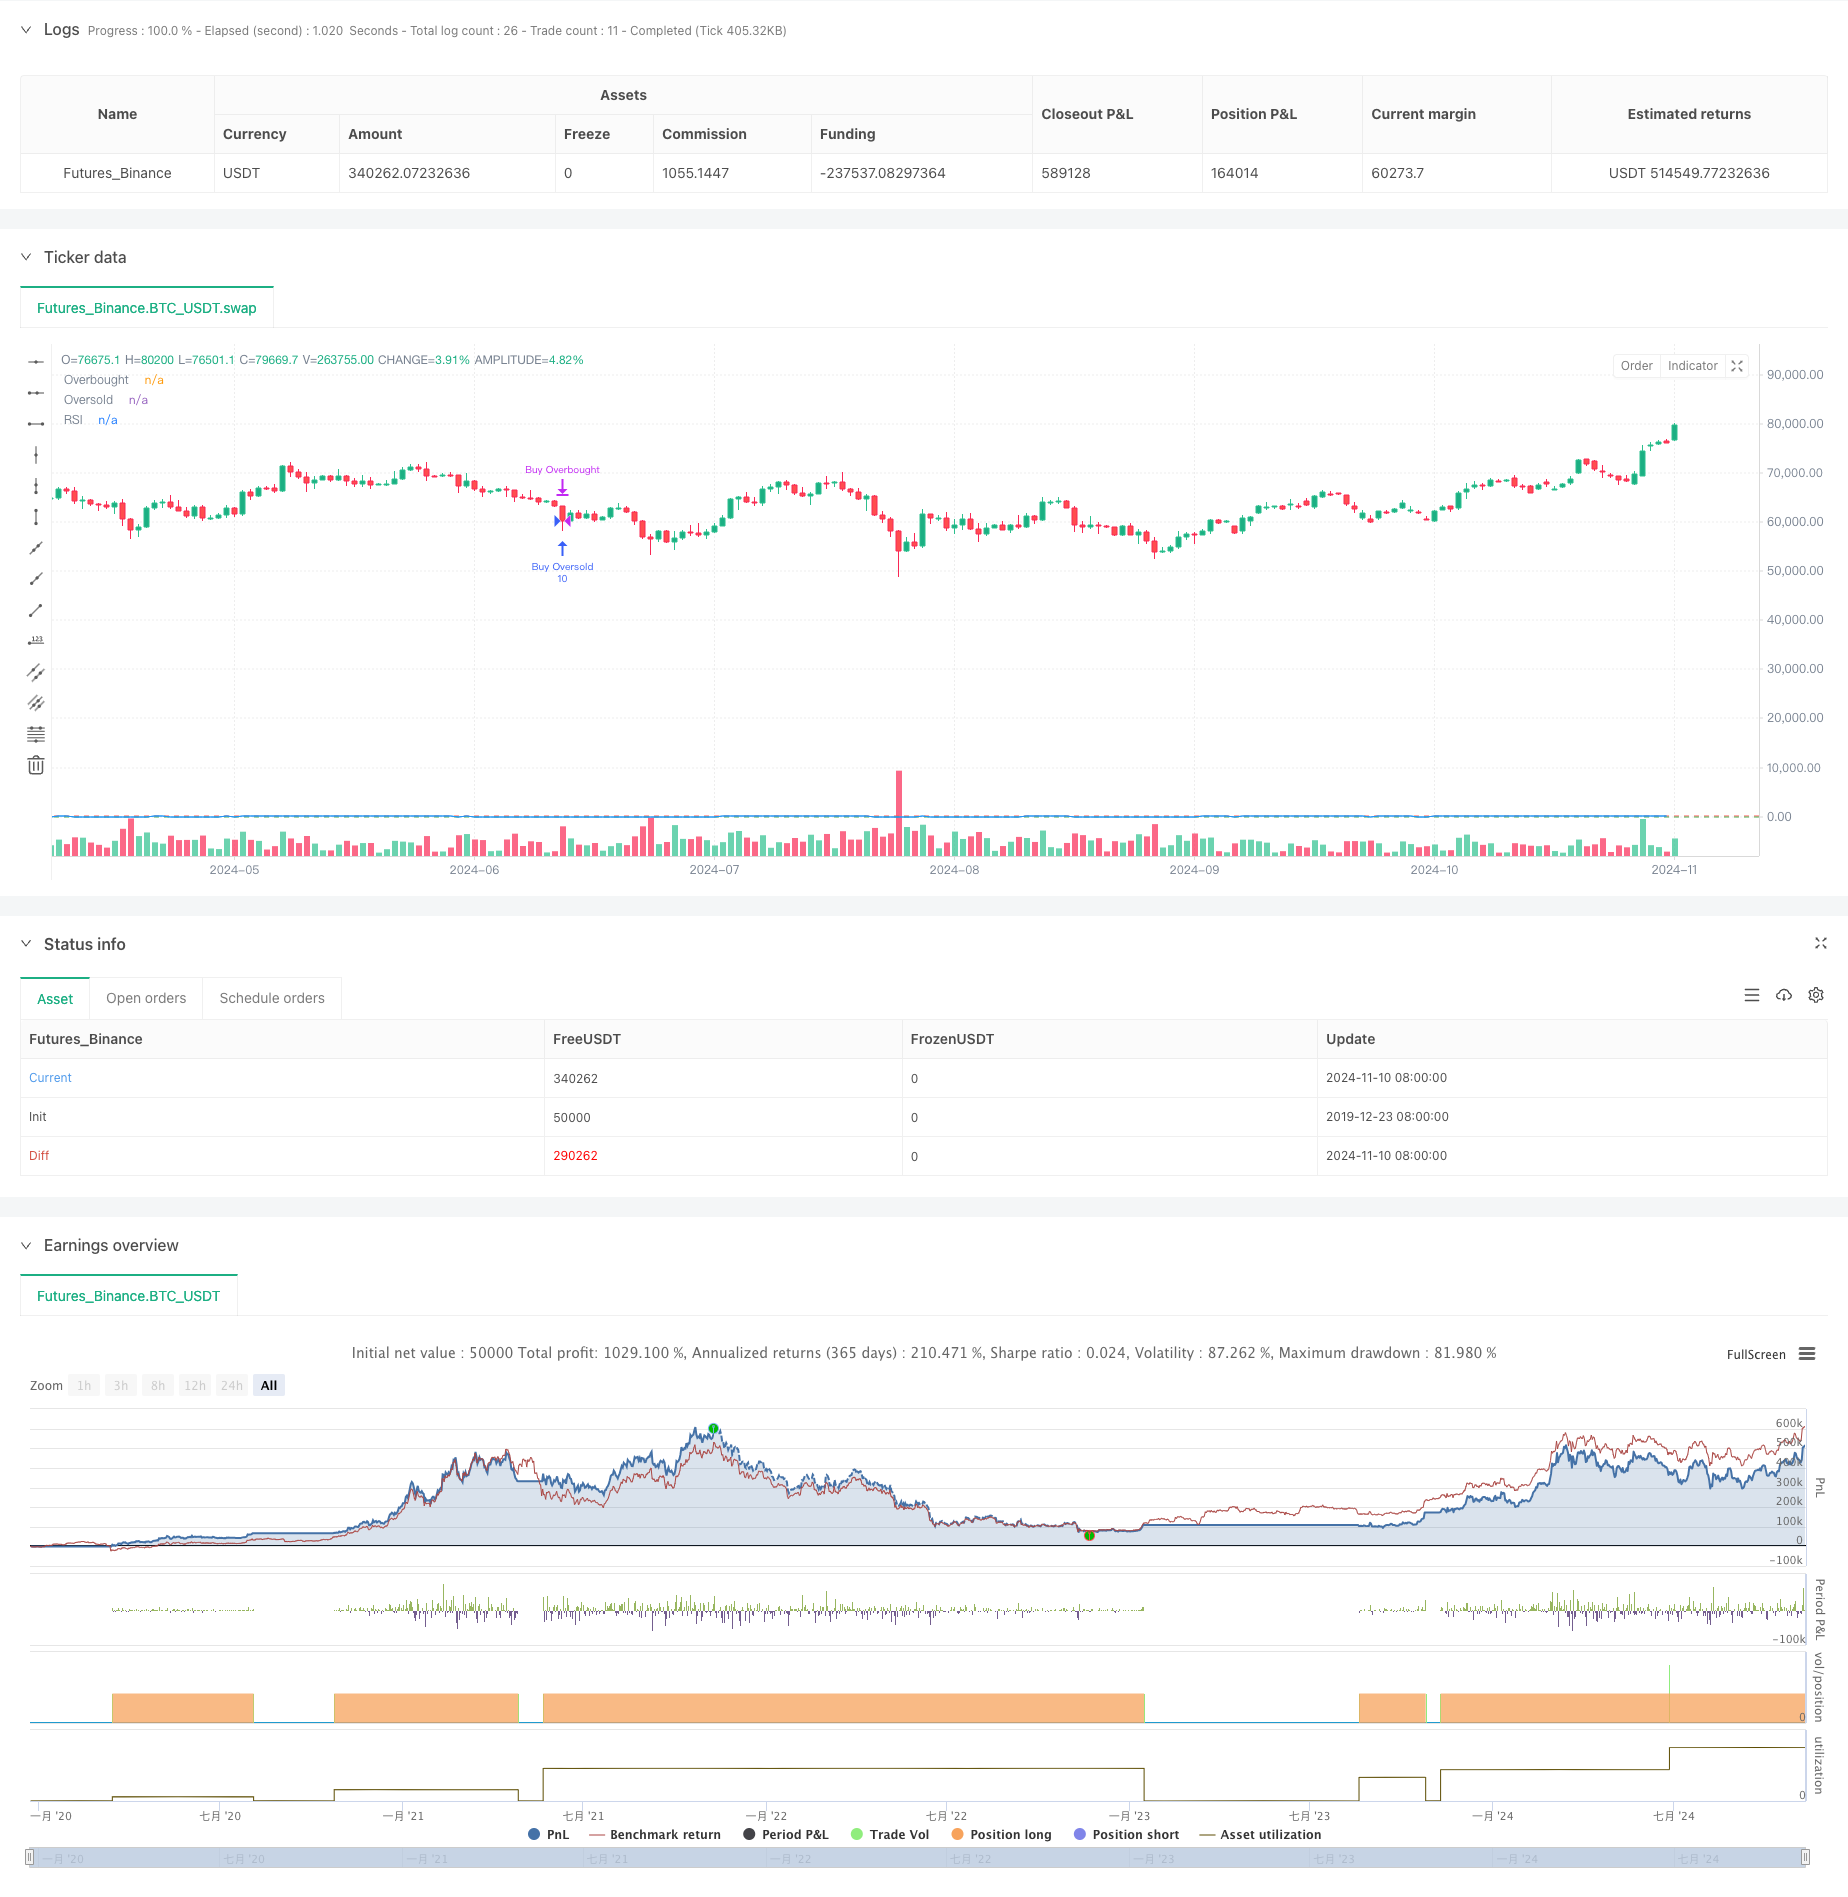
Overview
This strategy is a dynamic range reversal trading system based on the RSI indicator, capturing market turning points through adjustable overbought/oversold zones combined with convergence/divergence sensitivity parameters. The strategy employs a fixed number of contracts for trading and operates within a specific backtesting timeframe. The core of this model lies in identifying market overbought and oversold conditions through dynamic RSI changes and executing reversal trades at appropriate timing.
Strategy Principles
The strategy utilizes a 14-period RSI as its core indicator, setting 80 and 30 as overbought and oversold benchmark levels. By introducing a convergence/divergence sensitivity parameter (set at 3.0), it adds dynamic adjustment capability to the traditional RSI strategy. Long positions are established when RSI breaks above the overbought level and closed when RSI falls below the oversold level. Similarly, long positions are established when RSI falls below the oversold level and closed when RSI breaks above the overbought level. Each trade uses a fixed 10 contracts to ensure stability in capital utilization.
Strategy Advantages
- Dynamic Range Adjustment: Achieves dynamic adjustment of overbought/oversold zones through convergence/divergence parameters
- Clear Risk Control: Uses fixed contract quantity for trading, facilitating capital management
- Time Range Limitation: Avoids trading outside target periods through specific backtesting timeframe settings
- Signal Clarity: Uses RSI crossover signals as trading triggers, reducing false signals
- Visualization Support: Displays RSI trends and key levels through charts for monitoring and analysis
Strategy Risks
- Choppy Market Risk: May result in frequent trading in sideways markets, increasing transaction costs
- Trend Continuation Risk: Reversal signals might lead to premature position closure in strong trends
- Fixed Contract Risk: Doesn't consider market volatility changes, potentially over-risking in high volatility periods
- Parameter Sensitivity: Strategy performance heavily depends on RSI period and overbought/oversold level settings
- Time Dependence: Strategy effectiveness may be limited to specific backtesting periods
Strategy Optimization Directions
- Implement Volatility Adaptation: Suggest dynamically adjusting contract quantity based on market volatility
- Add Trend Filters: Combine other technical indicators to judge market trends, avoiding reversals in strong trends
- Optimize Signal Confirmation: Can add volume and other auxiliary indicators for signal confirmation
- Dynamic Time Periods: Automatically adjust RSI calculation periods based on different market phases
- Stop Loss Mechanism: Add dynamic stop losses to control single trade risk
Summary
This is a dynamic range reversal strategy based on the RSI indicator, achieving a relatively complete trading system through flexible parameter settings and clear trading rules. The strategy's main advantages lie in its dynamic adjustment capability and clear risk control, while attention needs to be paid to potential risks in choppy and trending markets. Through optimization measures such as volatility adjustment and trend filtering, the strategy has room for further improvement. Overall, this is a practical quantitative trading strategy framework suitable for in-depth research and practical verification.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-11 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("RSI Options Strategy", overlay=true)

// RSI settings
rsiLength = input(14, title="RSI Length")
rsiOverbought = input(80, title="Overbought Level")
rsiOversold = input(30, title="Oversold Level")
rsiSource = input(close, title="RSI Source")
rsi = ta.rsi(rsiSource, rsiLength)

// Convergence/Divergence Input
convergenceLevel = input(3.0, title="Convergence/Divergence Sensitivity")

// Order size (5 contracts)
contracts = 10

// Date Range for Backtesting
startDate = timestamp("2024-09-10 00:00")
endDate = timestamp("2024-11-09 23:59")

// Limit trades to the backtesting period
inDateRange = true

// RSI buy/sell conditions with convergence/divergence sensitivity
buySignalOverbought = ta.crossover(rsi, rsiOverbought - convergenceLevel)
sellSignalOversold = ta.crossunder(rsi, rsiOversold + convergenceLevel)
buySignalOversold = ta.crossunder(rsi, rsiOversold - convergenceLevel)
sellSignalOverbought = ta.crossover(rsi, rsiOverbought + convergenceLevel)

// Execute trades only within the specified date range
if (inDateRange)
    // Buy when RSI crosses above 80 (overbought)
    if (buySignalOverbought)
        strategy.entry("Buy Overbought", strategy.long, qty=contracts)

    // Sell when RSI crosses below 30 (oversold)
    if (sellSignalOversold)
        strategy.close("Buy Overbought")

    // Buy when RSI crosses below 30 (oversold)
    if (buySignalOversold)
        strategy.entry("Buy Oversold", strategy.long, qty=contracts)

    // Sell when RSI crosses above 80 (overbought)
    if (sellSignalOverbought)
        strategy.close("Buy Oversold")

// Plot the RSI for visualization
plot(rsi, color=color.blue, title="RSI")
hline(rsiOverbought, "Overbought", color=color.red)
hline(rsiOversold, "Oversold", color=color.green)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Dynamic-Range-Reversal-Quantitative-Strategy-with-Volatility-Optimization-Model.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive RSI Oscillator Dynamic Trading Strategy with Threshold OptimizationPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Fibonacci Retracement Trend Following and Reversal Trading StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d