Strategy vault / Mean reversion
RSI Dynamic Stop Loss Intelligent Trading Strategy
This strategy is a dynamic stop-loss trading system based on the RSI indicator, combining SMA and ATR indicators to optimize trading decisions. It employs a multi-level take-profit approach with pyramid-style…
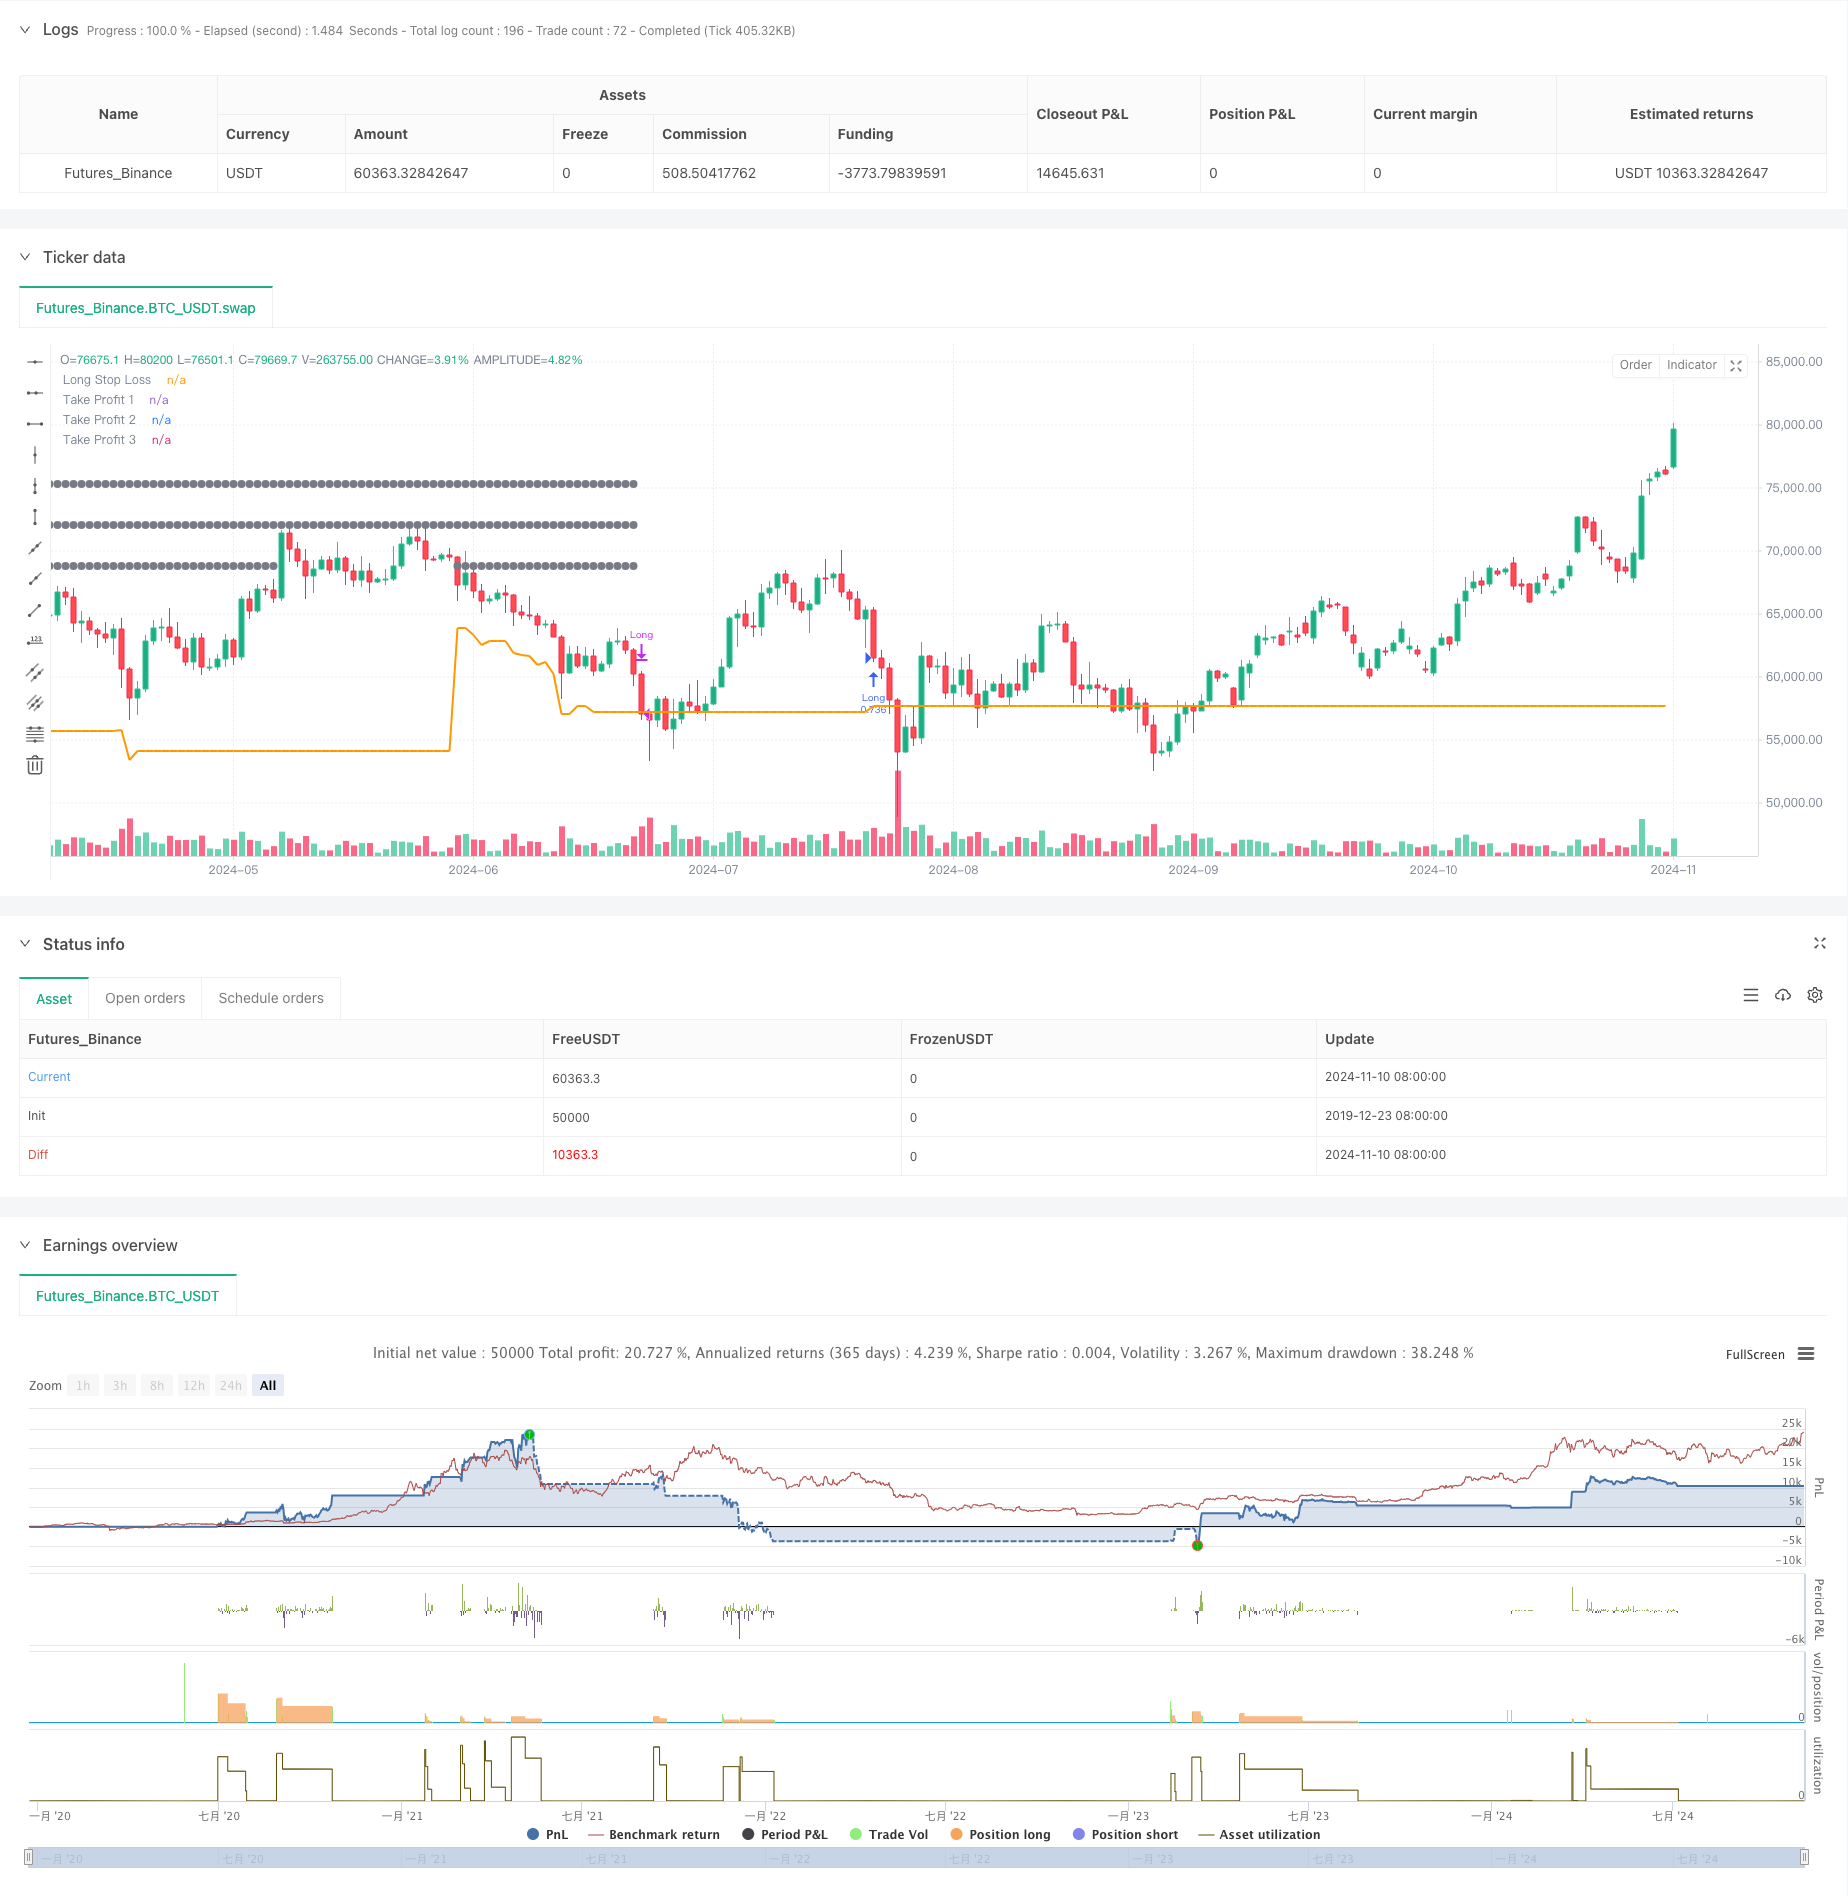
Overview
This strategy is a dynamic stop-loss trading system based on the RSI indicator, combining SMA and ATR indicators to optimize trading decisions. It employs a multi-level take-profit approach with pyramid-style position closing to maximize returns while using ATR dynamic stop-loss for risk control. The strategy features high adaptability and automatically adjusts trading parameters based on market volatility.
Strategy Principles
The strategy primarily uses RSI oversold conditions (RSI<30) as entry signals while requiring price to be above the 200-day moving average to ensure an uptrend. It implements three take-profit targets (5%, 10%, 15%) combined with ATR dynamic stop-loss. Specifically:
- Entry conditions: RSI below 30 and price above SMA200
- Position management: 75% capital per trade
- Stop-loss: Dynamic stop based on 1.5x ATR
- Take-profit: Three levels at 5%, 10%, 15%, closing 33%, 66%, and 100% respectively
Strategy Advantages
- Dynamic risk management: ATR adaptation to market volatility
- Staged profit-taking: Reduces emotional interference and improves profit probability
- Trend confirmation: Uses moving average to filter false signals
- Money management: Percentage-based position sizing for different account sizes
- Commission optimization: Considers trading costs for practical implementation
Strategy Risks
- Moving average lag may delay entries
- RSI oversold doesn't guarantee reversal
- Large position sizes may lead to significant drawdowns
- Frequent partial exits may increase trading costs These risks can be managed through parameter adjustments and additional filters.
Optimization Directions
- Add volume confirmation signals
- Incorporate trend strength indicators
- Optimize profit-taking ratios
- Add time-frame filters
- Consider volatility-adaptive position sizing
Summary
This strategy combines technical indicators with dynamic risk management to create a comprehensive trading system. Its strengths lie in adaptability and controlled risk, though parameter optimization based on market conditions is still necessary. The strategy is suitable for medium to long-term investors and serves as a solid foundation for systematic trading.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-11 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This work is licensed under a Attribution-NonCommercial-ShareAlike 4.0 International (CC BY-NC-SA/4.0) https://creativecommons.org/licenses/by-nc-sa/4.0/
// © wielkieef

//@version=5
strategy("Simple RSI stock Strategy [1D] ", overlay=true, pyramiding=1, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=75, calc_on_order_fills=false, slippage=0, commission_type=strategy.commission.percent, commission_value=0.03)

// Rsi
oversoldLevel = input(30, title="Oversold Level")
overboughtLevel = input(70, title="Overbought Level")
rsi = ta.rsi(close, 5)
rsi_overbought = rsi > overboughtLevel
rsi_oversold = rsi < oversoldLevel

// Sma 200
lenghtSMA = input(200, title = "SMA lenght")
sma200 = ta.sma(close, lenghtSMA)

// ATR stop-loss
atrLength = input.int(20, title="ATR Length")
atrMultiplier = input.float(1.5, title="ATR Multiplier")
atrValue = ta.atr(atrLength)
var float long_stop_level = na
var float short_stop_level = na
var float tp1_level = na
var float tp2_level = na
var float tp3_level = na

// Strategy entry
long = (rsi_oversold ) and close > sma200

// Take Profit levels
tp_1 = input.float(5.0, "TP 1", minval=0.1, step=0.1)
tp_2 = input.float(10.0, "TP 2", minval=0.2, step=0.1)
tp_3 = input.float(15.0, "TP 3", minval=0.3, step=0.1)

if long
    strategy.entry('Long', strategy.long)
    long_stop_level := close - atrMultiplier * atrValue
    tp1_level := strategy.position_avg_price * (1 + tp_1 / 100)
    tp2_level := strategy.position_avg_price * (1 + tp_2 / 100)
    tp3_level := strategy.position_avg_price * (1 + tp_3 / 100)

// basic SL - this code is from author RafaelZioni, modified by wielkieef
sl = input.float(25.0, 'Basic Stop Loss %', step=0.1)
per(procent) =>
    strategy.position_size != 0 ? math.round(procent / 100 * strategy.position_avg_price / syminfo.mintick) : float(na)

// ATR SL
if (strategy.position_size > 0 and (close <= long_stop_level))
    strategy.close("Long")
    tp1_level := na
    tp2_level := na
    tp3_level := na
plot(long_stop_level, color=color.orange, linewidth=2, title="Long Stop Loss")

// TP levels
if (strategy.position_size > 0)
    if (not na(tp1_level) and close >= tp1_level)
        tp1_level := na
    if (not na(tp2_level) and close >= tp2_level)
        tp2_level := na
    if (not na(tp3_level) and close >= tp3_level)
        tp3_level := na

plot(strategy.position_size > 0 and not na(tp1_level) ? tp1_level : na, color=color.gray, style=plot.style_circles , linewidth=1, title="Take Profit 1")
plot(strategy.position_size > 0 and not na(tp2_level) ? tp2_level : na, color=color.gray, style=plot.style_circles , linewidth=1, title="Take Profit 2")
plot(strategy.position_size > 0 and not na(tp3_level) ? tp3_level : na, color=color.gray, style=plot.style_circles , linewidth=1, title="Take Profit 3")

// Strategy exit points for Take Profits
strategy.exit('TP 1', from_entry="Long", qty_percent=33, profit=per(tp_1), loss=per(sl))
strategy.exit('TP 2', from_entry="Long", qty_percent=66, profit=per(tp_2), loss=per(sl))
strategy.exit('TP 3', from_entry="Long", qty_percent=100, profit=per(tp_3), loss=per(sl))

// by wielkieefPublished by ChaoZhang on the FMZ strategy square · last modified 2024-11-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Dynamic-Stop-Loss-Intelligent-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Strategy with Volume and Price Pullback Multiple Take ProfitPine Script · Mean reversion · 1h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Multi Indicator Reversal Point Capture Trading StrategyPine Script · Mean reversion · 1d
- Multi Timeframe Adaptive Mean Reversion with Volume Analysis StrategyPine Script · Mean reversion · 1h
- Dual Moving Average Crossover with Stochastic RSI Overbought Oversold Enhanced Trading StrategyPine Script · Mean reversion · 1d