Strategy vault / Mean reversion
RSI Gap Reversal Strategy
The GBP RSI Gap Reversal strategy is a short-term trading strategy that identifies trend reversal opportunities based on the RSI indicator. It enters trades after the RSI breaks out of overbought or oversold areas…
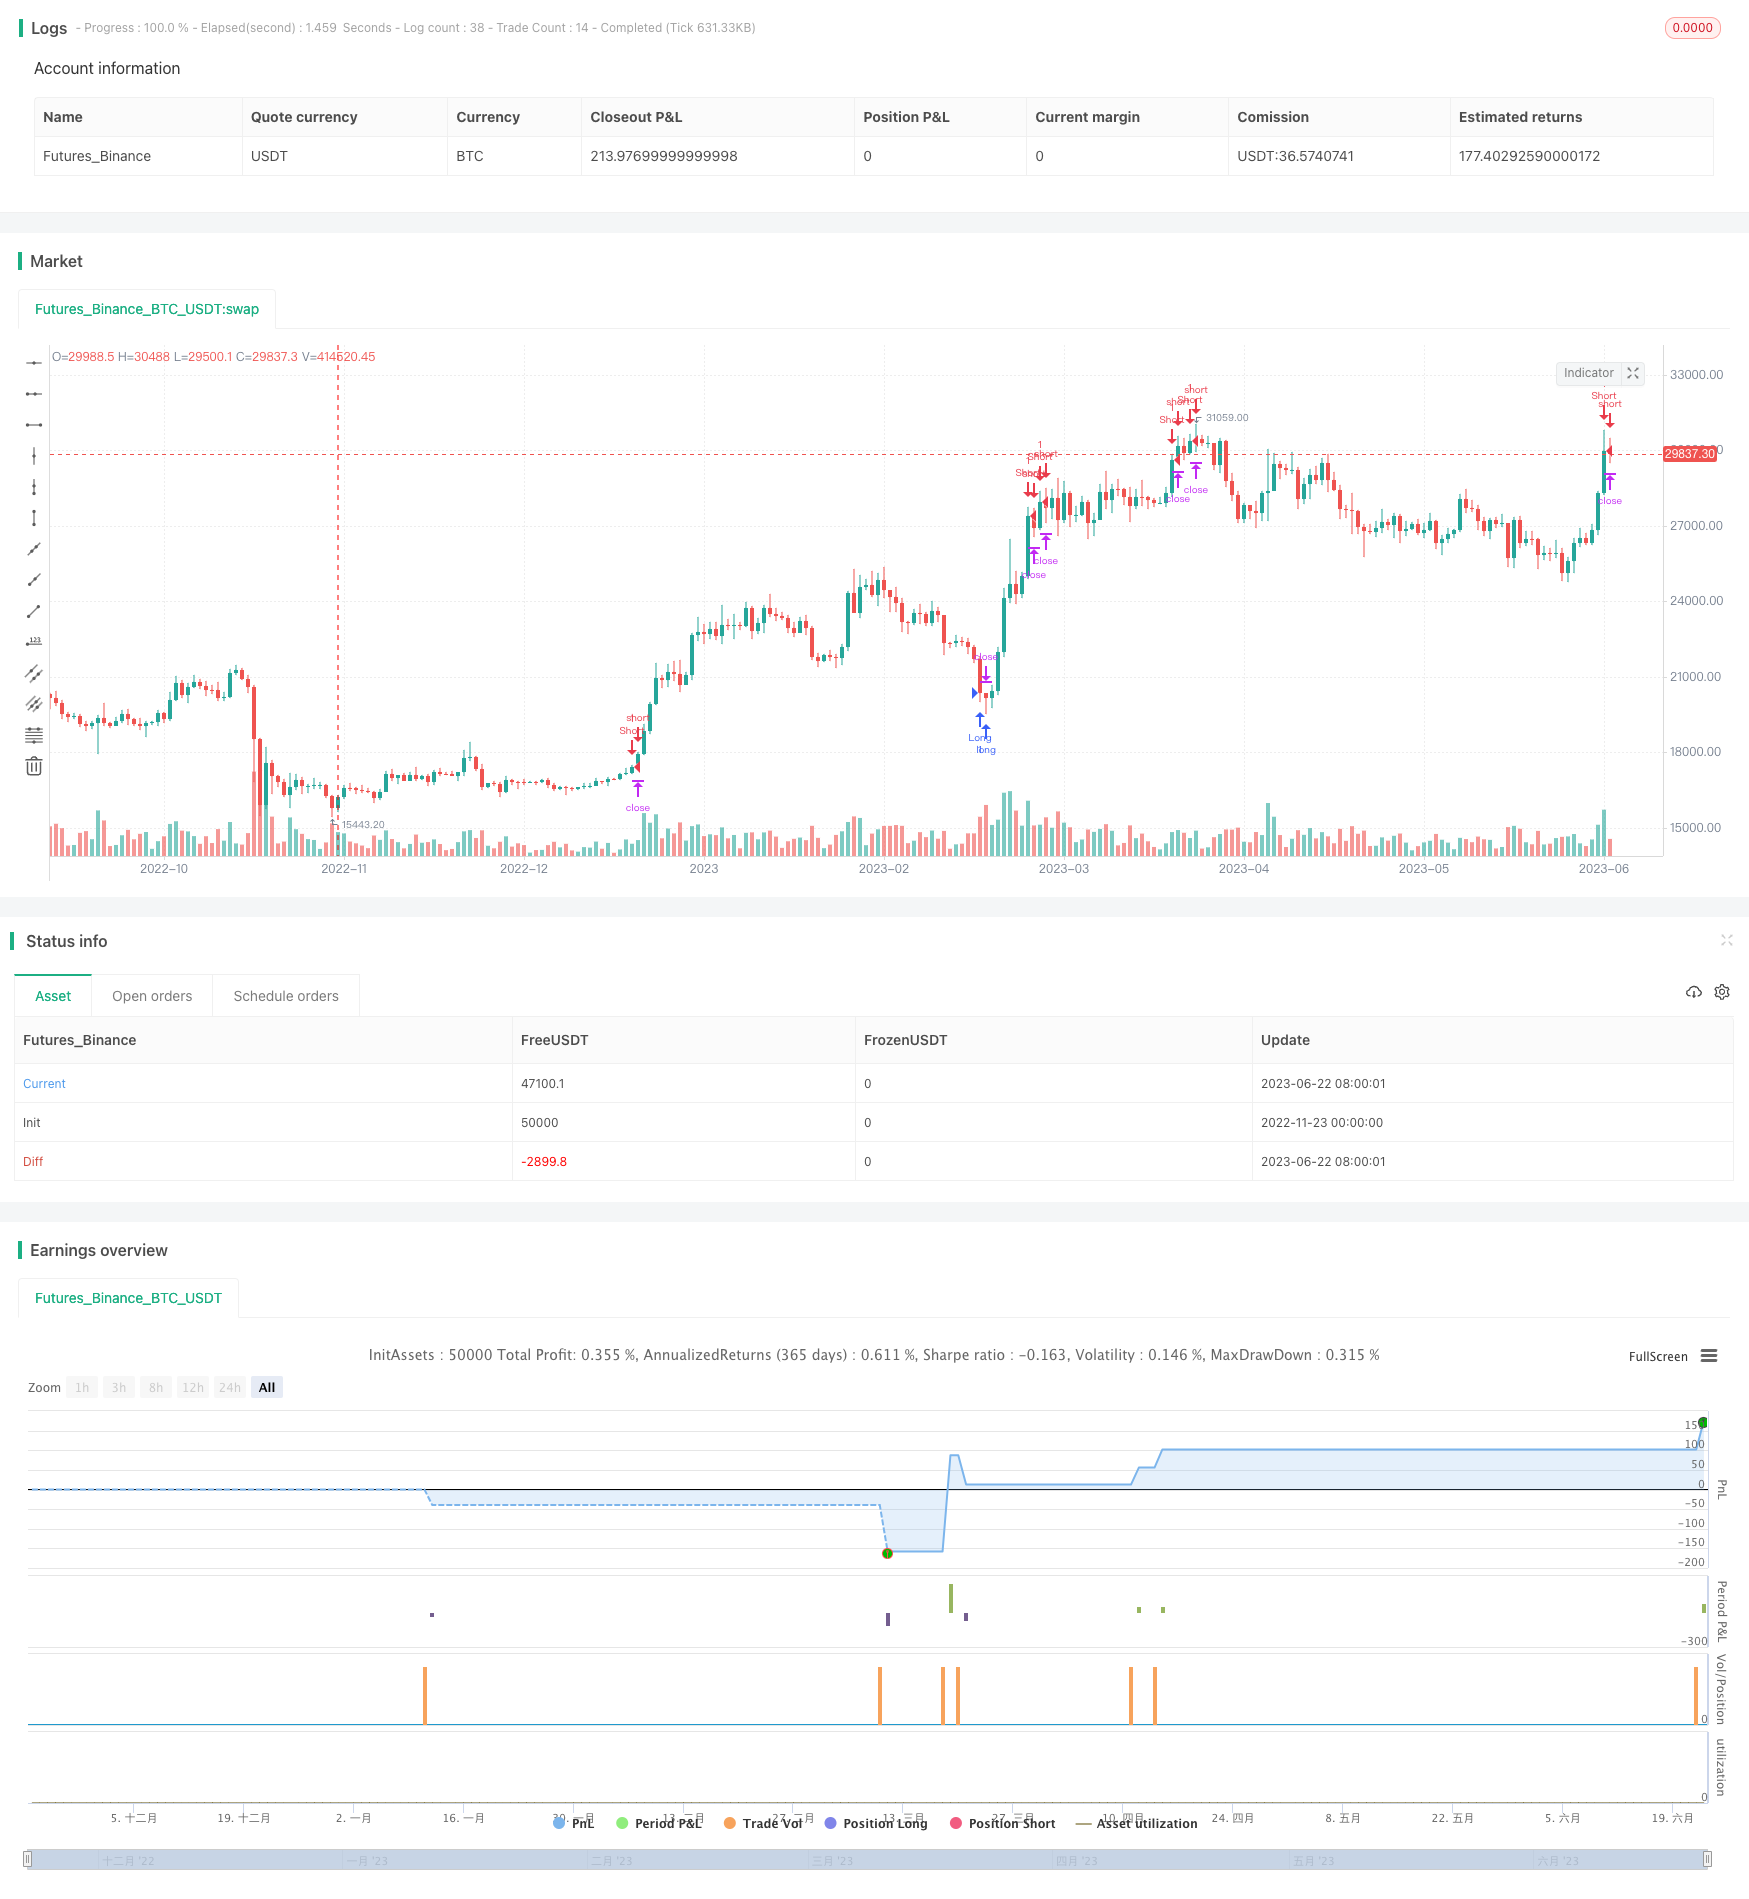
Overview
The GBP RSI Gap Reversal strategy is a short-term trading strategy that identifies trend reversal opportunities based on the RSI indicator. It enters trades after the RSI breaks out of overbought or oversold areas, forming a gap reversal pattern, to capture market turning points in a timely manner.
Principles
The core logic relies on RSI to identify overbought/oversold formations. The specific rules are:
Check if RSI breaks through 23 from oversold area, forming a bottom reversal. Go long if the gap reversal pattern is validated.
Set profit target when RSI crosses above 75. Set stop loss at 189 pips loss.
Check if RSI breaks through 75 from overbought area, forming a top reversal. Go short if the gap reversal pattern is validated.
Set profit target when RSI crosses below 23. Set stop loss at 152 pips loss.
Capturing reversals by identifying breakthrough reversal patterns is the key idea. Profit targets and stop losses lock in profits and prevent the risk of failed reversals.
Advantage Analysis
Captures market turning points by identifying RSI reversal patterns.
High success rate with gap reversal breakdowns/breakouts.
Effective risk control by setting profit targets and stop losses.
Simple and clear logic, easy to understand and implement.
Risk Analysis
Probability of false RSI reversal signals exists, price may reverse back after entry.
Improper profit target and stop loss setting may lead to premature exit or oversized losses.
Parameters like RSI period, overbought/oversold levels need continuous optimization.
Parameters vary significantly across symbols and timeframes.
Optimization Directions
Test different RSI parameters for better reversal identification.
Add filtering indicators like MACD to avoid false reversals.
Add volume filters for reversal breakdowns/breakouts.
Optimize across timeframes to find best fit.
Conclusion
The GBP RSI Gap Reversal Strategy captures reversals by identifying RSI gap signals. It has advantages like high success rate, risk control, and simplicity. But the risk of failed reversals still exists and further optimization is needed, along with additional filtering indicators. It suits short-term traders familiar with trading reversals, especially GBP traders.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 8 | length |
| v_input_2 | 23 | overSold |
| v_input_3 | 75 | overBought |
| v_input_4 | 35 | overSoldP |
| v_input_5 | 78 | overBoughtP |
| v_input_6 | 406 | ProfitL |
| v_input_7 | 189 | LossL |
| v_input_8 | 370 | ProfitS |
| v_input_9 | 152 | LossS |
| v_input_10 | 16 | BarssinceL |
| v_input_11 | 26 | BarssinceS |
Source Pine Script
/*backtest
start: 2022-11-23 00:00:00
end: 2023-06-23 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("GBP combine", overlay=true)
length = input( 8 )
overSold = input( 23 )
overBought = input( 75 )
price = close
overSoldP = input( 35 )
overBoughtP = input (78)
ProfitL = input(406)
LossL = input(189)
ProfitS = input(370)
LossS = input(152)
BarssinceL = input(16)
BarssinceS = input(26)

vrsi = rsi(price, length)

longCondition() => crossunder(vrsi, overSold)
closeLPLCondition() => crossover(vrsi, overBoughtP)
closeLCondition() => barssince(longCondition())>BarssinceL

shortCondition() => crossover (vrsi, overBought)
closeLPSCondition() => crossunder(vrsi, overSoldP)
closeSCondition() => barssince(shortCondition())>BarssinceS

if (longCondition())
    strategy.entry("Long", strategy.long)
    strategy.exit ("Exit", "Long", profit=ProfitL,loss=LossL)
strategy.close("Long", when = closeLPLCondition() or closeLCondition())

if (shortCondition())
    strategy.entry("Short", strategy.short)
    strategy.exit ("Exit", "Short", profit=ProfitS,loss=LossS)
strategy.close("Short", when = closeLPSCondition() or closeSCondition())


//plot(strategy.equity, title="equity", color=red, linewidth=2, style=areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Gap-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Multi EMA Trend Reversal Trading StrategyPine Script · Mean reversion · 1d
- Smoothed RSI Based Stock Trading StrategyPine Script · Mean reversion · 1h
- Enhanced Multi Indicator Trend Reversal Intelligence StrategyPine Script · Mean reversion · 1d
- Multi Dimensional Technical Indicator Cross Confirmation Buy Signal Optimization StrategyPine Script · Mean reversion · 1d
- Multi Signal Adaptive Trading StrategyPine Script · Mean reversion · 1d