Strategy vault / Mean reversion
RSI Indicator Long Short Separation Trading Strategy
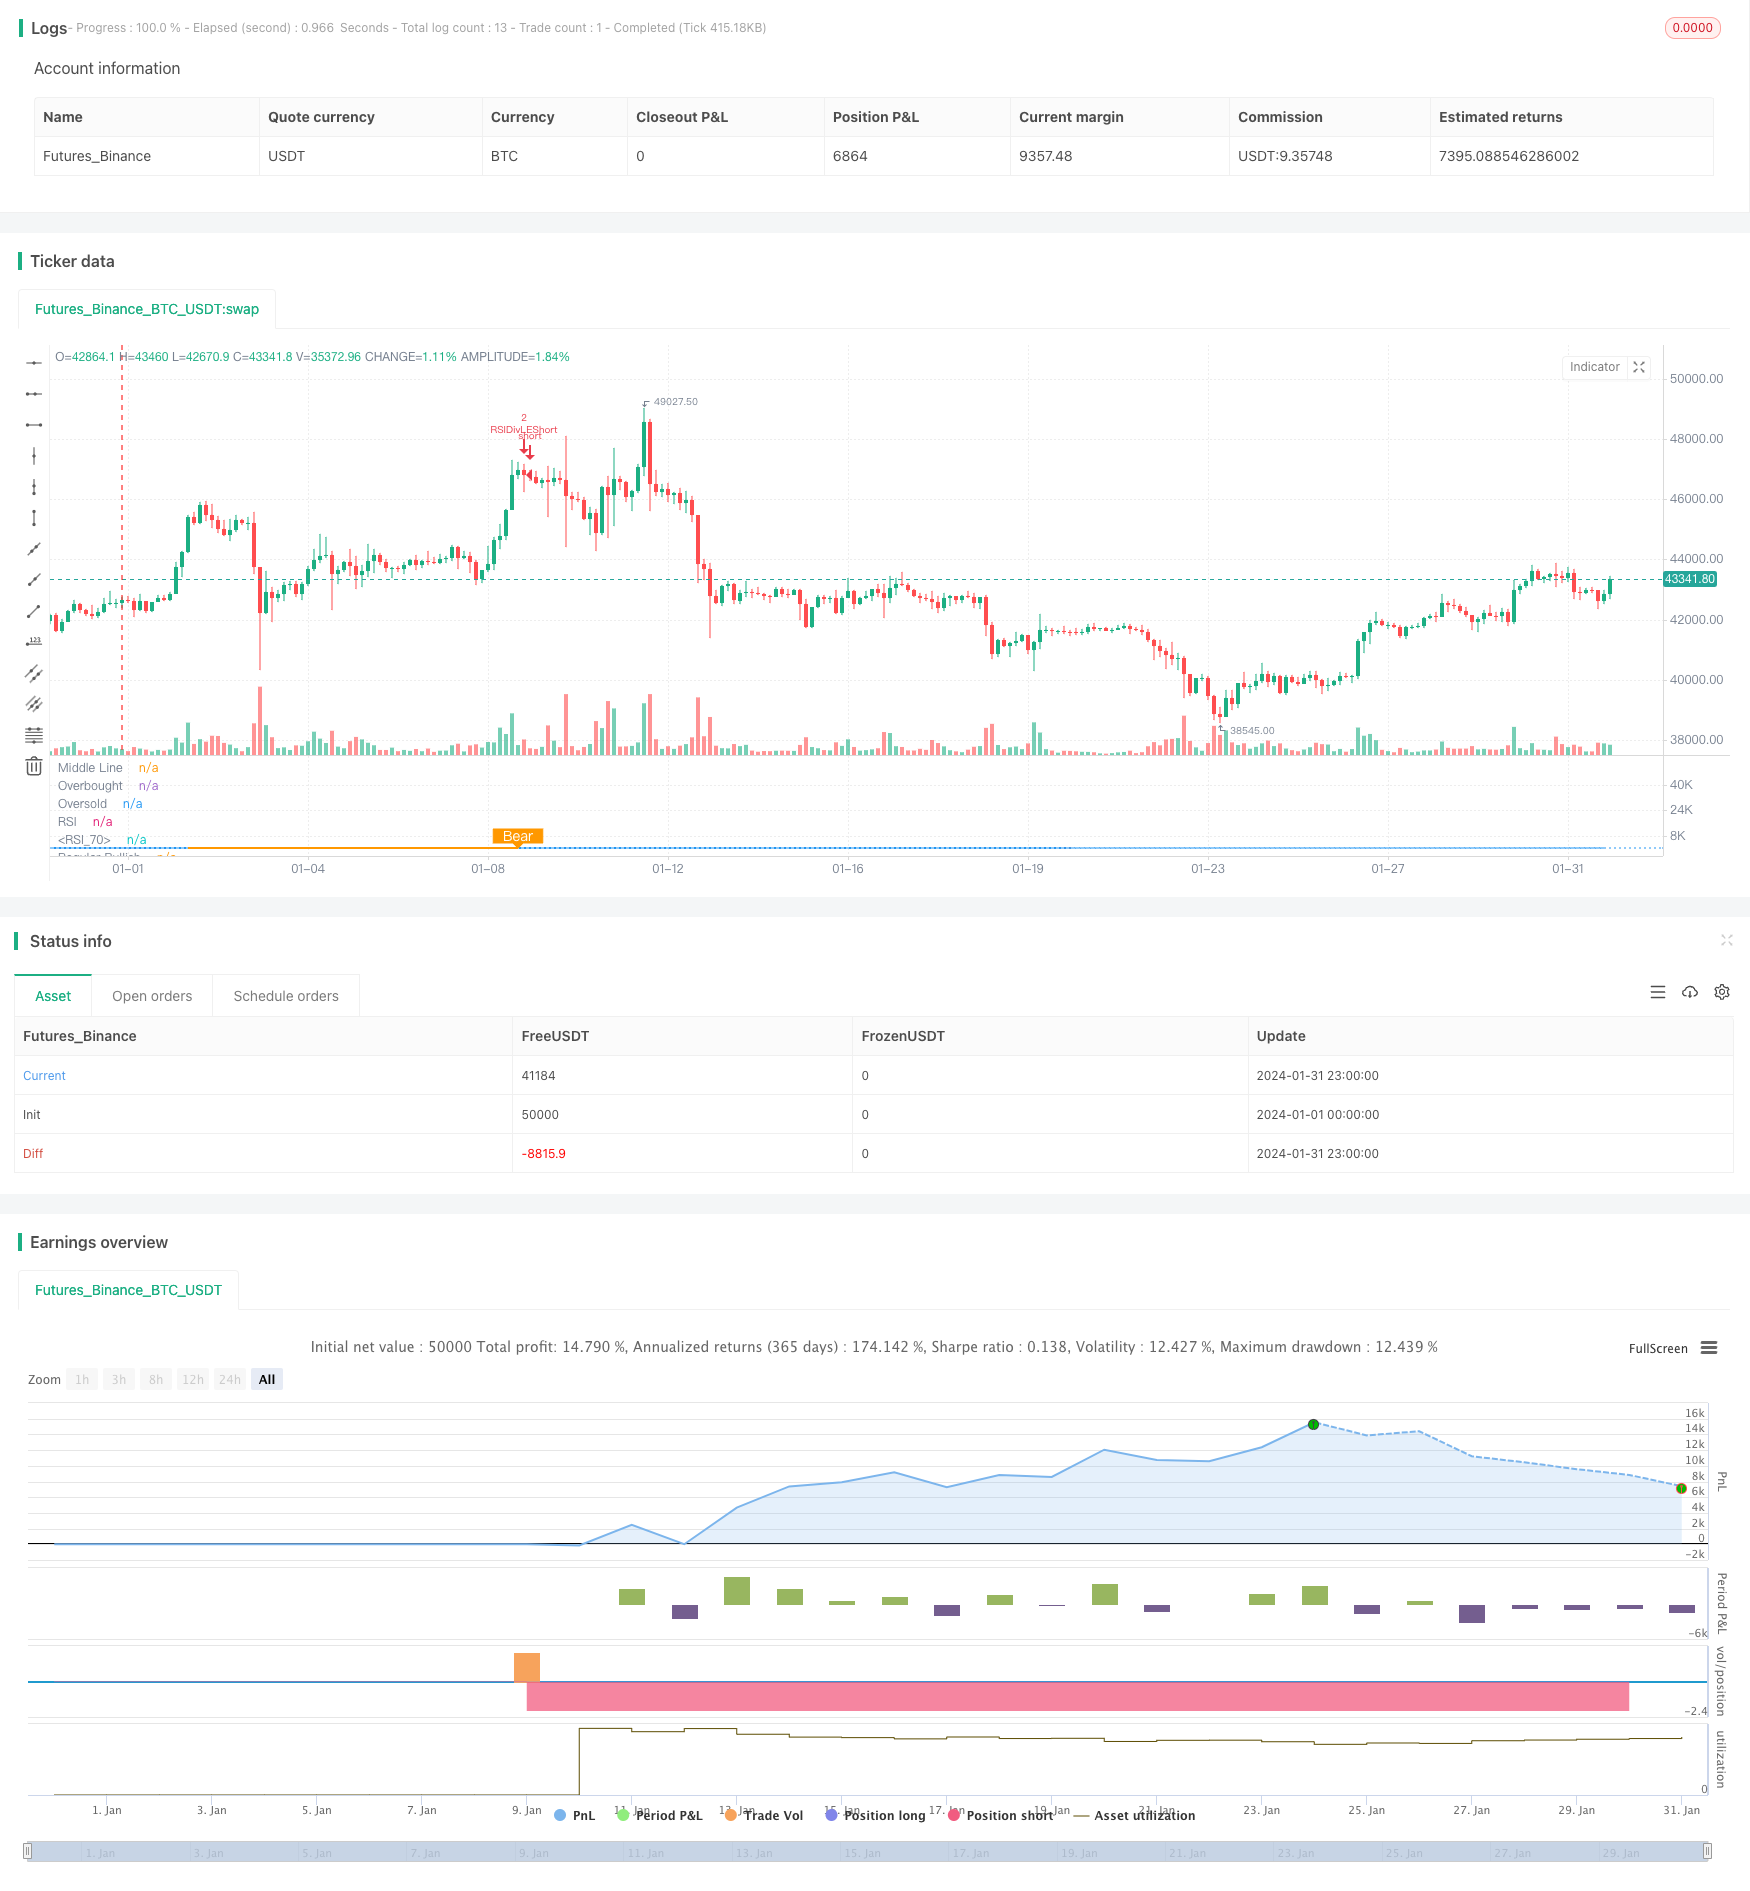
This strategy identifies long short separation phenomena through the RSI indicator to make trading decisions. The core idea is that when prices hit new lows but the RSI indicator hits new highs, a "bullish…
Overview
This strategy identifies long short separation phenomena through the RSI indicator to make trading decisions. The core idea is that when prices hit new lows but the RSI indicator hits new highs, a "bullish separation" signal is generated, indicating that the bottom has formed and going long. When prices hit new highs but the RSI indicator hits new lows, a "bearish separation" signal is generated, indicating that the top has formed and going short.
Strategy Principles
The strategy mainly uses the RSI indicator to identify the long short separation between prices and the RSI. The specific method is as follows:
- Use RSI indicator parameters of 13 and close prices as source data
- Define left lookback range for bullish separation as 14 days and right lookback range as 2 days
- Define left lookback range for bearish separation as 47 days and right lookback range as 1 day
- When prices hit lower lows but RSI hits higher lows, long separation condition is met to generate long signals
- When prices hit higher highs but RSI hits lower highs, short separation condition is met to generate short signals
By identifying the long short separation between prices and RSI, it can capture the inflection points of price trends in advance for trade decision making.
Advantages of the Strategy
The main advantages of this strategy are:
- Identifying price/RSI separation can judge trend inflections early to capture trading opportunities
- Use indicator analysis so less affected by emotions
- Use fixed lookback periods to identify separation, avoiding frequent parameter tuning
- Additional conditions like daily RSI reduce false signals
Risks and Solutions
There are still some risks:
RSI divergence does not necessarily mean immediate reversal, time lag may exist leading to stop loss risk. Solution is to allow wider stops to give time for divergence signal confirmation.
Prolonged separation also increases risk. Solution is to add longer-term daily or weekly RSI as filter conditions.
Small divergence may not confirm trend reversal, need to expand lookback periods to find more significant RSI divergence.
Optimization Directions
The strategy can be improved in the following aspects:
Optimize RSI parameters to find best parameter combinations
Try other technical indicators like MACD, KD to identify separation
Add oscillation filters to reduce false signals in choppy periods
Combine RSI from multiple timeframes to find best combination signals
Conclusion
The RSI long short separation trading strategy judges trend inflections by identifying divergence between price and RSI to generate trading signals. The strategy is simple and practical. Further improving parameters and adding filters can increase profitability. Overall an effective quantitative trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 13 | RSI Period |
| v_input_2_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | true | Short Lookback Right |
| v_input_4 | 47 | Short Lookback Left |
| v_input_5 | 2 | Long Lookback Right |
| v_input_6 | 14 | Long Lookback Left |
| v_input_7 | 400 | Max of Lookback Range |
| v_input_8 | true | Min of Lookback Range |
| v_input_9 | 75 | Take Profit at RSI Level |
| v_input_10 | 25 | Take Profit for Short at RSI Level |
| v_input_11 | 0 | Long Stop Loss Type: PERC | ATR | FIB | NONE |
| v_input_12 | 0 | Short Stop Loss Type: PERC | ATR | FIB | NONE |
| v_input_13 | 14 | Long Stop Loss Value |
| v_input_14 | 5 | Short Stop Loss Value |
| v_input_15 | true | Plot Bullish |
| v_input_16 | true | Plot Bearish |
| v_input_17 | 14 | ATR Length (for Trailing stop loss) |
| v_input_18 | 3.5 | ATR Multiplier (for Trailing stop loss) |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Nextep

//@version=4
strategy(title="RSI top&bottom destroy ", overlay=false, pyramiding=4, default_qty_value=2, default_qty_type=strategy.fixed, initial_capital=10000, currency=currency.USD)


// INPUT Settings --------------------------------------------------------------------------------------------------------------------------------------------------
len = input(title="RSI Period", minval=1, defval=13)
src = input(title="RSI Source", defval=close)


// defining the lookback range for shorts
lbRshort = input(title="Short Lookback Right", defval=1)
lbLshort = input(title="Short Lookback Left", defval=47)

// defining the lookback range for longs
lbRlong = input(title="Long Lookback Right", defval=2)
lbLlong = input(title="Long Lookback Left", defval=14)


rangeUpper = input(title="Max of Lookback Range", defval=400)
rangeLower = input(title="Min of Lookback Range", defval=1)

// take profit levels
takeProfitLongRSILevel = input(title="Take Profit at RSI Level", minval=0, defval=75)
takeProfitShortRSILevel = input(title="Take Profit for Short at RSI Level", minval=0, defval=25)


// Stop loss settings
longStopLossType = input("PERC", title="Long Stop Loss Type", options=['ATR','PERC', 'FIB', 'NONE'])
shortStopLossType = input("PERC", title="Short Stop Loss Type", options=['ATR','PERC', 'FIB', 'NONE'])
longStopLossValue = input(title="Long Stop Loss Value", defval=14, minval=0)
shortStopLossValue = input(title="Short Stop Loss Value", defval=5, minval=-10)


// PLOTTING THE CHARTS --------------------------------------------------------------------------------------------------------------------------------------------------
// Plotting the Divergence
plotBull = input(title="Plot Bullish", defval=true)
plotBear = input(title="Plot Bearish", defval=true)
bearColor = color.orange
bullColor = color.green
textColor = color.white
noneColor = color.new(color.white, 100)

// Adding the RSI oscillator
osc = rsi(src, len)
ma_len = 14 // Length for the moving average
rsi_ma = sma(osc, ma_len) // Calculate the moving average of RSI
plot(osc, title="RSI", linewidth=1, color=color.purple)
plot(rsi_ma, color=color.blue, title="RSI MA") // Plot the RSI MA

// Adding the lines of the RSI oscillator
plot(osc, title="RSI", linewidth=1, color=color.purple)
hline(50, title="Middle Line", linestyle=hline.style_dotted)
obLevel = hline(75, title="Overbought", linestyle=hline.style_dotted)
osLevel = hline(25, title="Oversold", linestyle=hline.style_dotted)
fill(obLevel, osLevel, title="Background", color=color.purple, transp=80)


atrLength = input(14, title="ATR Length (for Trailing stop loss)")
atrMultiplier = input(3.5, title="ATR Multiplier (for Trailing stop loss)")


// RSI PIVOTS --------------------------------------------------------------------------------------------------------------------------------------------------
// Define a condition for RSI pivot low
isFirstPivotLowlong = not na(pivotlow(osc, lbLlong, lbRlong))
// Define a condition for RSI pivot high
isFirstPivotHighlong = not na(pivothigh(osc, lbLlong, lbRlong))
// Define a condition for the first RSI value
firstPivotRSIValuelong = isFirstPivotLowlong ? osc[lbRlong] : na
// Define a condition for the second RSI value
secondPivotRSIValuelong = isFirstPivotLowlong ? valuewhen(isFirstPivotLowlong, osc[lbRlong], 1) : na


// Define a condition for RSI pivot low
isFirstPivotLowshort = not na(pivotlow(osc, lbLshort, lbRshort))
// Define a condition for RSI pivot high
isFirstPivotHighshort = not na(pivothigh(osc, lbLshort, lbRshort))
// Define a condition for the first RSI value
firstPivotRSIValueshort = isFirstPivotLowshort ? osc[lbRshort] : na
// Define a condition for the second RSI value
secondPivotRSIValueshort = isFirstPivotLowshort ? valuewhen(isFirstPivotLowshort, osc[lbRshort], 1) : na

_inRange(cond) =>
    bars = barssince(cond == true)
    rangeLower <= bars and bars <= rangeUpper


// ADDITIONAL ENTRY CRITERIA --------------------------------------------------------------------------------------------------------------------------------------------------
// RSI crosses RSI MA up by more than 2 points and subsequently down
rsiUpCross = crossover(osc, rsi_ma + 1)
rsiDownCross = crossunder(osc, rsi_ma - 1)

// Calculate the daily RSI
rsiDaily = security(syminfo.ticker, "D", rsi(src, 14))


// BULLISH CONDITIONS --------------------------------------------------------------------------------------------------------------------------------------------------

// LOWER LOW PRICE & HIGHER LOW OSC

// Price: Lower Low
priceLL = na(isFirstPivotLowlong[1]) ? false : (low[lbRlong] < valuewhen(isFirstPivotLowlong, low[lbRlong], 1))
// Osc: Higher Low
oscHL = na(isFirstPivotLowlong[1]) ? false : (osc[lbRlong] > valuewhen(isFirstPivotLowlong, osc[lbRlong], 1) and _inRange(isFirstPivotLowlong[1]))


// BULLISH PLOT
bullCond = plotBull and priceLL and oscHL and isFirstPivotLowlong
plot(
     isFirstPivotLowlong ? osc[lbRlong] : na,
     offset=-lbRlong,
     title="Regular Bullish",
     linewidth=2,
     color=(bullCond ? bullColor : noneColor),
     transp=0
     )

plotshape(
     bullCond ? osc[lbRlong] : na,
     offset=-lbRlong,
     title="Regular Bullish Label",
     text=" Bull ",
     style=shape.labelup,
     location=location.absolute,
     color=bullColor,
     textcolor=textColor,
     transp=0
     )


// BEARISH CONDITIONS --------------------------------------------------------------------------------------------------------------------------------------------------

// HIGHER HIGH PRICE & LOWER LOW OSC
// Osc: Lower High
oscLH = na(isFirstPivotHighshort[1]) ? false : (osc[lbRshort] < valuewhen(isFirstPivotHighshort, osc[lbRshort], 1) and _inRange(isFirstPivotHighshort[1]))
// Price: Higher High
priceHH = na(isFirstPivotHighshort[1]) ? false : (high[lbRshort] > valuewhen(isFirstPivotHighshort, high[lbRshort], 1))


// BEARISH PLOT
bearCond = plotBear and priceHH and oscLH and isFirstPivotHighshort

plot(
     isFirstPivotHighshort ? osc[lbRshort] : na,
     offset=-lbRshort,
     title="Regular Bearish",
     linewidth=2,
     color=(bearCond ? bearColor : noneColor),
     transp=0
     )

plotshape(
     bearCond ? osc[lbRshort] : na,
     offset=-lbRshort,
     title="Regular Bearish Label",
     text=" Bear ",
     style=shape.labeldown,
     location=location.absolute,
     color=bearColor,
     textcolor=textColor,
     transp=0
     )


// ENTRY CONDITIONS --------------------------------------------------------------------------------------------------------------------------------------------------

longCondition = false
shortCondition = false

// Entry Conditions
longCondition := bullCond
shortCondition := bearCond

// Conditions to prevent entering trades based on daily RSI
longCondition := longCondition and rsiDaily >= 23
shortCondition := shortCondition and rsiDaily <= 80


// STOPLOSS CONDITIONS --------------------------------------------------------------------------------------------------------------------------------------------------
// Stoploss Conditions
long_sl_val =
      longStopLossType == "ATR" ? longStopLossValue * atr(atrLength)
      : longStopLossType == "PERC" ? close * longStopLossValue / 100 : 0.00
long_trailing_sl = 0.0
long_trailing_sl := strategy.position_size >= 1 ? max(low - long_sl_val, nz(long_trailing_sl[1])) : na

// Calculate Trailing Stop Loss for Short Entries
short_sl_val =
      shortStopLossType == "ATR" ? 1 - shortStopLossValue * atr(atrLength)
      : shortStopLossType == "PERC" ? close * (shortStopLossValue / 100) : 0.00 //PERC = shortstoplossvalue = -21300 * 5 / 100 = -1065
short_trailing_sl = 0.0
short_trailing_sl := strategy.position_size <= -1 ? max(high + short_sl_val, nz(short_trailing_sl[1])) : na


// RSI STOP CONDITION

rsiStopShort = (strategy.position_avg_price != 0.0 and close <= strategy.position_avg_price * 0.90) or (strategy.position_avg_price != 0.0 and rsi(src, 14) >= 75)

rsiStopLong = (strategy.position_avg_price != 0.0 and close >= strategy.position_avg_price * 1.10) or (strategy.position_avg_price != 0.0 and rsi(src, 14) <= 25)


// LONG CONDITIONS --------------------------------------------------------------------------------------------------------------------------------------------------
strategy.entry(id="RSIDivLELong", long=true, when=longCondition)

strategy.entry(id="RSIDivLEShort", long=false, when=shortCondition)


// Close Conditions
shortCloseCondition = bullCond // or cross(osc, takeProfitShortRSILevel)
strategy.close(id="RSIDivLEShort", comment="Close All="+tostring(-close + strategy.position_avg_price, "####.##"), when=abs(strategy.position_size) <= -1 and shortStopLossType == "NONE" and shortCloseCondition )
strategy.close(id="RSIDivLEShort", comment="TSL="+tostring(-close + strategy.position_avg_price, "####.##"), when=abs(strategy.position_size) >= -1 and ((shortStopLossType == "PERC" or shortStopLossType == "ATR") and cross(short_trailing_sl,high))) // or rsiStopShort)// or rsiStopShort)


longCloseCondition = bearCond
strategy.close(id="RSIDivLELong", comment="Close All="+tostring(close - strategy.position_avg_price, "####.##"), when=abs(strategy.position_size) >= 1 and longStopLossType == "NONE" and longCloseCondition)
strategy.close(id="RSIDivLELong", comment="TSL="+tostring(close - strategy.position_avg_price, "####.##"), when=abs(strategy.position_size) >= 1 and ((longStopLossType == "PERC" or longStopLossType == "ATR") and cross(long_trailing_sl,low)))  //or rsiStopLong
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Indicator-Long-Short-Separation-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Timeframe Gold Reversal Tracking StrategyPine Script · Mean reversion · 2h
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d
- Mean Reversion Trading Strategy Based on Bollinger Bands and Golden RatioPine Script · Mean reversion · 1h
- Quant Bitcoin Trading Strategy Combining MACD RSI and FIBPine Script · Mean reversion · 10m
- Advanced Fibonacci Retracement Trend Following and Reversal Trading StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d