Strategy vault / Mean reversion
RSI Long Short Balance Trading Strategy
This strategy uses a combination of RSI indicators across different timeframes to determine if the current market is overbought or oversold, and combines the relationship between price and moving average to generate…
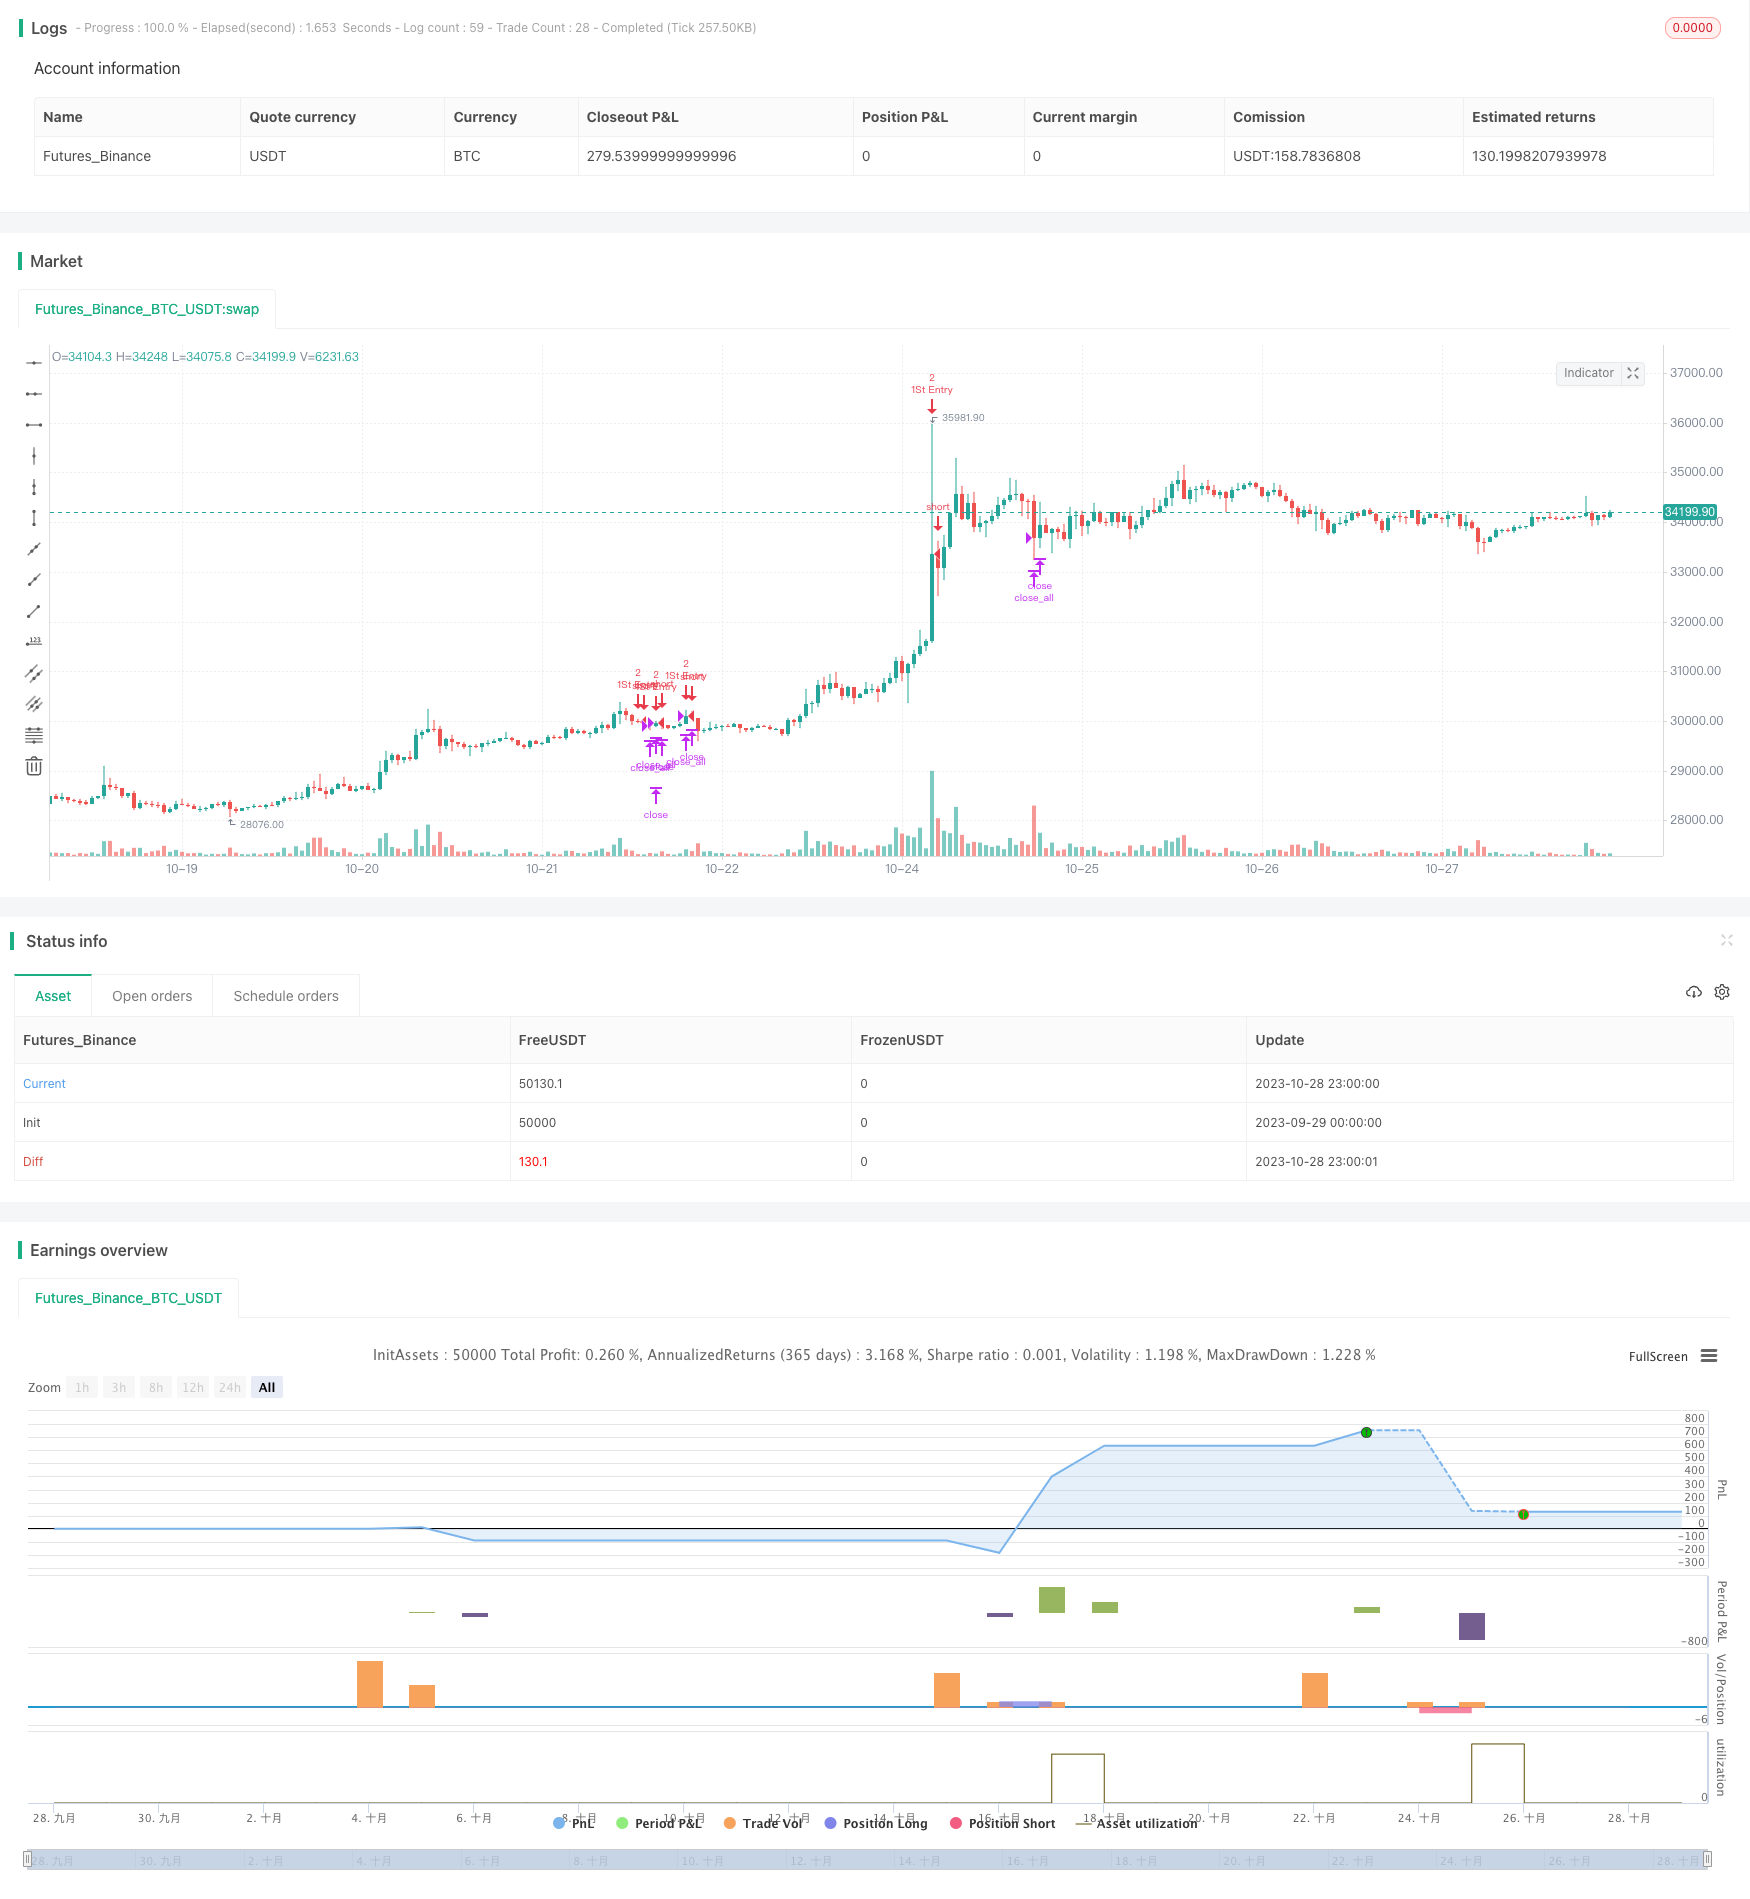
Overview
This strategy uses a combination of RSI indicators across different timeframes to determine if the current market is overbought or oversold, and combines the relationship between price and moving average to generate buy and sell signals. The goal is to buy on dips and sell on rallies to profit during consolidation.
Strategy Logic
Calculate the RSI values of the 5-minute, 15-minute, and 1-hour timeframes. When the 5-minute, 15-minute and 1-hour RSI are all below 25 at the same time, it is judged as an oversold condition and generates a buy signal. When the 5-minute, 15-minute and 1-hour RSI are all above 75 at the same time, it is judged as an overbought condition and generates a sell signal.
Breaking the 21-day moving average also acts as a trading signal. If the price is below the moving average, a buy signal is generated. If the price is above the moving average, a sell signal is generated.
Based on the current position, the initial trade size and pyramiding rules are set: 2 contracts for the first entry, and then adding 1 contract each time until the position reaches 2 contracts.
The stop loss is triggered when the loss reaches 3%. Take profit when the profit reaches 1%.
Advantages
Using RSI indicators across multiple timeframes to determine overbought and oversold conditions improves signal reliability.
Combining moving average generates additional trading signals and expands trading opportunities.
Setting position sizing control and profit/loss ratio for stop loss and take profit manages risks.
Scaling in with fixed quantity expands profit potential.
Risks
RSI divergence risk. Price may continue to trend for a period after RSI reaches overbought or oversold threshold before reversing. Blindly following RSI signal can lead to losses.
Moving average trading signal may be misleading. Moving average fails to track price change timely during huge price swings.
Incorrect position sizing and profit/loss ratio settings lead to improper risk control.
Pyramiding conditions need to be set reasonably to avoid magnifying losses.
Optimization Directions
Adjust RSI parameters and test different period combinations to find more reliable overbought/oversold signals.
Test different moving averages as auxiliary trading signals, or other technical indicators.
Optimize position sizing and stop loss/take profit rules to build more scientific risk control mechanisms.
Optimize pyramiding conditions to prevent magnifying losses. Consider exponential scaling instead of fixed quantity scaling.
Summary
This strategy uses RSI across multiple timeframes to determine trend potential and achieve higher win rate. Additional signals are generated with moving averages to expand trading opportunities. Risk is managed through position sizing, stop loss/take profit, and fixed quantity pyramiding. Overall, this strategy combines trend and mean reversion indicators, incorporates both trend following and bottom-picking logic, and is effective during consolidation. Further testing and optimization is needed to build more robust risk control for more consistent performance.
Source Pine Script
/*backtest
start: 2023-09-29 00:00:00
end: 2023-10-29 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("5M_RSI_Strategy", overlay=true, pyramiding = 1)
len =14
Initial_Trade_Size = 2
up = rma(max(change(close), 0), len)
down = rma(-min(change(close), 0), len)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
RSI_1h = request.security(syminfo.tickerid, "60", rsi)
RSI_3h = request.security(syminfo.tickerid, "180", rsi)
RSI_15m = request.security(syminfo.tickerid, "15", rsi)
RSI_5m = request.security(syminfo.tickerid, "5", rsi)
RSI_1m = request.security(syminfo.tickerid, "1", rsi)
ema21_5 = ema(request.security(syminfo.tickerid, "5", close), 21)
ema21_15 = ema(request.security(syminfo.tickerid, "15", close), 21)
//(RSI_3h<=25) and  (RSI_1h<=25) and (RSI_15m<=25) and
Positive = ((RSI_5m<=25) and (RSI_15m<=25) and (RSI_1h<=25))?true:false
//alertcondition(Positive, title='POS', message='POS')
//plotshape(Positive, style=shape.triangleup,location=location.belowbar, color=green,size =size.tiny)
Negative = (( RSI_5m>=75) and ( RSI_15m>=75) and ( RSI_1h>=75))?true:false
//alertcondition(Negative, title='NEG', message='NEG')
//plotshape(Negative, style=shape.triangledown,location=location.abovebar, color=red,size=size.tiny)          Positive and   Negative and

lastordersize = abs(strategy.position_size)>=Initial_Trade_Size?abs(strategy.position_size):Initial_Trade_Size
//lastordersize =1
// and ((ema21_15-low)/ema21_15) > 0.077
//Adding to position rules
if (abs(strategy.position_size) >= Initial_Trade_Size and (abs(close - strategy.position_avg_price)/abs(strategy.position_avg_price)>0.03))
    if(strategy.position_avg_price > close and strategy.position_size > 0)
        strategy.entry("Add", strategy.long , qty = lastordersize , when = true)
    if(strategy.position_avg_price < close and strategy.position_size < 0)
        strategy.entry("Add", strategy.short, qty = lastordersize , when = true)
if (strategy.position_size == 0)
    if (Positive or ((ema21_5-low)/ema21_5) > 0.07)
        strategy.entry("1St Entry", strategy.long , qty = lastordersize , when = true)
    // and ((high-ema21_15)/ema21_15) > 0.077
    if (Negative or ((high-ema21_5)/ema21_5) > 0.07)
        strategy.entry("1St Entry", strategy.short, qty = lastordersize , when = true)
//lastordersize := lastordersize * 2
//or (strategy.openprofit / abs(strategy.position_size * close))>=0.01
if(cross(ema21_5, high) or cross(ema21_5, low))
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-30. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Long-Short-Balance-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Chaikin Oscillator StrategyPine Script · Mean reversion · 3h