RSI Momentum Long Short Strategy
The RSI Momentum Long Short strategy is a typical momentum strategy based on the Larry Connors RSI indicator, using the overbought and oversold signals from RSI to determine entries and exits. The key is to identify…
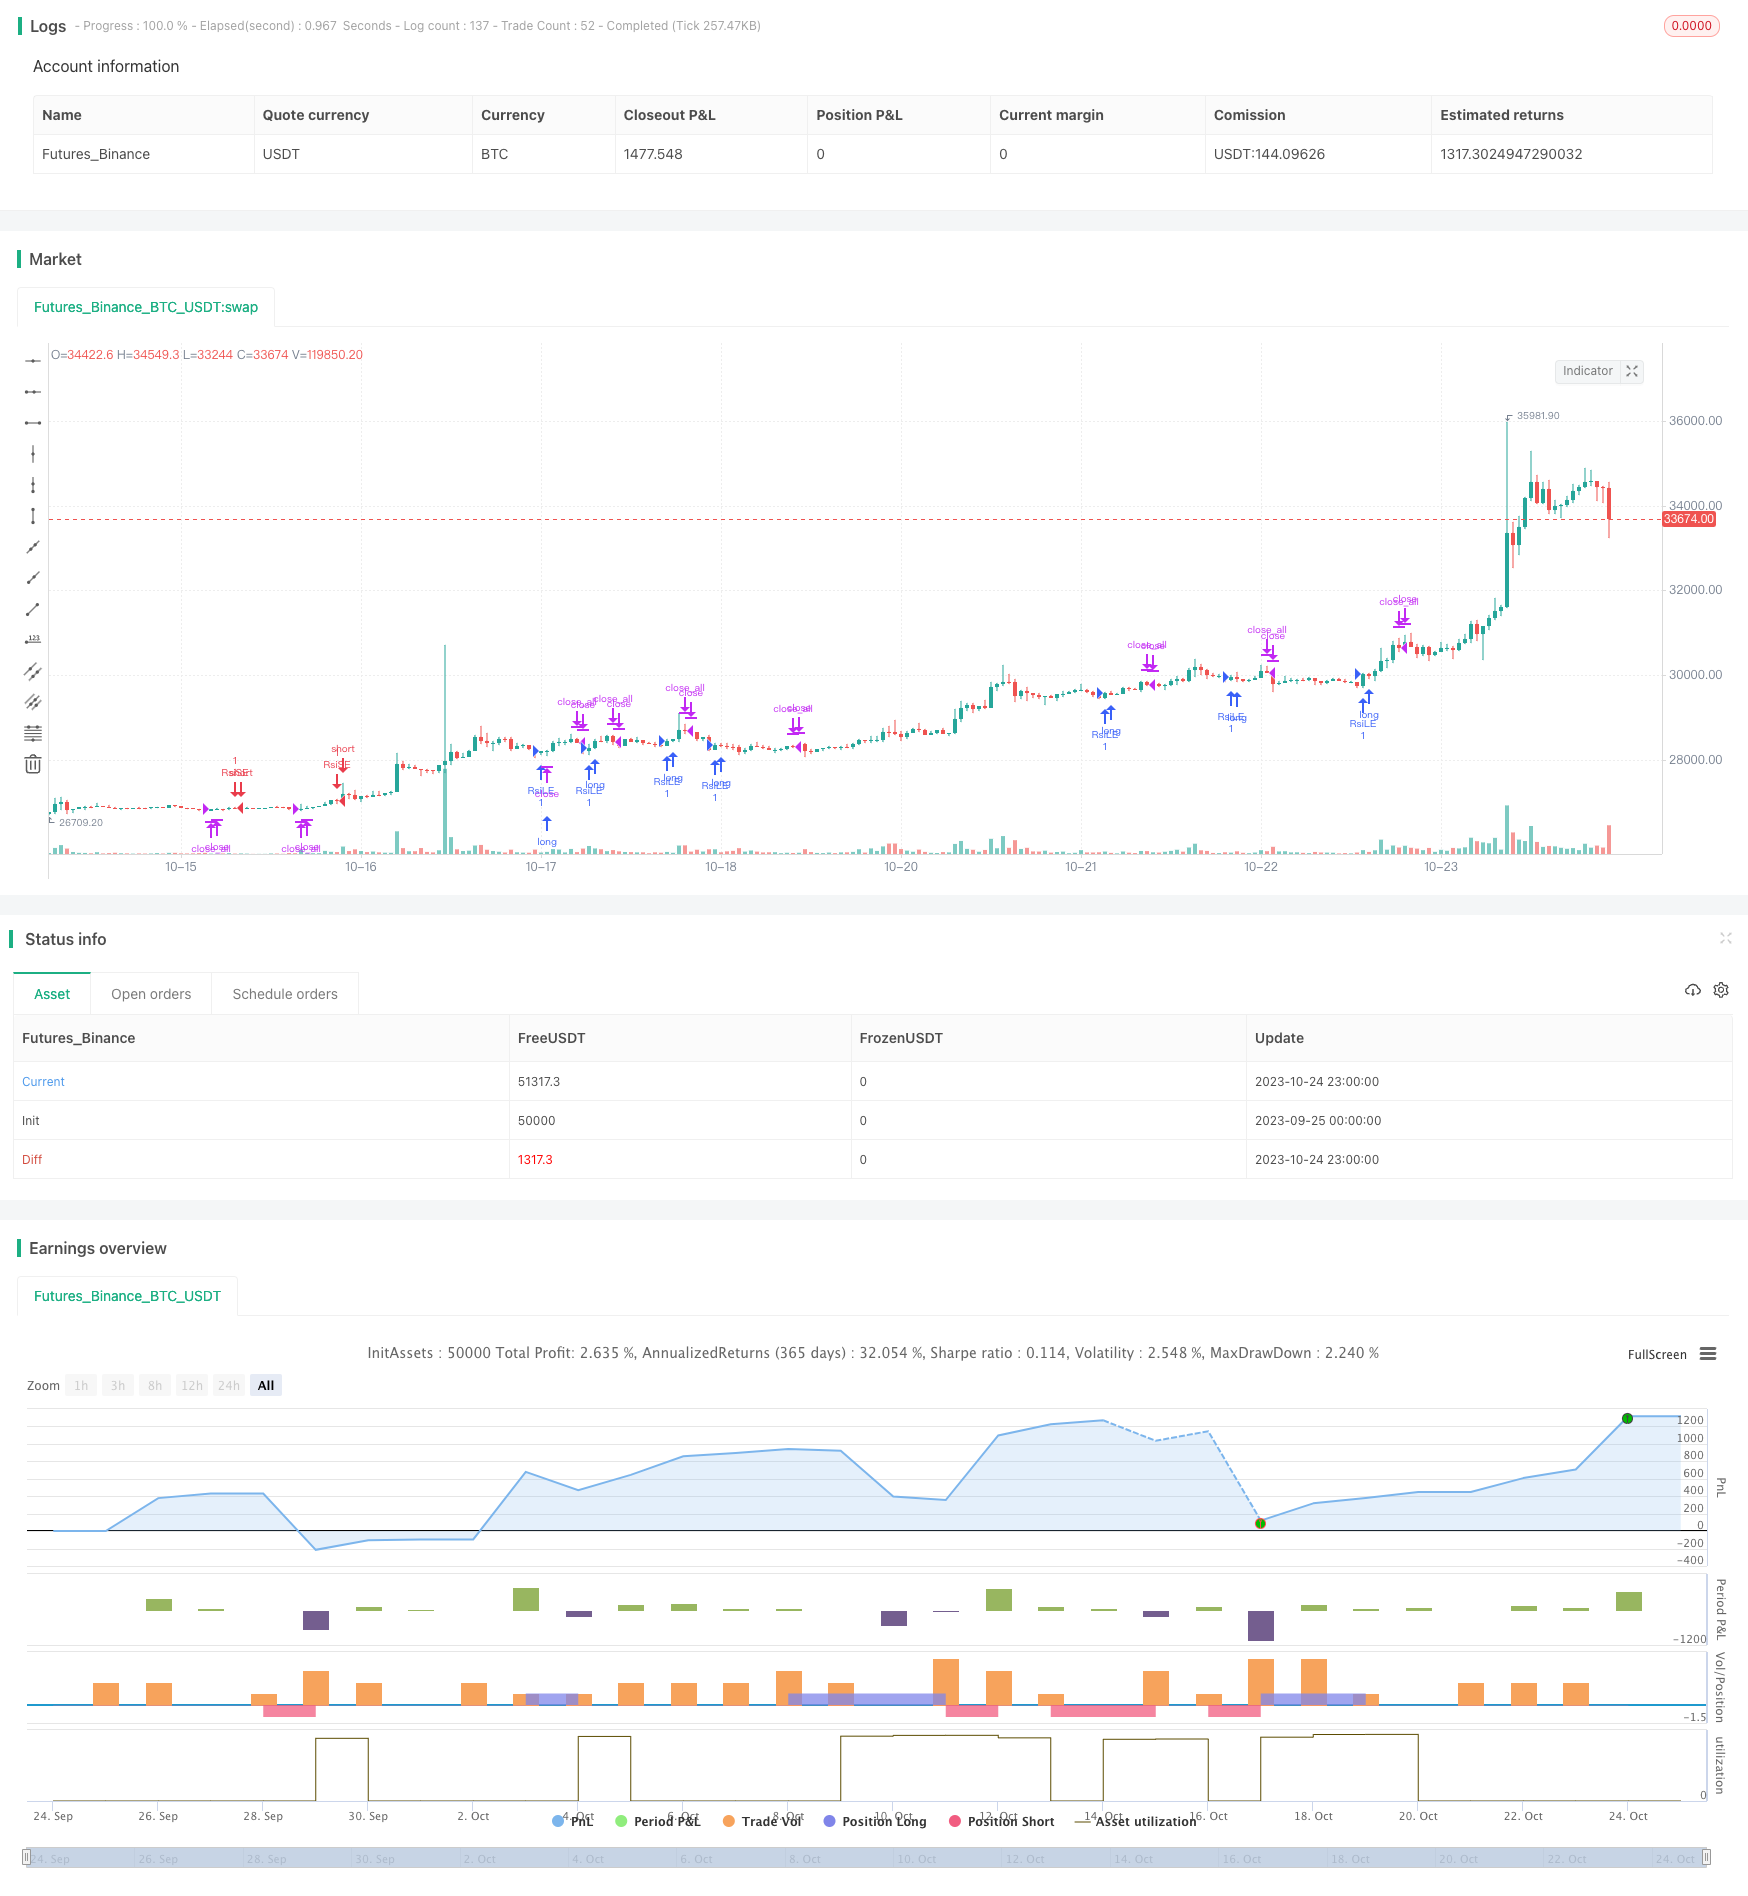
Overview
The RSI Momentum Long Short strategy is a typical momentum strategy based on the Larry Connors RSI indicator, using the overbought and oversold signals from RSI to determine entries and exits. The key is to identify whether the price is in overbought or oversold status and use that as trading signals.
Strategy Logic
The strategy constructs RSI indicator by calculating the upside momentum and downside momentum of prices over a lookback period. RSI below oversold line 10 is considered oversold, while RSI above overbought line 90 is considered overbought. The strategy generates long signals when RSI crosses oversold line from below, and generates short signals when RSI crosses overbought line from above.
Additional moving average filters are added - only allowing long signals when 5day MA is above 200day MA, and short signals when 5day MA is below 200day MA. This helps filter out false signals from short-term rebounds.
Profit taking mechanisms are also introduced. Existing long positions will be closed out when RSI crosses above overbought line 90. Existing short positions will be closed out when RSI crosses below oversold line 10. This locks in profits and avoids increasing losses.
Advantages of the Strategy
Using RSI to identify overbought/oversold levels catches price reversal moments.
Adding MA filters reduces false signals from short-term noise.
Profit-taking mechanics help control risks and limit losses.
Simple and clear rules, easy to understand and implement.
RSI is a widely used and practical indicator, suitable for many instruments.
Risks of the Strategy
RSI overbought/oversold may not always result in reversal.
MA filters could also filter out good trading opportunities.
Improper profit-taking settings give up trends too early.
Parameters like RSI lookback, overbought/oversold levels, MA settings need tuning.
Risks can be reduced via parameter optimization, combining other indicators, flexible profit-taking, etc.
Enhancement Opportunities
Test RSI with different lookback periods.
Add other indicators like KDJ, MACD to supplement RSI.
Adjust overbought/oversold levels based on market regimes.
Fine tune profit-taking RSI levels based on holding period.
Incorporate stop loss strategies based on max loss percentage.
Optimize MA system, use dynamic trailing stop loss.
Conclusion
The RSI Momentum Long Short Strategy catches short-term reversal opportunities by using RSI to identify overbought/oversold levels, filtered by MAs and profit-taking rules. The strategy is simple and practical, worth further testing and enhancement to adapt to diverse markets. Overall it provides a good framework that can serve as a reference for quantitative trading strategy development.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Entry area |
| v_input_2 | 90 | overBought |
| v_input_3 | 10 | overSold |
Source Pine Script
/*backtest
start: 2023-09-25 00:00:00
end: 2023-10-25 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//authour: SudeepBisht
//@version=3
//Based on Larry Connors RSI-2 Strategy - Lower RSI
strategy("SB_CM_RSI_2_Strategy_Version 2.0", overlay=true)

src = close
entry= input(defval=0,title="Entry area")
entry:=nz(entry[1])
overBought=input(90)
overSold=input(10)
//RSI CODE
up = rma(max(change(src), 0), 2)
down = rma(-min(change(src), 0), 2)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
//Criteria for Moving Avg rules
ma5 = sma(close,5)
ma200= sma(close, 200)

//Rule for RSI Color
col = close > ma200 and close < ma5 and rsi < 10 ? lime : close < ma200 and close > ma5 and rsi > 90 ? red : silver
chk= col==red?-1:col==lime?1:0

if (not na(rsi))
    if (crossover(rsi, overSold))
        if(chk[1]==1)
            strategy.entry("RsiLE", strategy.long, comment="RsiLE")
            entry:=1
    if (crossunder(rsi, overBought))
        if(chk[1]==-1)
            strategy.entry("RsiSE", strategy.short, comment="RsiSE")
            entry:=-1

if (not na(rsi))
    if (crossover(rsi, overSold) and entry==-1)
        strategy.close_all()
        //strategy.entry("RsiLE", strategy.long, comment="RsiLE")
        entry:=0
    if (crossunder(rsi, overBought) and entry==1)
        strategy.close_all()
        //strategy.entry("RsiSE", strategy.short, comment="RsiSE")
        entry:=0
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Momentum-Long-Short-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- MACD Momentum Indicator Backtest StrategyPine Script · Momentum · 1h
- MoonFlag MACD Momentum StochRSI Trading StrategyPine Script · Momentum · 1d
- Multi Indicator MACD Momentum Options Strategy with Risk Controlled Percentage Based ExitsPine Script · Momentum · 1h
- Multi Indicator Probability Threshold Momentum Trend Trading StrategyPine Script · Momentum · 1d
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h