Strategy vault / Mean reversion
RSI of MACD Reversal Strategy
This strategy is based on the RSI values of the MACD indicator to determine buy and sell signals. It buys when the RSI exceeds the overbought line or range, and sells or stops profit/loss when the RSI breaks below…
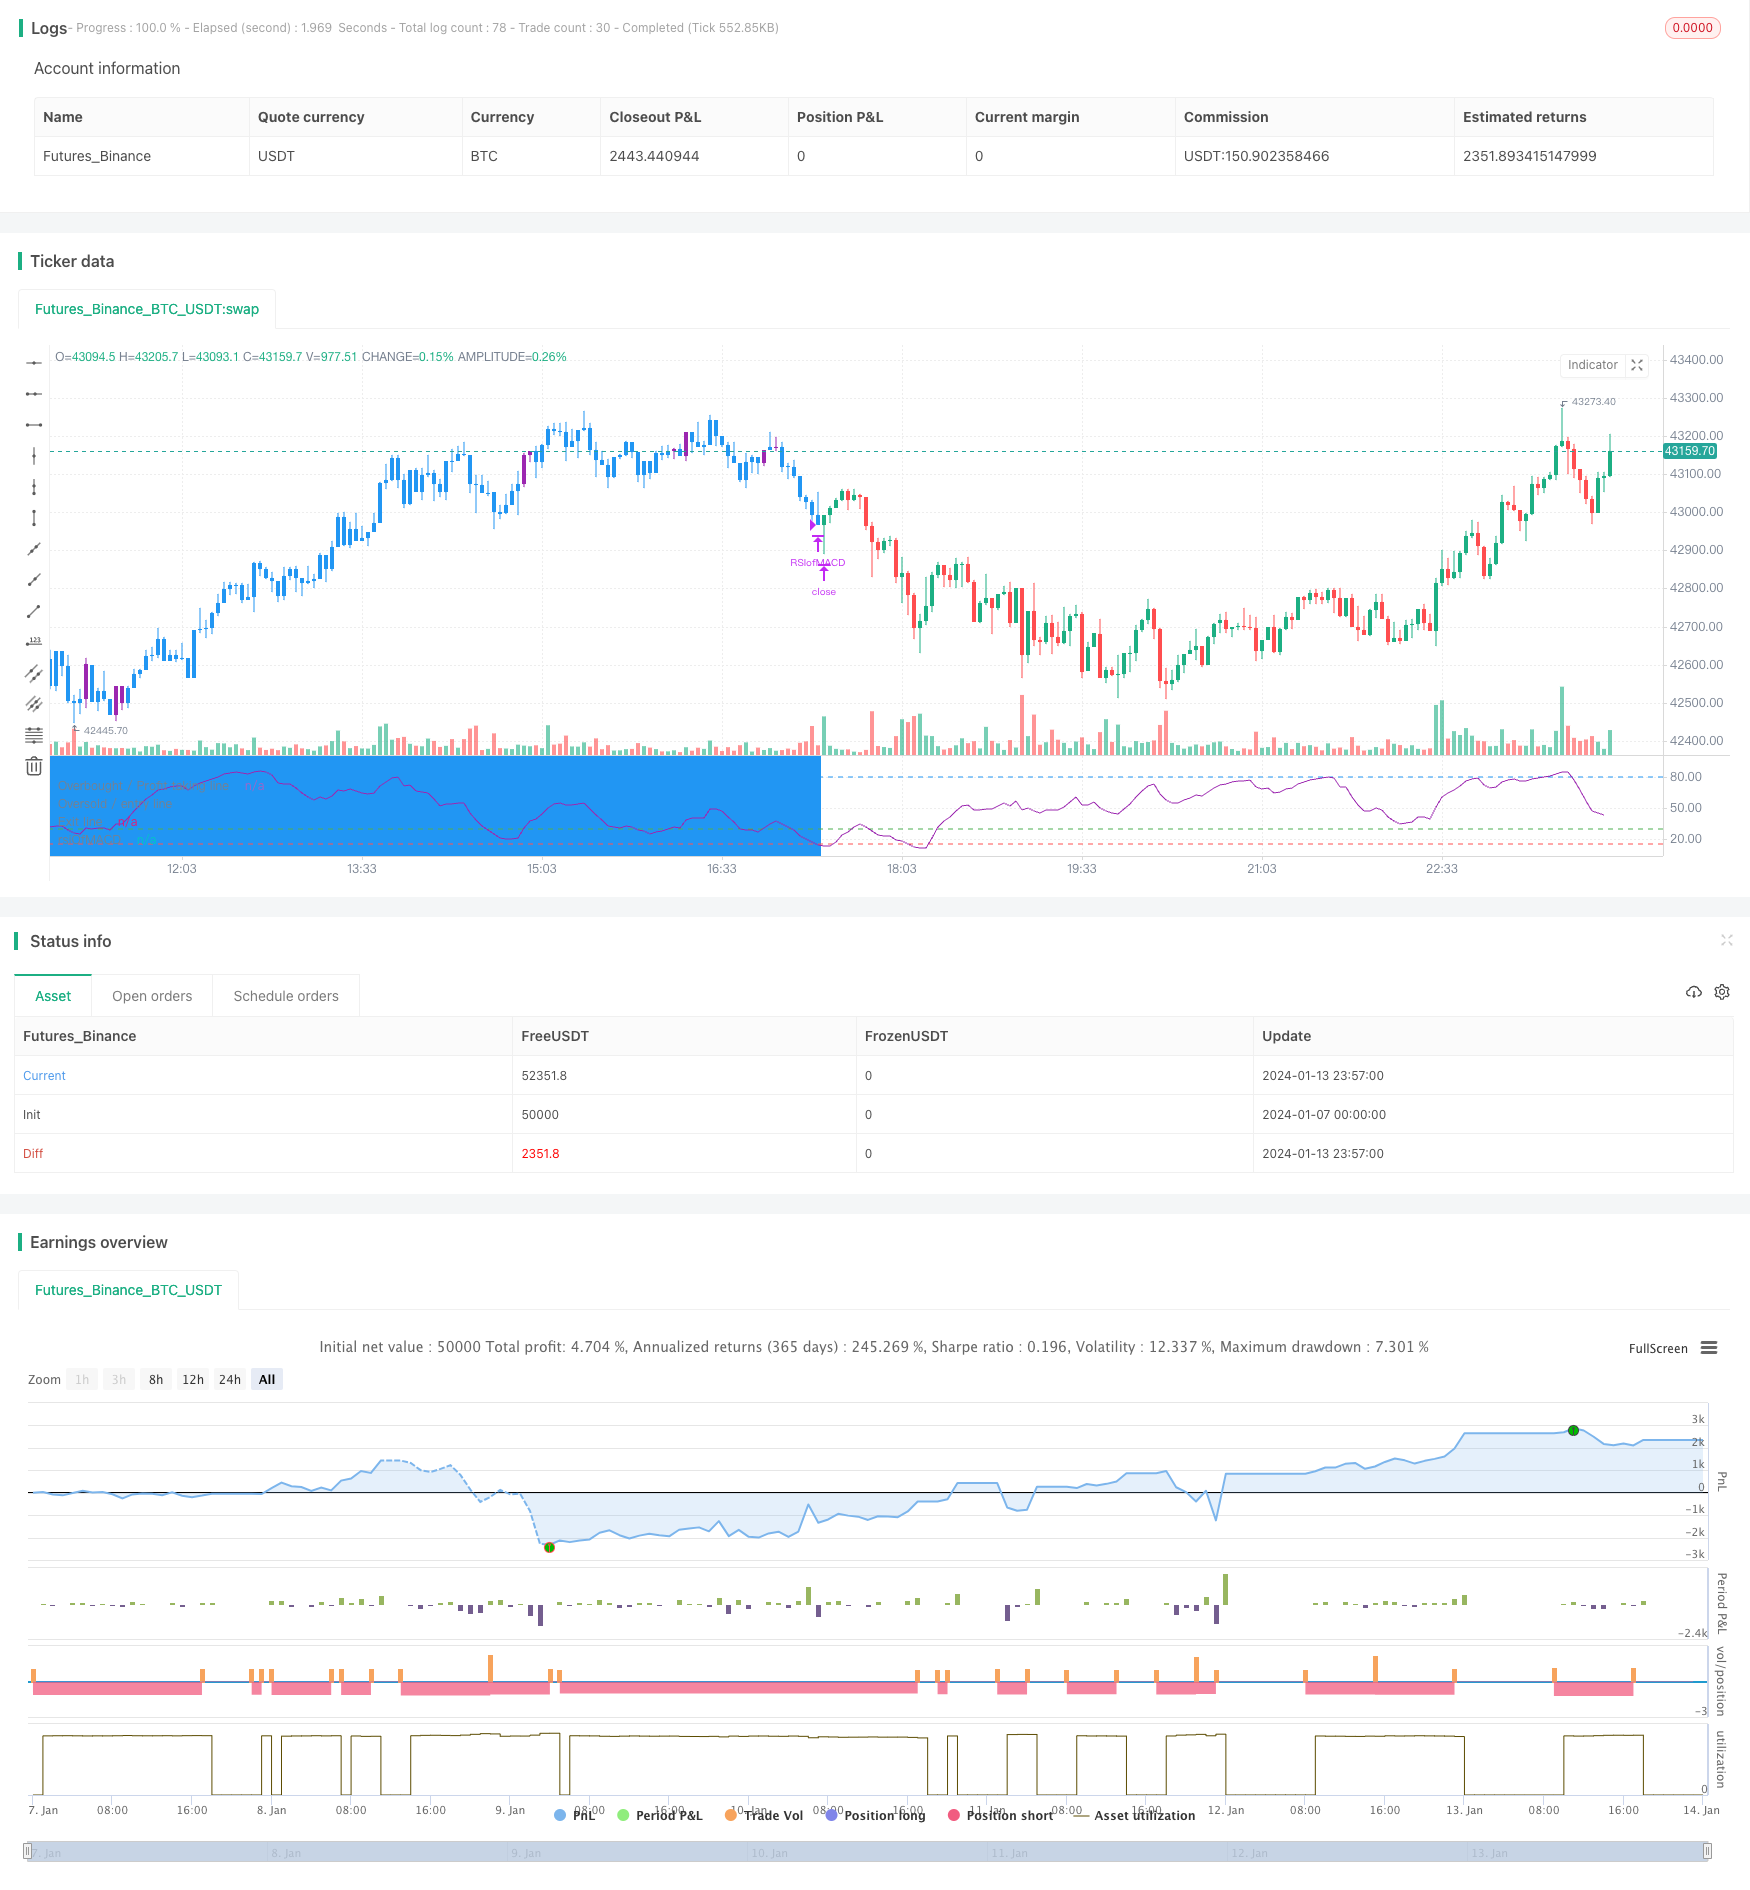
Overview
This strategy is based on the RSI values of the MACD indicator to determine buy and sell signals. It buys when the RSI exceeds the overbought line or range, and sells or stops profit/loss when the RSI breaks below the overbought range.
Strategy Principle
This strategy combines the advantages of both the MACD and RSI indicators.
First, the three curves of the MACD indicator are calculated, including the DIF, DEA and MACD lines. Then the RSI indicator is calculated on the MACD line to form the RSI of MACD.
When the RSI of MACD indicator exceeds the overbought range of 30 or 35, a buy signal is generated, indicating the MACD line has entered the oversold range and the price trend has started to reverse upwards. When the RSI of MACD indicator breaks below the overbought range of 15 again, a sell signal is generated, indicating the trend reversal has ended.
The strategy also sets partial profit taking. When the RSI of MACD indicator exceeds the overbought level of 80, part of the position can be sold to lock in partial profits.
Advantage Analysis
- Utilize MACD indicator to determine trend reversal points
- Utilize RSI indicator to determine overbought/oversold levels to filter fake signals
- Combination of dual indicators for accurate buy/sell points
- Partial profit taking set to prevent enlarged losses
Risk Analysis
- Inaccurate judgement of trend if improper MACD parameters
- Inaccurate judgement of overbought/oversold zones if improper RSI parameters
- Potentially missing greater upside if profit taking too aggressive
Solutions:
- Optimize MACD parameters to find best combination
- Optimize RSI parameters to improve accuracy
- Relax profit taking criteria properly to target greater returns
Optimization Directions
The strategy can also be optimized in the following aspects:
- Add stop loss strategy to further control downside risks
- Add position sizing module to gradually ramp up positions as price moves
- Integrate machine learning models trained on historical data to further improve buy/sell point accuracy
- Attempt running on shorter timeframes like 15m or 5m to improve strategy frequency
Conclusion
The overall strategy design philosophy is clear, with the core idea of using MACD reversal combined with RSI filter to determine buy/sell points. With parameter optimization, stop loss management, risk control measures etc., it can be shaped into a very practical quant trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | Fast Length |
| v_input_2 | 21 | Slow Length |
| v_input_3 | 9 | Signal Length |
| v_input_4 | 14 | RSI of MACD Length |
| v_input_5 | 10 | Risk % of capital |
| v_input_6 | 3 | Stop Loss |
| v_input_7 | false | Take Profit |
Source Pine Script
/*backtest
start: 2024-01-07 00:00:00
end: 2024-01-14 00:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © mohanee

//@version=4

strategy(title="RSI of MACD Strategy[Long only]",  shorttitle="RSIofMACD" , overlay=false, pyramiding=1,     default_qty_type=strategy.percent_of_equity,  default_qty_value=20, initial_capital=10000, currency=currency.USD)  //default_qty_value=10, default_qty_type=strategy.fixed,


/////////////////////////////////////////////////////////////////////////////////


// MACD Inputs ///
fastLen = input(12, title="Fast Length")
slowLen = input(21, title="Slow Length")
sigLen  = input(9, title="Signal Length")

rsiLength  = input(14, title="RSI of MACD Length")


riskCapital = input(title="Risk % of capital", defval=10, minval=1)
stopLoss=input(3,title="Stop Loss",minval=1)

takeProfit=input(false, title="Take Profit")


[macdLine, signalLine, _] = macd(close, fastLen, slowLen, sigLen)

rsiOfMACD = rsi(macdLine, rsiLength)
emaSlow = ema(close, slowLen)


//drawings
/////////////////////////////////////////////////////////////////////////////////


obLevelPlot = hline(80, title="Overbought / Profit taking line",  color=color.blue , linestyle=hline.style_dashed)
osLevelPlot = hline(30, title="Oversold / entry line", color=color.green, linestyle=hline.style_dashed)

exitLinePlot = hline(15, title="Exit line", color=color.red, linestyle=hline.style_dashed)


plot(rsiOfMACD, title = "rsiOfMACD" ,  color=color.purple)


//drawings
/////////////////////////////////////////////////////////////////////////////////


//Strategy Logic
/////////////////////////////////////////////////////////////////////////////////

//Entry--
//Echeck how many units can be purchased based on risk manage ment and stop loss
qty1 = (strategy.equity  * riskCapital / 100 ) /  (close*stopLoss/100)

//check if cash is sufficient  to buy qty1  , if capital not available use the available capital only
qty1:= (qty1 * close >= strategy.equity ) ? (strategy.equity / close) : qty1


strategy.entry(id="RSIofMACD", long=true,   qty=qty1,  when =  ( crossover(rsiOfMACD, 30) or crossover(rsiOfMACD, 35)  ) and close>=emaSlow )


bgcolor(abs(strategy.position_size)>=1 ? color.blue : na , transp=70)


barcolor(abs(strategy.position_size)>=1 and  ( crossover(rsiOfMACD, 30) or crossover(rsiOfMACD, 35) ) ? color.purple : abs(strategy.position_size)>=1 ? color.blue : na  )


//partial exit
strategy.close(id="RSIofMACD", comment="PExit Profit is "+tostring(close - strategy.position_avg_price,  "###.##")  ,  qty=strategy.position_size/3, when= takeProfit and abs(strategy.position_size)>=1 and close > strategy.position_avg_price and crossunder(rsiOfMACD,80) )

//Close All
strategy.close(id="RSIofMACD", comment="Close All   Profit is "+tostring(close - strategy.position_avg_price,  "###.##"), when=abs(strategy.position_size)>=1 and crossunder(rsiOfMACD,15) ) //and close > strategy.position_avg_price )


//Strategy Logic
/////////////////////////////////////////////////////////////////////////////////
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-of-MACD-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Chaikin Oscillator StrategyPine Script · Mean reversion · 3h
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d